Individual Economists

Mamdani Moves To Ban Horse Carriages From NYC, Drivers React

Zero Hedge -

Mamdani Moves To Ban Horse Carriages From NYC, Drivers React

Authored by Nicholas Zifcak via The Epoch Times,

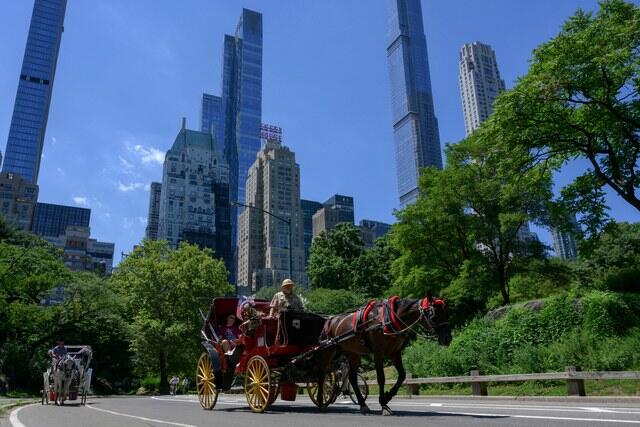
Mayor Zohran Mamdani has confirmed that he and the City Council speaker have agreed to phase out carriage horse rides in Central Park, a win for animal rights activists who have long opposed the rides.

The mayor said he would make sure workers and owners are protected as the rides wind down, with an end date of June 1, 2028.

"I think that we have a civic responsibility to ensure that we are not leaving anybody out to dry," Mamdani said at an unrelated press conference Oct. 14. The City Council announced it will vote on the bill ending carriage rides on Oct. 22.

The Transport Workers Union, which represents the carriage drivers, denounced the text of the bill as noncommittal, with "no meaningful economic relief for workers." The bill does not require the city to compensate the 68 owners for their city-issued license or medallion.

Mamdani said the city's plan will become more explicit and options are still being discussed. The mayor said he would make sure owners and workers won't be made to pay "for the sunsetting of an industry."

However, drivers say they feel they have been treated poorly, and that the City Council has no solid justification for the ban.

In a statement, the union denounced City Council Speaker Julie Menin for what it described as using "the tragic death of a tourist to contrive a public safety crisis."

On June 17, Romanch Mahajan, 18, a tourist visiting from India, was thrown from a carriage after the horse spooked and bolted during a ride with his family. Mahajan hit his head and died. After his death, Menin announced her support for the ban in a video on X.

Carriage horse drivers argue the issue is not public safety. Mahajan's death is the first in more than 160 years of horse-drawn carriages operating under the union in Central Park, compared to as many as 28 deaths related to bikes, e-bikes, and scooters on New York streets in 2026 alone. Menin and Mamdani have yet to set new safety measures on e-bikes and scooters.

Animal rights groups have long sought to end the carriage horses in Central Park, launching social media campaigns whenever there is a horse-related incident, such as the death of a carriage horse named Deniz on June 9 after he ate Japanese yew growing in the park.

Animal rights group New Yorkers for Clean, Livable, and Safe Streets (NYCLASS) reacted on X to the ban.

"For decades, NYCLASS fought to end cruel and dangerous horse carriages," it wrote. "It took the extraordinary courage, compassion, and unwavering leadership of Speaker Menin."

Drivers say that the horses are well-treated and that extensive city rules govern their feeding schedule, what time of day they can work, as well as the temperature range during which horses are not allowed to work (18 degrees or colder, 90 degrees or warmer). The city also mandates an eight-hour workday and five weeks of vacation time for the horses every year.

'No Way!'

Carriage license owner Ahmet Bilici, who trained as a veterinarian in Turkey before coming to the United States in 2001, became a carriage driver to support himself as he was learning English. The job stuck, and he's been a driver for 23 years. He said that if the City Council wanted to work with carriage drivers, drivers would be amenable, but that City Council just wants a ban.

"When you take this carriage from me, I am going to lose my quarter century! No way!" he said. "I trusted the city because the city licensed the medallion, and now you are shutting down? No way!"

Bilici said the ban will hurt 300 families if you count support staff, which includes stable workers, blacksmiths producing horseshoes, and craftsmen making saddles.

"This is my small business, my investment. It's like my house. You're burning my house!"

Bilici said that if the city shuts down the carriage rides, it must compensate drivers.

"There's no way we can accept this," he said.

Another driver, Danielle Slot, also said she was extremely disappointed. She thinks there is no solid justification for the ban.

"Our City Council is supposed to look out for people and represent people, and they're supposed to see through these things," said Slot, referring to the long-term campaign of NYCLASS head Steven Nislick to ban carriage horses, which dates to 2008.

Slot previously worked with horse-drawn carriages on Michigan's Mackinac Island, a 4-square-mile island in Lake Huron that never welcomed automobiles and still relies on horse-drawn carriages.

"I've just completely lost faith in the government here, which is very sad," said Slot. "It feels like they're capitalizing on sensationalism."

Slot said she voted for Mamdani.

She said City Council members are unaware of the realities of the equine industry, thinking as if a new home can easily be found for horses where they won't need to work. The proposed ban requires owners to make sure horses are not sold off to other carriage drivers out of state.

"It's a really nice thought that there would be some magical sanctuary. But it's just not realistic," said Slot, who added that caring for horses costs thousands of dollars a year. She said those on the City Council supporting the bill either don't know, or they don't care.

Slot moved to New York to work as an actor and is still pursuing her career in the performing arts. She said she came to New York in part "because this is a place where I feel like people are protected, people can be who they want to be," but she said her experience with the ban on horse-drawn carriages makes her feel the political system is compromised.

Tyler Durden Fri, 10/16/2026 - 10:10

Trump Unloads On Zelensky In Lengthy Interview Tirade: 'He's Not A Good Guy'

Zero Hedge -

Trump Unloads On Zelensky In Lengthy Interview Tirade: 'He's Not A Good Guy'

In a rarity, President Trump spent a good amount of time in a fresh Newsmax sit-down interview lambasting Ukraine's President Volodymyr Zelensky, a longtime Washington ally who has been the recipient of billions in US arms and funds.

At a moment Zelensky has resisted Trump's call to stop striking Russian oil refineries, Trump bashed the Ukrainian leader as "not a good guy for (the US) to deal with." Watch Trump put Zelensky on blast...

He lamented that the Ukrainian president does not want to help bring an end to the war, now it its fifth year.

"He says he wants to settle, but he doesn't. I'm not a big fan of Zelensky. They've destroyed that country," the US president said, ultimately laying blame the blame also on the prior Biden administration.

Trump said it is the Ukraine war - and not the Iran war which he started with his Operation Epic Fury - that is driving up global energy prices.

"Now, if you tell me that Zelensky is again shooting at refineries, all he's doing is making the world oil price higher," Trump stated.

"Well, I think that's a disgrace. There's plenty of other targets... There are a lot of targets that you can hit," the president continued.

Trump goes after Zelensky extensively in the interview, not holding back:

"But when you shoot at diesel refineries where you make, you know, diesel oil and we need that and the world needs that, then he's not doing a good service for the world" - Trump said further of Zelensky.

The American president again went so far as to say it's time for a new Ukrainian leader, and that fresh elections must be held.

"I think you need an election because there's nobody that's telling me that the people of Ukraine are satisfied having missiles hitting their apartment building," Trump said.

Concerning the admitted ongoing difficulty of getting the two warring sides to the negotiating table, Trump described, "As you know, Putin hates Zelenskyy, and Zelensky hates Putin. And when you have that kind of hatred, it's very hard to get something settled."

Trump has engaged in plenty of prior public critiques of Zelensky, but again - it's unusual for him to sit down with a conservative outlet and offer lengthy commentary on how Zelensky is failing.

Show host Rob Finnerty looks briefly shocked when Trump bluntly says "I find Zelensky to be more difficult to deal with than Putin"...

This week there are signs that the US may be cutting back intelligence-sharing with Kiev, also amid Ukrainian outrage at the diesel deal with Putin announced last week. Ukraine has continued refinery strikes, also with Zelensky saying that Trump's prior proclaimed 'energy ceasefire' was "news to me".

* * *

Tyler Durden Fri, 10/16/2026 - 09:55

US Industrial Production Is Growing At The Fastest Pace In 4 Years As Manufacturing Rebounds

Zero Hedge -

US Industrial Production Is Growing At The Fastest Pace In 4 Years As Manufacturing Rebounds

Amid hot inflation (CPI, PPI, Import/Export prices) and AI-infected growth scares, US Industrial Production data this morning added another twist, printing far better than expected as capacity utilization picked up further in September.

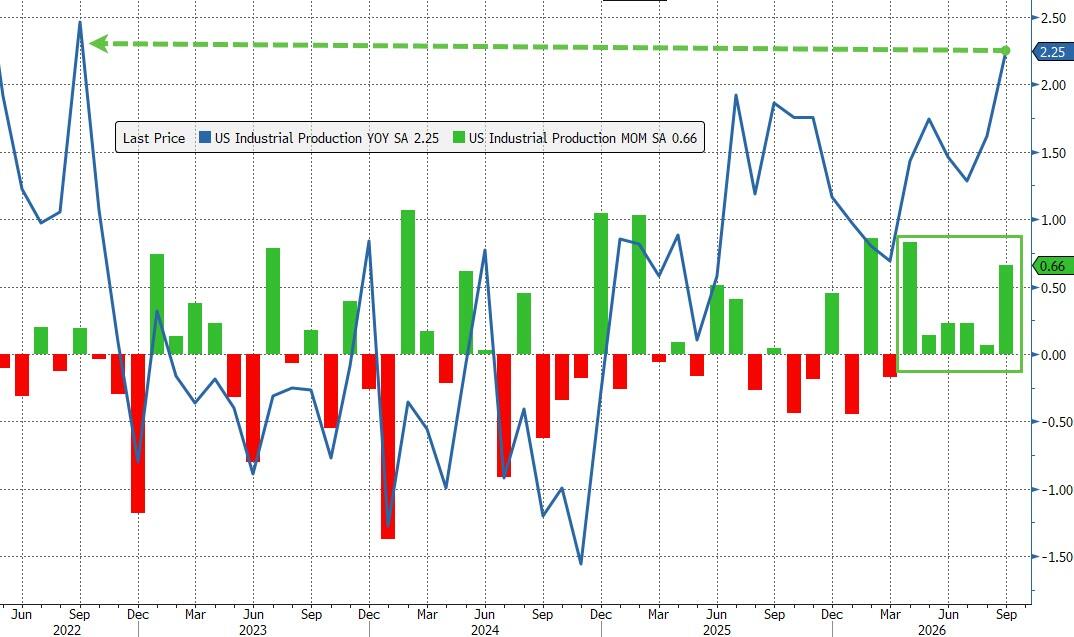
Headline Industrial Production rose 0.7% MoM in September (almost double the 0.5% MoM expected) with August's unchanged revised up to +0.1% MoM. That is the sixth straight month of gains for industrial production...

...lifting the annual increase in US industrial production to +2.25% - the highest since Sept 2022.

Utilities were the main driver: +3.5% in September (and a strong +14.8% annual rate in Q3) and Mining picked up.

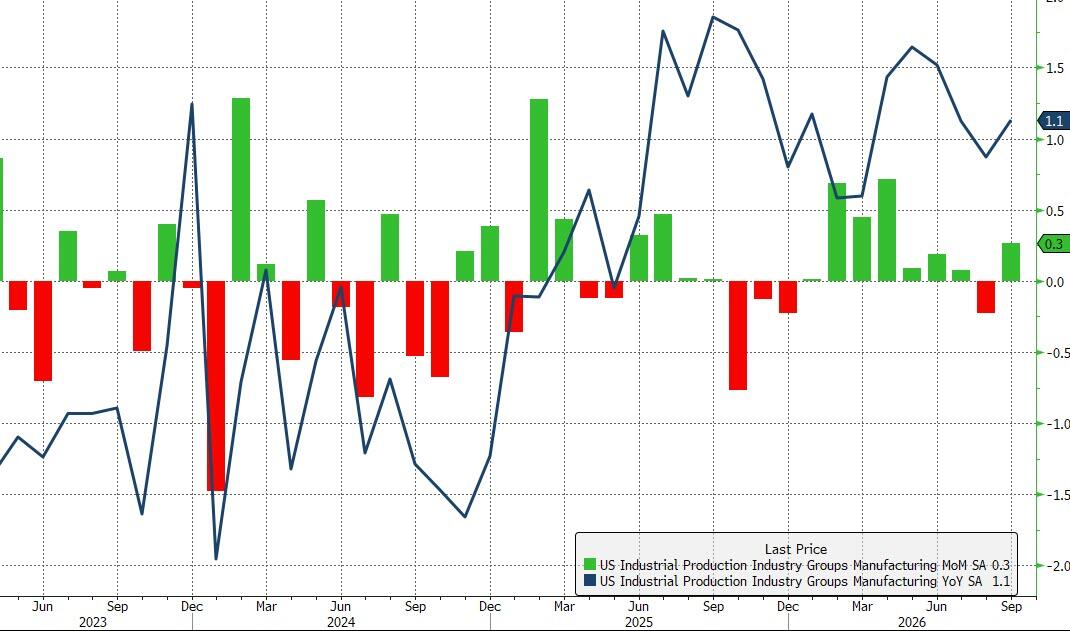
US Manufacturing rebounded from August's dip (better than expected)...

Durable manufacturing was up only slightly as motor vehicles & parts fell 3.0%. Nondurables rose 0.4%, though semiconductors and related components were very strong.

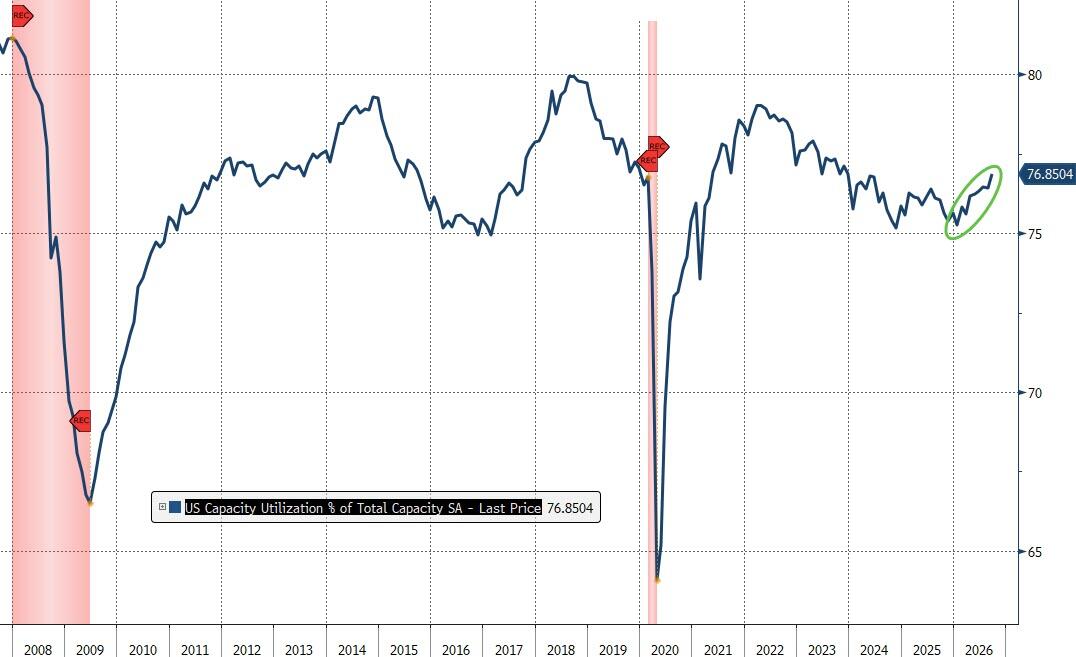
Capacity Utilization also surprised to the upside (76.9% vs 76.5% exp).

That is the highest since Dec 2023 (but still 2.5 percentage points below its long-run (1972–2025) average).

Nevertheless, it was a clear beat on the side of growth (albeit uneven as autos lagged), driven largely by utilities, with manufacturing showing a modest rebound after prior softness.

Tyler Durden Fri, 10/16/2026 - 09:34

Rate Hike Odds Tumble After Warsh Does Not Address October FOMC Meeting

Zero Hedge -

Rate Hike Odds Tumble After Warsh Does Not Address October FOMC Meeting

In our morning wrap we said that market sentiment was boosted overnight following Kevin Warsh's speech at the IMF meeting in Bangkok, specifically "The day's driver is Warsh (or rather what he didn't say): with the blackout starting Saturday, the Fed chair declined to push back on rate expectations and instead talked up a "massive investment surge" from AI."

Goldman set the context, with its chief economist Jan Hatzius writing in a note overnight that in comments at the IMF’s annual meetings, Fed Chairman Kevin Warsh did not specifically address the FOMC’s upcoming October meeting but said that “in the intermeeting period, the world has broadly conformed to our expectations [at the September meeting].” Hatzius adds that "alongside other recent comments from FOMC participants, Warsh’s comments indicate that the FOMC is set to pause in October. We continue to expect a second and final hike in December."

Below we excerpt the highlights from Goldman's note:

  • In comments at the IMF’s annual meetings, Fed Chairman Kevin Warsh did not specifically address the FOMC’s upcoming October meeting but said that “in the intermeeting period, the world has broadly conformed to our expectations [at the September meeting].”
  • In other recent comments from FOMC participants, Fed Vice Chair for Supervision Bowman said, “I don’t feel any urgency for taking further action at this point.” San Francisco Fed President Daly, speaking after the firmer than expected September CPI report, likewise said that she did not see an urgent need “to decide with a limited set of information.”
  • Taken together, these comments indicate that the FOMC is set to pause in October. We continue to expect a second and final hike in December.
  • In other comments during his fireside chat, Warsh highlighted that the US is experiencing “a massive investment surge” related to the AI buildout. He also noted that there has been a “synchronous tightening in monetary policy around the world” recently. 

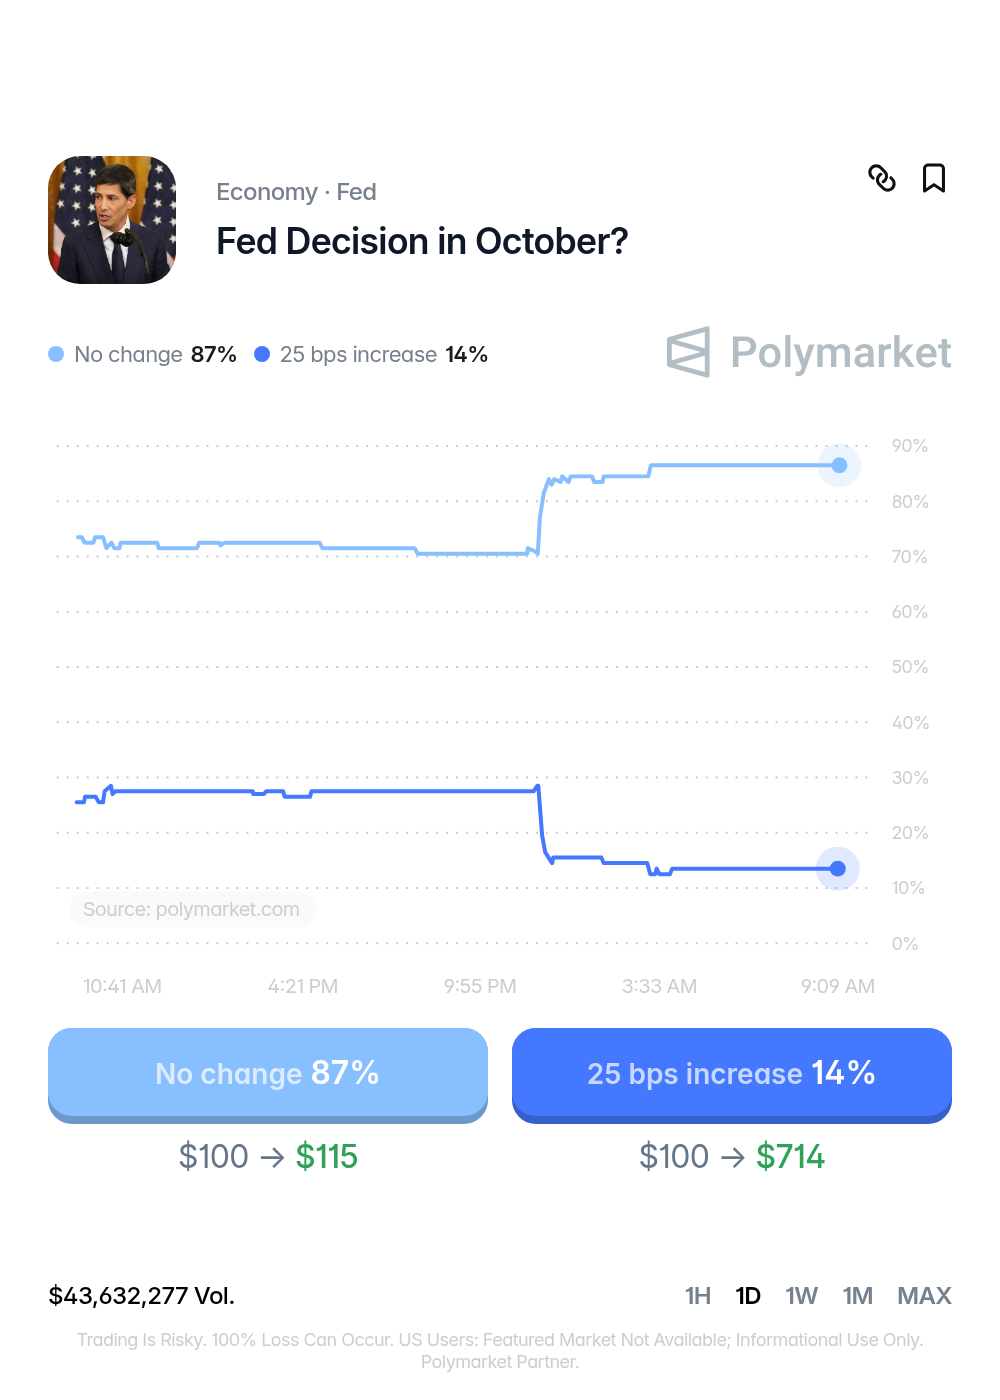
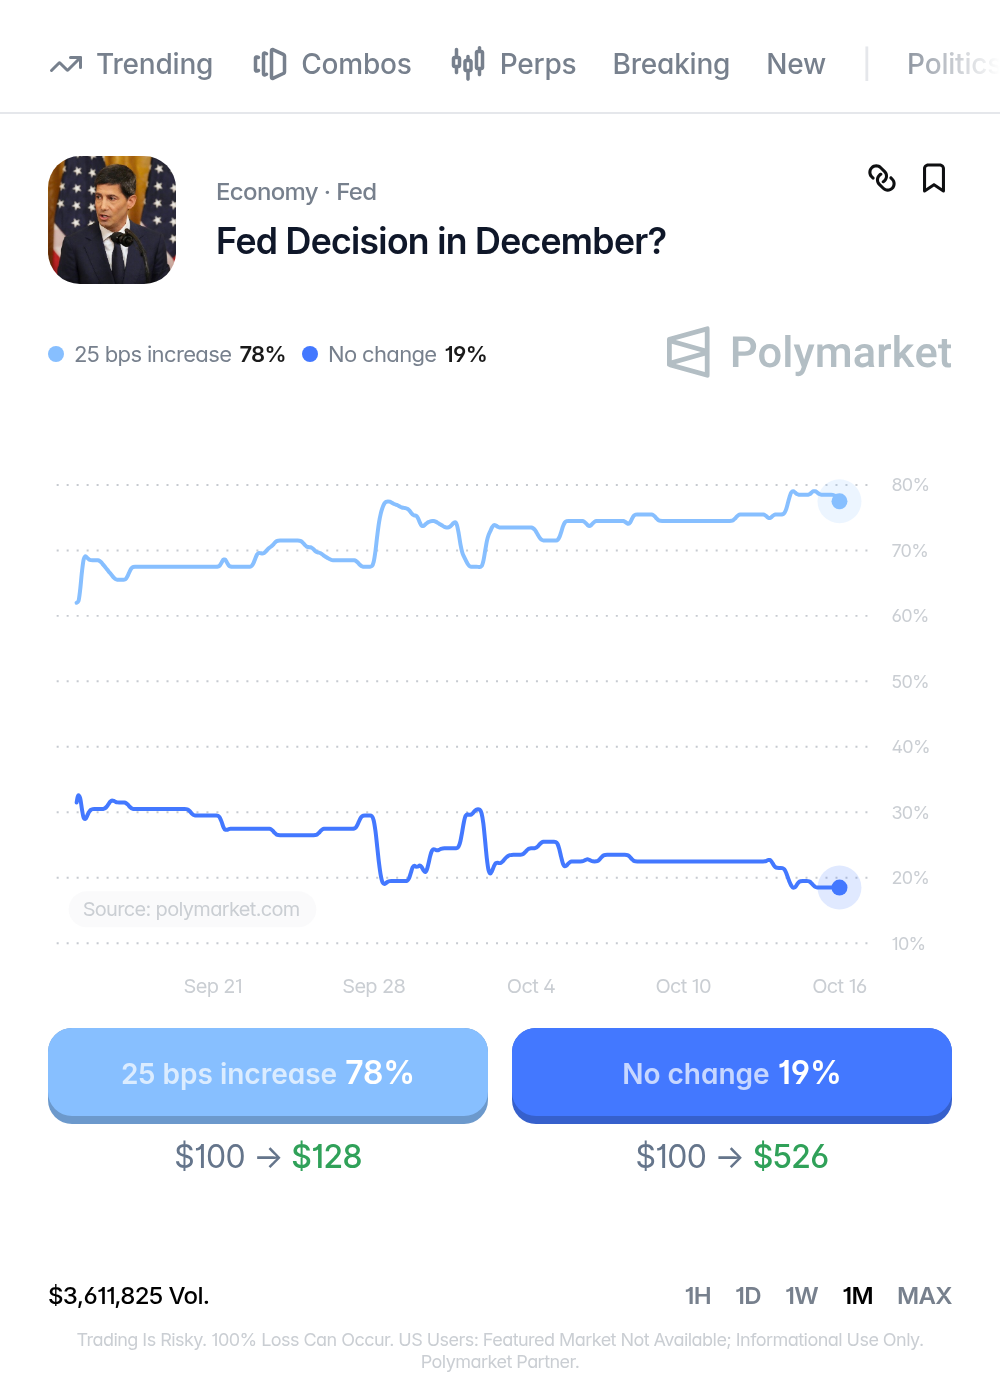
Warsh's comments, or rather lack thereof, coupled with the market's interpretation that his lack of priming an October hike (which is hardly surprising for a Fed chair who has repeatedly refused to offer forward guidance) means one isn't coming, was enough to send October rate hike odds sharply lower, or 13%, less than half where they were before Warsh...

... even as odds of a December rate hike rose to new contract highs.

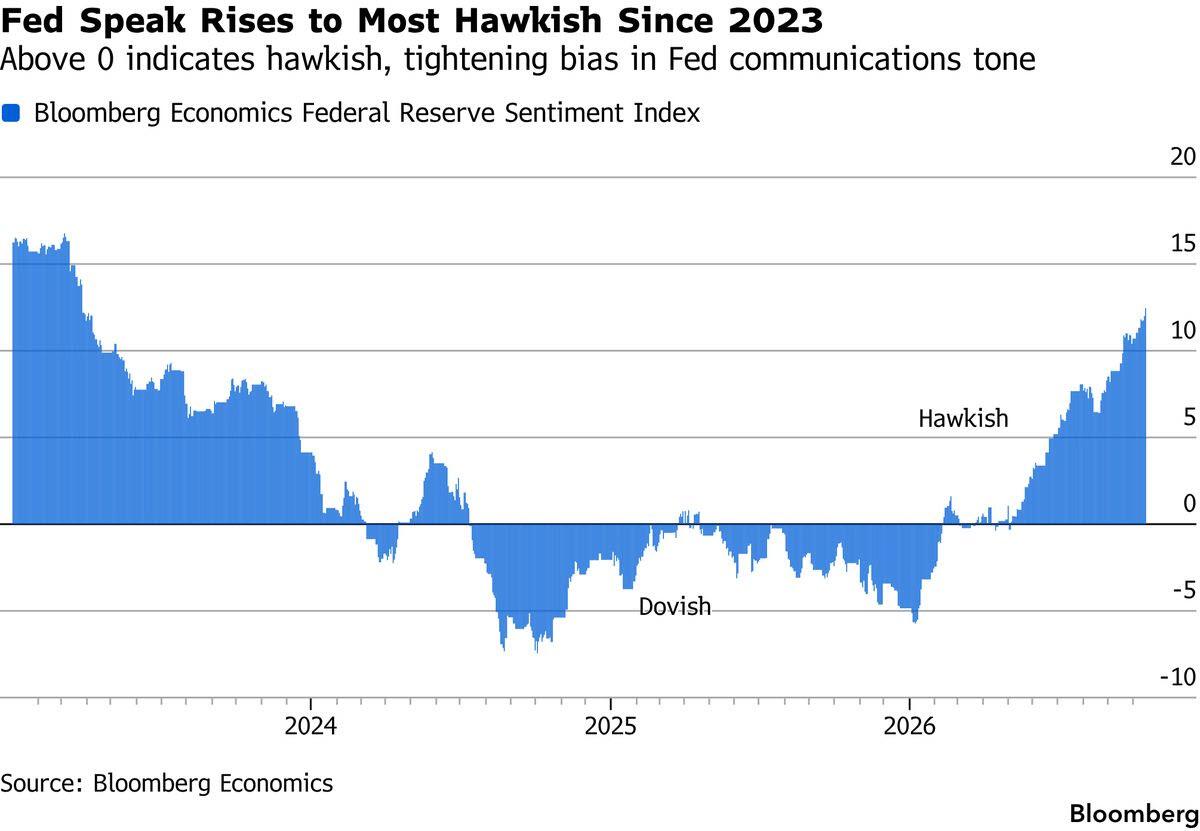
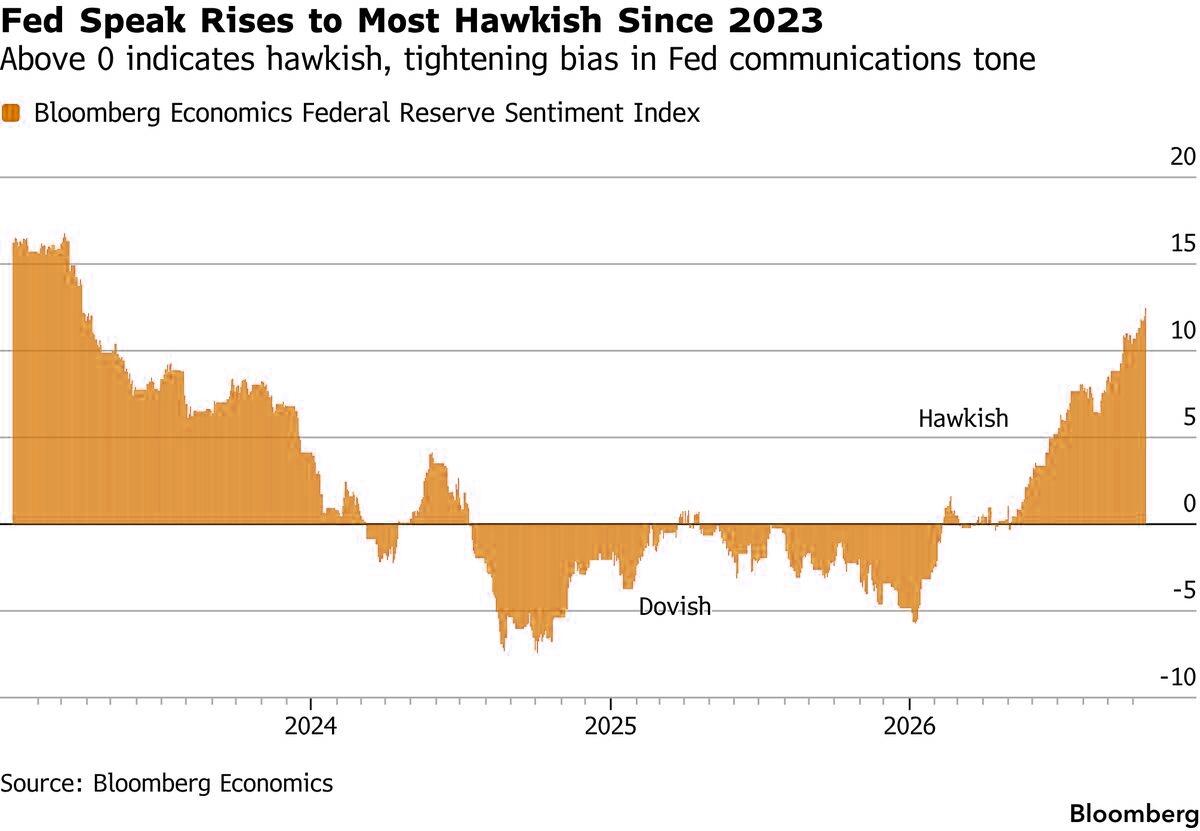
One possible reason for the market's near certainty that a rate hike is coming in the year's final FOMC meeting: the Bloomberg Economics Federal Reserve Sentiment Index continues to rise, now at its highest level since 2023

More in the full Goldman note available to pro subs.

Tyler Durden Fri, 10/16/2026 - 09:26

Bad Inflation Cures Itself. Good Inflation Doesn't

Zero Hedge -

Bad Inflation Cures Itself. Good Inflation Doesn't

Authored by Lance Roberts via RealInvestmentAdvice.com,

Key Takeaways
  • Inflation driven by supply shocks is "bad" inflation, and bad inflation is self-liquidating because rising income doesn't support it.
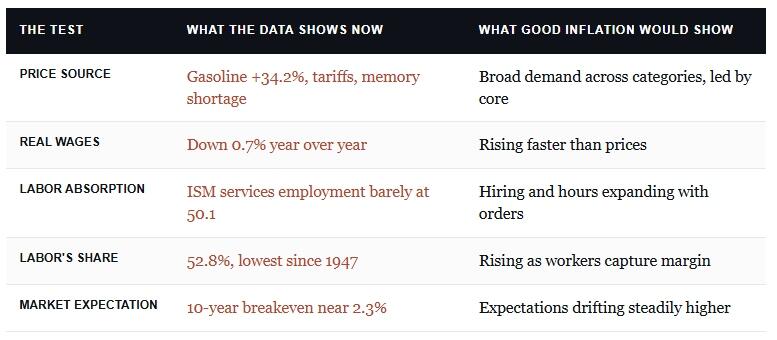
  • September headline CPI ran 3.7% while core sat at 2.6%. The gap is gasoline, up 34.2% over the year and now more than half of the monthly increase.
  • Real wages have turned negative, and labor's share of output just set its lowest reading since the series began in 1947.
  • The 10-year breakeven sits near 2.3%. The market that gets paid to price inflation is not pricing an inflation problem.

Most of the argument about inflation right now is a fight between people using the same word for two completely different things. One side sees a 3.7% headline print and starts sketching a repeat of 1979. The other sees core running more than a point below it and declares the problem solved. Both are reading the same release. The distinction that matters is not how big the number is, but whether anybody's income is financing it. That is the line between "good" inflation and bad inflation, and almost nobody draws it.

Good Inflation, Bad Inflation, And The Difference Nobody Makes

There is a general framework to inflation, and it is older than any of us. Prices can rise because buyers are bidding for scarce goods with money they've actually earned. Or prices can rise because the cost of producing something has jumped for reasons unrelated to demand. An oil embargo will do it, as we saw in the 1970s. So does a shuttered Strait of Hormuz, a new tariff schedule, or a pandemic that takes half the world's shipping capacity offline for eighteen months.

This is an important point for the "debasement" crowd, whose narrative overlooks the underlying fundamentals.

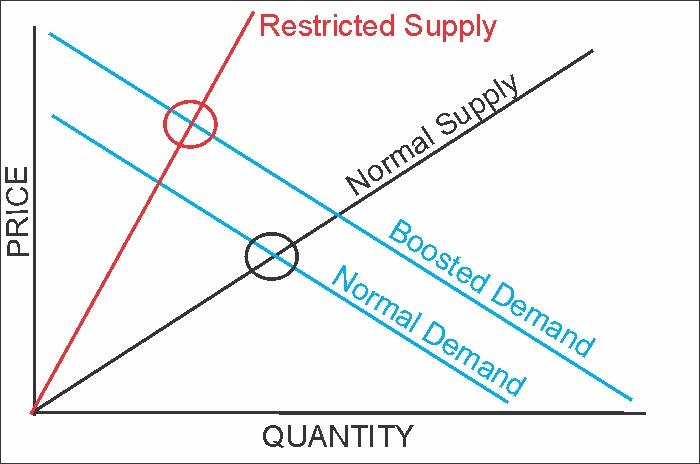
"The following economic illustration is taught in every 'Econ 101' class. Unsurprisingly, inflation is the consequence if supply is restricted and demand increases via monetary interventions."

However, there is a very important distinction to be made about inflation. The first type is the "good" kind of inflation, and it is genuinely good. Demand pushes prices up; firms book wider margins; tight labor markets funnel those margins into paychecks, and the higher paychecks fund the higher prices. The loop closes and becomes self-reinforcing because every leg of it is paid for by real output.

The second kind, the "bad" kind of inflation, closes nothing. A tariff is a tax, just like an oil shock is a tax. Somebody's cost went up, and the money has to come out of a budget that did not grow. Every dollar of that price increase is a dollar not spent somewhere else. Bad inflation doesn't create the income that pays for it, so it destroys the demand that supports it. Such is the mechanism behind the oldest saying in commodities: "high prices cure high prices."

Think of it this way. A group of people drives the same way to work every day. Half get a raise, the other half doesn't. The city decides to put a toll booth on the road they drive to work; each year, that toll rises. Both groups have an increasing number draining their bank accounts each month. However, only one group has sufficient compensation to continue using the toll road. The group without the compensation raise is eventually forced to stop using the toll road; traffic falls, and the operator cuts the toll to win them back.

What The September Print Actually Says

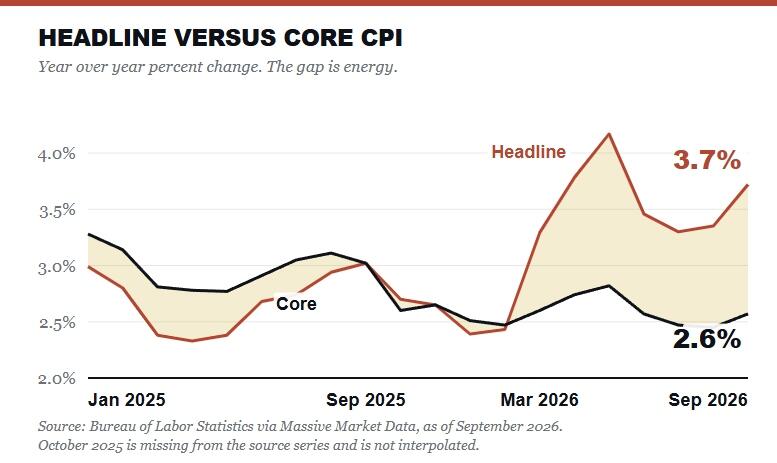
Let's review the recent August data to see what the message, versus the narrative, actually is. The headline CPI came in at 3.7% year over year in September. Core came in at 2.6%, a tick higher than August. Read that pair again, because it is the whole argument. The gap between them widened from nine-tenths of a point to one and a tenth, meaning the headline accelerated roughly three times faster than the core.

That gap suggests a very different narrative than what the media suggests. Gasoline rose 9.1% in the month alone and 34.2% over the year, and the BLS attributes over half the entire monthly increase in the all-items index to that one category. Energy overall is up 20.4%. Meanwhile, core goods, where a genuine demand boom would show up first and loudest, rose 0.7% over twelve months, sitting exactly where it was in August. Shelter ticked up to 3.2%

Now the part I owe you, because I set a test in advance. Core ticked up, shelter ticked up, and services' less energy reached 3.1%, which would eventually prove me wrong. One month of tenths is noise rather than a trend. It is also the first month this year that those three moved the wrong way together, and core goods holding flat at 0.7% is why I am not moving yet, because that is where a demand boom announces itself first, and it has not.

Headline CPI pulled further away from core in September. The shaded area is the spread, and the spread is energy. Source: BLS via Massive Market Data, September 2026.

I've been making this argument since June, when I wrote about why the May 4.2% headline was an oil story rather than a demand story. To wit:

"A 4.2% headline that is three-fifths gasoline is not the same animal as a 4.2% headline driven by wages, rents, and services broadening."

Four months later, the composition has not changed. What has changed is that the evidence against the demand-pull story got considerably stronger.

Labor Just Set A 79-Year Low

The most important evidence comes from the labor market. If this were the "good" kind of inflation, workers would be capturing some of it. They are not.

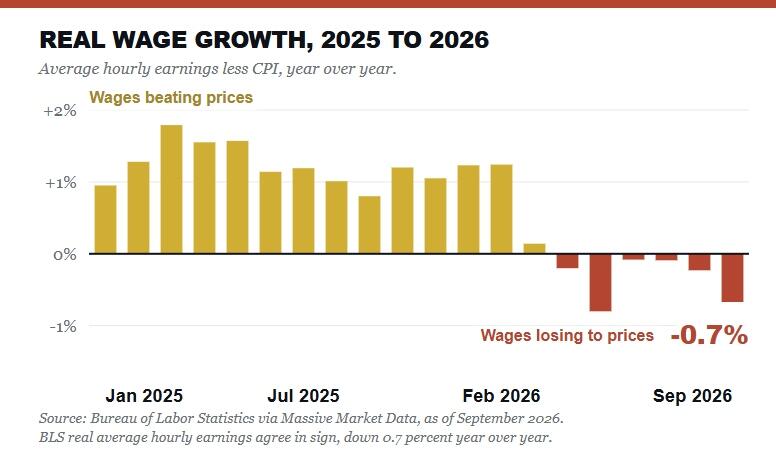
Real average hourly earnings fell 0.7% over the twelve months through September, more than double the August decline. Nominal wages rose 0.1% on the month against a 0.6% CPI print, so purchasing power went backward at the fastest pace of the year. Run the same calculation off average hourly earnings and CPI, and you land in the same place. Real wage growth is near -0.7%, down from over 1.5% as recently as last spring.

In April 2026, real wage growth crossed below zero and hit its weakest reading in September. The gold bars represent the months when wages grew faster than prices. The red bars are months when they didn't. Source: BLS via Massive Market Data, August 2026.

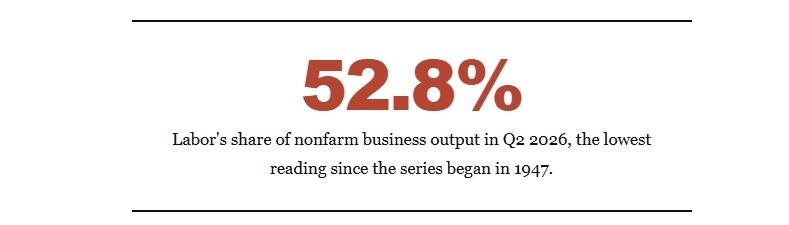
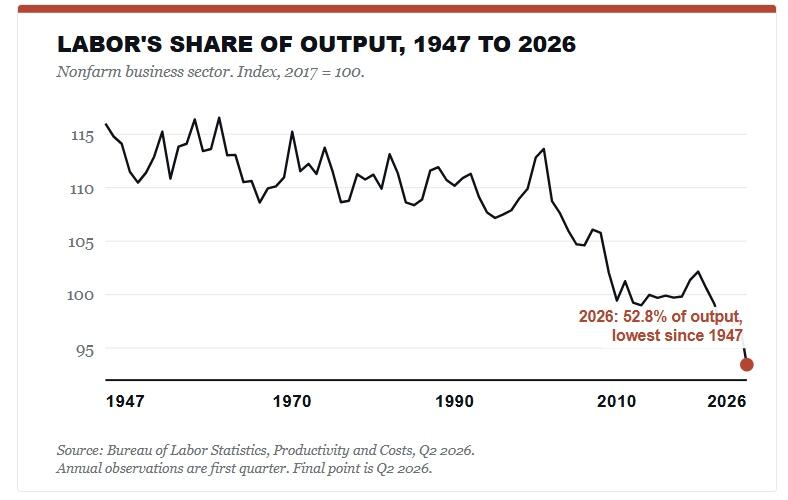
Then there is the one number that everyone simply overlooked. In the second quarter, labor's share of nonfarm business output fell to 52.8%. The Bureau of Labor Statistics flagged that as the lowest level in a series that begins in the first quarter of 1947. Read that again. There have been 79 years of data, 2 dozen business cycles, 4 major wars, the Volcker shock, the China trade shock, and the pandemic. Despite all that, in what is supposed to be an economic boom, we just set a record low.

Labor's share of nonfarm business output in Q2 2026, the lowest reading since the series began in 1947.

Labor's share of output has been falling for a quarter century and just made a series low. Good inflation requires this line to rise. Source: BLS, Productivity and Costs, Q2 2026.

Stop and notice that in the chart above, this is not a 2026 event. The erosion in labor runs back to the early 2000s, long before "artificial intelligence" or "surging debt." The last two years have simply accelerated the numbers. With respect to the inflation question, the timing matters most. A price level that is rising while labor's slice of output hits an all-time low is the textbook signature of cost pass-through rather than demand-pull. In this environment, corporations are fixated on protecting profit margins, while workers are absorbing the difference.

The economic activity surveys tell the same story if you take the time to read past the headlines. The ISM services printed 54.9 in September, with new orders easing to 59.8. That reads like a demand boom until you see prices paid at 74.0, the highest since July 2022, against an employment index that has not managed to exceed 50.1 in three months. Steady orders, hot input costs, flat payrolls. When respondents were asked what was driving those costs, fuel came up about twice as often as anything else.

Where The Inflation Bulls Have A Point

As always, we need to examine both sides of every argument, as the inflation bulls do have a valid point.

The strongest one is the AI buildout. Memory is genuinely scarce; its scarcity is genuinely caused by capital spending, and the producer price index for storage devices has climbed 23% since the end of 2024, while import prices for computers and parts are up 37%. J.P. Morgan's research team puts the memory shock at 0.2% to 0.4% on core inflation. That is capex-driven price pressure; it is real, and it did not come from an embargo. However, that scarcity will eventually reverse. As with oil prices, high prices eventually curtail demand.

The second argument is that tariffs are a policy choice, not a weather event. That is a true statement, and a tariff regime that stays in place for years produces a price level that stays elevated for years. Calling that "transitory" is a semantic trick. I can't argue with that. A permanent tax produces a permanent price. However, the current tariffs were not enacted by Congressional legislation, which would make them more permanent. In this case, they were enacted through executive order, which means the next Administration can repeal them quickly.

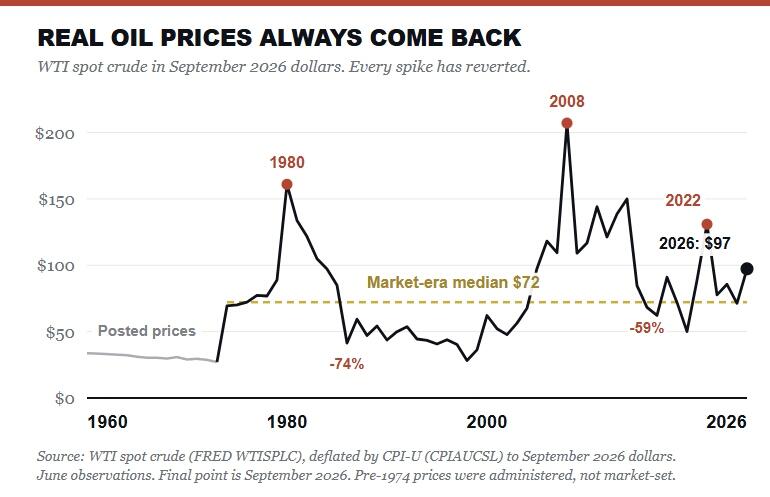
The third is that energy is not reliably mean-reverting on any schedule you can trade. Geopolitics doesn't run on a calendar. However, high oil prices, as shown in the chart below, reliably mean-revert over time.

Those are all sound and valid arguments, but there is a problem with all three, though. Every one of them describes a SUPPLY constraint. A memory shortage is, by definition, a shortage. Call the tariff what it is: a tax. And the Middle East risk is a supply risk. None of them creates the income that pays the higher price. All three fail the same test: gasoline fails, and a more flattering story doesn't change what the bill does to a household budget.

Why Bad Inflation Cures Itself

"Inflation is inflation. My grocery bill doesn't care about the taxonomy."

That is a fair statement. The pain from inflation is the same either way, and when you are staring at the number on the gas pump, the squeeze on household budgets happens regardless. Just because it happens to be the academically preferable kind, the household budget just doesn't care. However, the taxonomy isn't about how it feels, but how it ends, and bad inflation ends in a way the good kind never does.

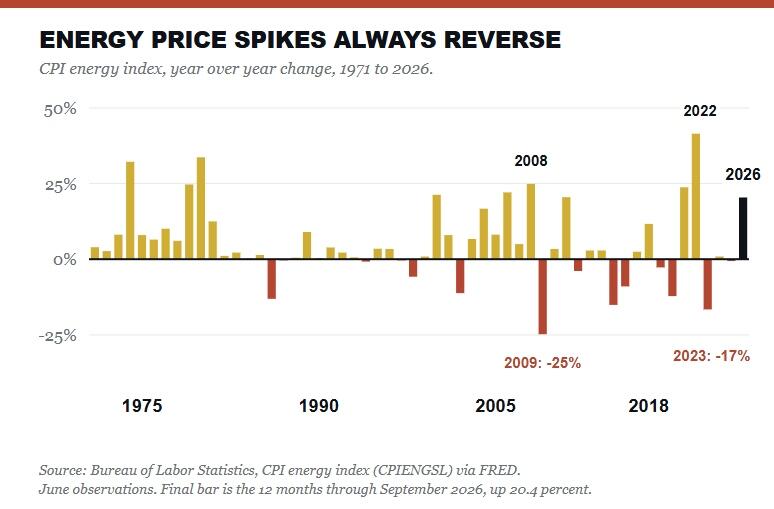
Every major energy spike since 1971 has reversed within one to two years. The 2008 spike gave way to a 25% collapse. The 2022 spike gave way to a 17% collapse. Source: BLS, CPI energy index via FRED, through September 2026.

Notably, look at what happens after every spike on that chart. In June 2008, energy jumped by more than 24%, then subsequently fell by 25% over the following year. In June 2022, energy surged by 41.5%, then only to fall by 16.6% by 2023. Every period from the 1974 and 1980 shocks, the 2000 run, and the 2015 collapse is the same. The pattern repeats itself because it has to, since "demand destruction" is not an economic theory; it's just arithmetic. The current reading of roughly 20% sits well inside the range that has always reverted.

Such is why the bond market refuses to panic. The 10-year breakeven inflation rate is 2.33% as of October 13, and the September monthly average was 2.36%. That number has barely moved all year, holding a range of roughly 2.24% to 2.44% while headline CPI swung from 2.4% up to 4.2% and back to 3.7%. The one market that gets paid to be right about inflation looked at an 180-basis-point headline swing and didn't blink. It then watched September print three-tenths hotter and tick down.

Critically, this is where the case from the "Persistent Purveyors Of Doom" gets confused with itself. Yes, bond yields are elevated, and the bears point at that as vindication for their case. The 10-year sits near 5.1% and the 30-year above 5.55%. But if you decompose it, the rise is due to real yield and the term premium, not inflation expectations, because expectations have been pinned near 2.3% for 18 months. Since early September, the long bond has added about 30 basis points, while the breakeven has given up 3. The bears are right that the long end is repricing. They just have the wrong reason.

Five tests, and five answers pointing in the same direction, which all bring to mind a rule to live by.

"When every strategist on television agrees that inflation is structural and yields only go up, the setup is usually pointed the other way."

What This Means For Portfolios

Will bad inflation cure itself on a schedule you can put in a calendar? No. Demand destruction takes quarters, not weeks, and an energy shock can persist long enough to cause real damage as it resolves. Such is the frustration of running a process that works in quarters for clients who measure in weeks. But will it resolve without the Fed having to break something? On this evidence, probably yes, and that is a very different portfolio than the one the inflation-forever crowd is selling.

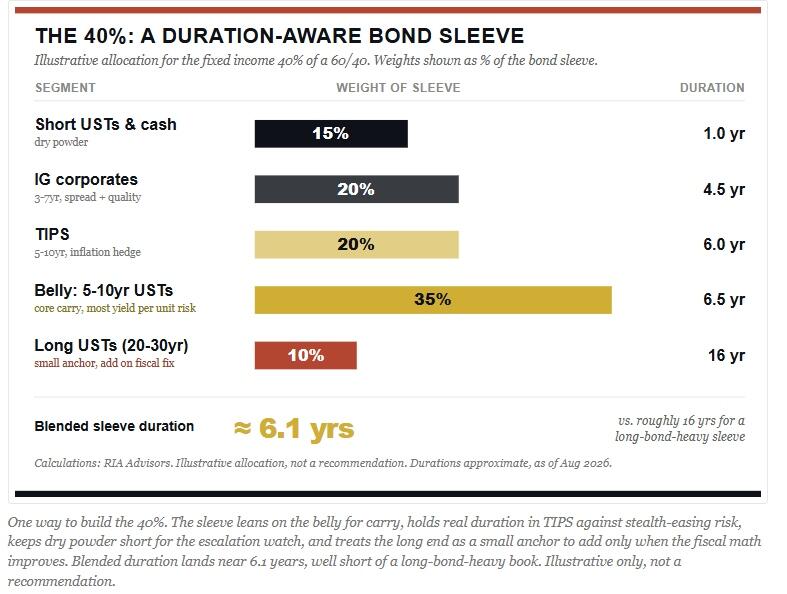
It argues for duration, which is the position I laid out in my discussion about wage growth as a leading inflation indicator. Since then, the real wage data has reinforced that positioning. Investors who bought commodity-linked exposure as an inflation hedge may have the wrong trade. The reason is that commodities would hedge the one kind of inflation that has historically unwound. However, quality equities with pricing power beat the debt-heavy cyclicals that need a nominal boom to work. Most notably, watch the labor data rather than the CPI headline. Labor is where the answer lives.

In the current environment, as laid out in the "Druckenmiller Warning," an effective bond sleeve would look something like this.

Here is what would change my mind, stated plainly so you can hold me to it. If core services excluding shelter reaccelerate, if the Employment Cost Index turns up, if real hourly earnings cross back above zero, and the quits rate rises, then the wage loop is closing, and this inflation became the durable kind while I was arguing it wasn't. Watch those four. I'd rather be corrected by data than by a client's statement.

The thing to fear was never that prices would keep climbing. It's that they'll stop climbing because nobody can afford them anymore, and labor's share of output has been telling us for twenty-five years exactly which of those two we're heading toward.

Tyler Durden Fri, 10/16/2026 - 09:20

Federal Judge Tosses Ex-CIA Chief Brennan's 'Speculative' Lawsuit Against Trump Admin

Zero Hedge -

Federal Judge Tosses Ex-CIA Chief Brennan's 'Speculative' Lawsuit Against Trump Admin

Authored by Debra Heine via American Greatness,

A federal judge on Thursday threw out former CIA Director John Brennan's lawsuit, which sought to compel the Trump administration to preserve records for his defense against potential criminal charges, ruling that he lacked standing.

The Department of Justice is investigating claims that Brennan and other national security officials conspired to undermine President Donald Trump.

The suit, filed in July 2026, sought to compel the Justice Department to retain investigative records so Brennan could prove any indictment against him was the result of vindictive or selective prosecution by the Trump administration.

Judge Jia Cobb, a Clinton-appointed judge, described Brennan's allegations of political targeting as "deeply concerning," but determined the claimed injury was "speculative" and not yet imminent, as no indictment has been filed.

Brennan was President Barack Obama's CIA director from March 2013 to January 2017, and before that, Obama's counterterrorism adviser.

He is facing indictment in at least two investigations: the broader "grand conspiracy" probe into the 2016 election interference inquiry and a separate case regarding alleged false statements made to Congress in 2023.

Prosecutors in the Southern District of Florida are examining allegations that Obama and Biden-era intelligence and law enforcement officials conspired to deprive President Trump of his civil rights through various investigations, from the 2016 Russia probe and the intelligence community assessment to the Mar-a-Lago classified documents case and related matters.

According to the Republican-led House Judiciary Committee, Brennan "made numerous willfully and intentionally false statements of material fact" during his testimony in 2023, including:

  • Falsely denying that the CIA relied on the discredited Steele dossier in drafting the post-2016 election Intelligence Community Assessment; and

  • Falsely testifying when he told the Committee that the CIA opposed including the Steele dossier in the Intelligence Community Assessment (ICA).

  • These statements were contradicted by the record established by the House Permanent Select Committee on Intelligence (HPSCI) and the CIA, the committee stated in a press release in October 2025.

Newly declassified documents show:

  • A CIA officer drafted the annex containing a summary of the dossier;

  • Brennan made the ultimate decision, along with then-FBI Director James Comey, to include information from the dossier in the ICA; and

  • Brennan overruled senior CIA officers who objected to the inclusion of the dossier material.

The former CIA director argued in his lawsuit that because he planned to contest any prosecution that arises from the DOJ's probes as vindictive and selective, internal records and communications would be needed to establish that in court.

Brennan alleged that President Trump had singled him out in retaliation for his role in the Russian collusion hoax.

Cobb appeared to that aspect of Brennan's case seriously, saying that "if he was eventually able to prove those allegations true, that would certainly suggest that his potential prosecution is vindictive."

But at this point, the judge said it remains to be seen that Brennan is facing enough harm to bring the lawsuit.

"Even taking all of Brennan's allegations to be truthful at this stage," the judge wrote, "the injury he alleges is simply too attenuated from the actions he seeks to enjoin to warrant a finding of standing here."

Tyler Durden Fri, 10/16/2026 - 08:35

Futures Rise As Warsh Stays Mum, Tesla "Flying Car" Interrupts AI Liquidation

Zero Hedge -

Futures Rise As Warsh Stays Mum, Tesla "Flying Car" Interrupts AI Liquidation

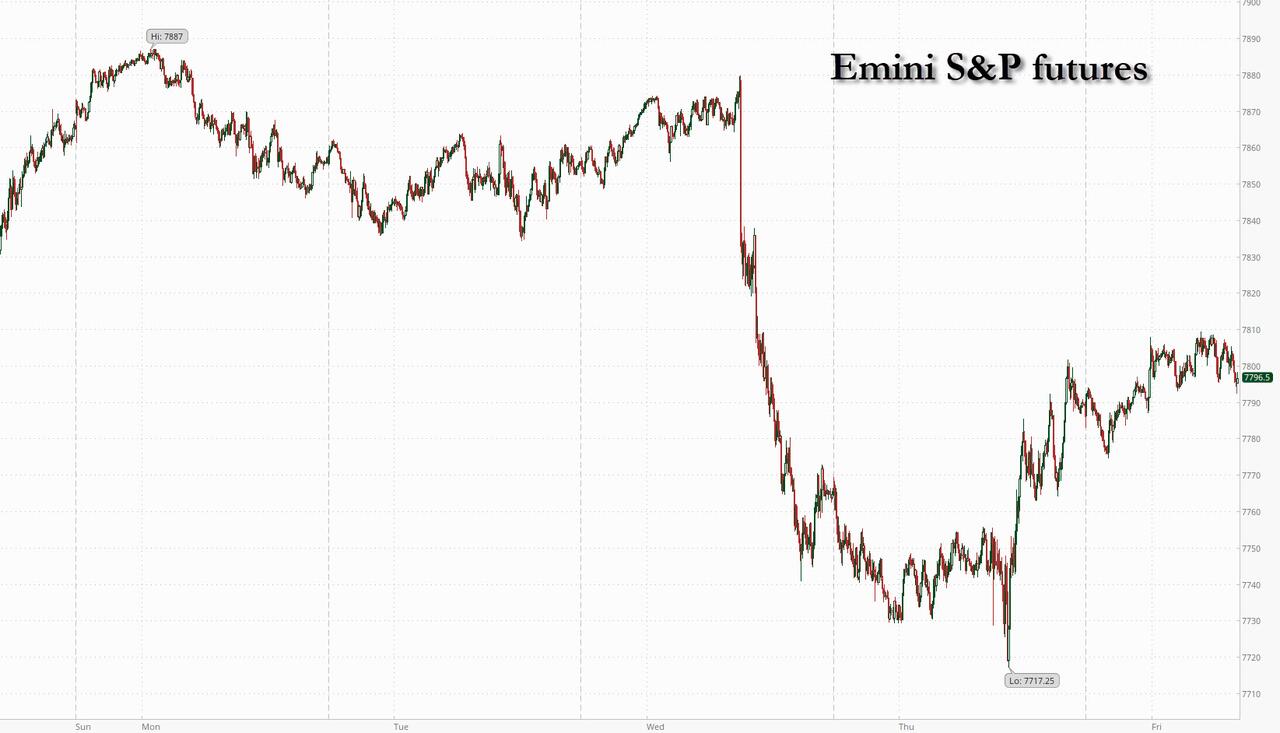
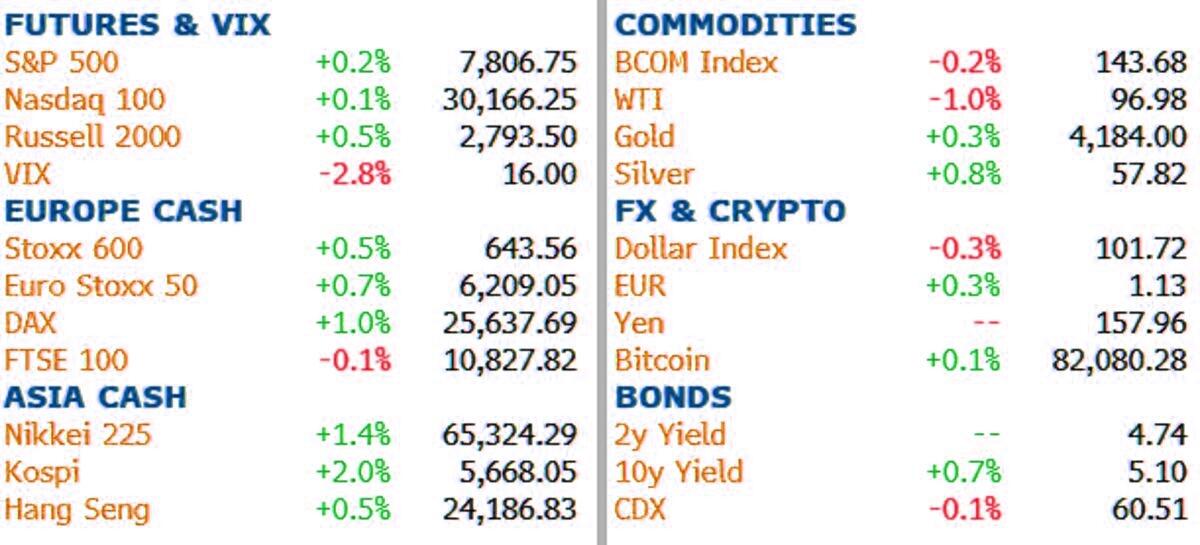
US futures are higher, and small caps are leading, as the crowded-trade unwind that hammered chips, momentum and AI baskets all week takes a breather: Fed Chair Kevin Warsh said nothing about rates at the IMF gathering in Bangkok overnight (traders took the silence as a dovish gift, cutting October hike odds to 14% from 26%), Tesla jumped 5% after Musk unveiled his "flying" Roadster, and oil slipped after Trump said Iran had asked for a halt to US attacks but then it rebounded when the market realized Trump is just lying; as a result haven demand faded and the global bond rally stalled, with 10Y yields rising 6bps to 5.12%. As of 8:00am ET, S&P futures are 0.1% higher at 7,800, Nasdaq futures are down -0.2% and Dow futures are -0.2%; Russell 2000 contracts are up 0.5%. Yesterday the S&P rose 0.3% and closed within 1% of its record high after Jensen Huang rode to CoreWeave's rescue, even as the SOX fell for a 7th straight day and the Nasdaq barely eked out a gain. Premarket, all Mag 7 names except Amazon are higher led by Tesla, while CoreWeave (-3.9%), Strategy (-2.9%) and Netflix (-2.5%) lag and the AI baskets (semis and memory) remain in the red per JPM. The day's driver is Warsh (or rather what he didn't say): with the blackout starting Saturday, the Fed chair declined to push back on rate expectations and instead talked up a "massive investment surge" from AI. In rates, Treasuries slide with a mild bear steepening (2s flat, 10s +4bps, 30s +3bps per JPM) as the rebound in global stocks clips the haven bid; bunds and gilts are also lower by about 15 ticks with UK banks in focus after reports Chancellor Healey will raise their taxes. In FX, the Bloomberg Dollar Spot Index drops 0.4%, down a second day, with the kiwi and Aussie leading G10 and the euro set to end a five-week losing run. In commodities, WTI is down 1% near $97 and Brent trades around $105 but is still headed for a second weekly gain; gold is up 0.3% at $4,184, silver gains 0.8% and copper rises 1% in London. Crypto is mixed: Bitcoin is little changed around $82,000 while Ether bounces. US economic data slate includes September import/export prices (8:30am), industrial production and capacity utilization (9:15am), the federal budget balance (2pm) and August TIC flows (4pm); Fed speaker slate includes Goolsbee on Bloomberg TV at 6pm, the last word before the blackout. There are no coupon auctions, but Treasury's primary dealer questionnaire (noon ET) ahead of the Nov. 4 refunding is worth watching.

In premarket trading, Magnificent Seven stocks are mostly higher: Tesla rises 3.6% after the EV maker unveiled its long-delayed Roadster sports car (Meta Platforms (META) +0.5%, Microsoft (MSFT) +0.5%, Alphabet (GOOGL) +0.3%, Amazon (AMZN) +0.3%, Apple (AAPL) +0.3%, Nvidia (NVDA) -0.1%)

  • Fox Corp. (FOXA) gains 3.9% after BofA upgraded the media company by two notches, to buy from underperform, citing Fox’s deal to buy Roku.
  • Mobileye Global (MBLY) climbs 4% as Citi starts coverage on the maker of software and hardware technology for automobiles with a buy rating, expecting the company to benefit from growth in autonomous driving technology.
  • Semtech Corp. (SMTC) rises 4.4% after Northland Securities upgraded the company to outperform from market perform, a move that comes in the wake of its analyst day event, where it raised its third-quarter forecast.
  • Omeros (OMER) is down 4.1% after the drug developer said an advisory committee of the European Medicines Agency issued a negative opinion on the company’s application for its narsoplimab therapy.
  • Travelers (TRV) drops 4.6% after the insurance company reported net premiums written for the third quarter that met the average analyst estimate. Revenue declined modestly year on year, while catastrophe losses rose.
  • Truist Financial (TFC) falls 2.1% after the financial services company reported third quarter taxable equivalent net interest income that came in just short of expectations.
  • Wise (WSE) falls 2.3% after the payments firm reported cross-border volumes that missed analyst expectations.
    Zeta Global (ZETA) is up 4.6% after Goldman Sachs upgraded the software company to buy from neutral, seeing potential for it to gain market share.

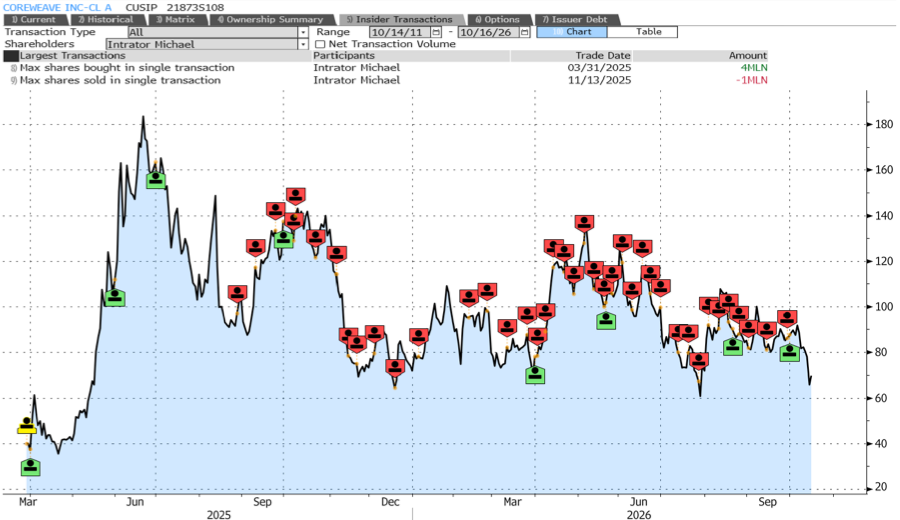
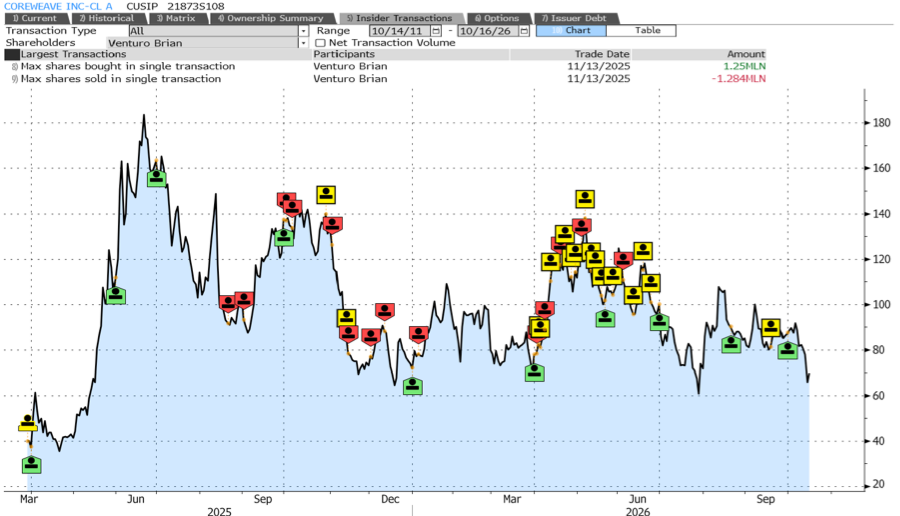
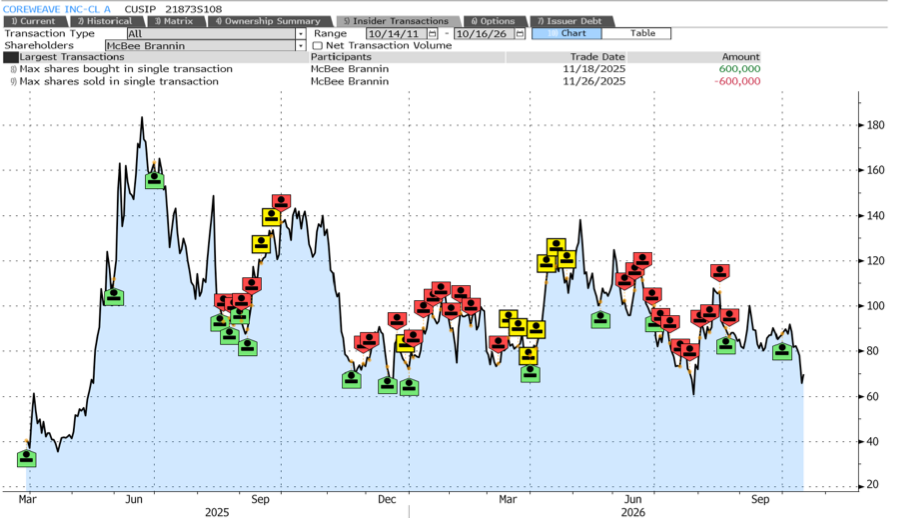
In other corporate news, Tesla unveiled its long-delayed new Roadster sports car (yes, the one that "flies": Newsquawk reports it uses thrusters to land after a ramp jump, does 0-60mph in under a second and enters production in 2028), sending shares of its Chinese suppliers Ningbo Xusheng, Wencan Group and Ningbo Joyson Electronic up 10% each. Thoma Bravo-backed Proofpoint agreed to buy cybersecurity company Varonis Systems for about $6.3 billion, prompting six brokers to cut Varonis to hold-equivalent. Some Anthropic investors discussed a more tempered $1.5 trillion valuation on the back of slowing revenue growth, according to Reuters, confirming our article from yesterday. Netflix is replacing its chief creative officer with veteran TV and film executive Peter Rice, Meta made one of its new AI models available for developers to download and modify, Mercedes-Benz and Nvidia extended their automated driving partnership, and City Therapeutics raised $200 million in a US IPO priced at the mid-point of its range. Meanwhile, three CoreWeave co-founders have sold $3.3 billion in shares since last year's IPO, which may explain why they look so relaxed.

After a brutal few sessions for crowded pockets of the market, including chips, momentum stocks and popular thematic baskets, futures point to a mild recovery in the final trading day of the week, Bloomberg's Before the Bell notes. Europe is on track for its biggest weekly outperformance over the S&P 500 since March as investors rotate out of the AI trade, and Asian stocks rebounded as dip buyers returned to chipmakers after a four-day selloff. The relief comes after quants suffered their worst day since August and hedge funds dumped AI stocks at the second fastest pace in a year.

The overnight catalyst was Warsh, and the most important thing was what he didn't say. With the Fed about to enter its blackout ahead of the Oct 27-28 FOMC, the Chair declined to push back on market pricing despite this week's hot CPI and PPI, saying only that since September "the world has broadly conformed to our expectations." Goldman's economists read this as a signal that the FOMC is set to pause in October, while still expecting a second and final hike in December. That is the punchline even though Bloomberg Economics' Fed Sentiment Index, which tracks the tone of Fed communications, continues to rise and is now at its most hawkish level since 2023 after Daly and Hammack warned about overlapping, long-lived supply shocks.

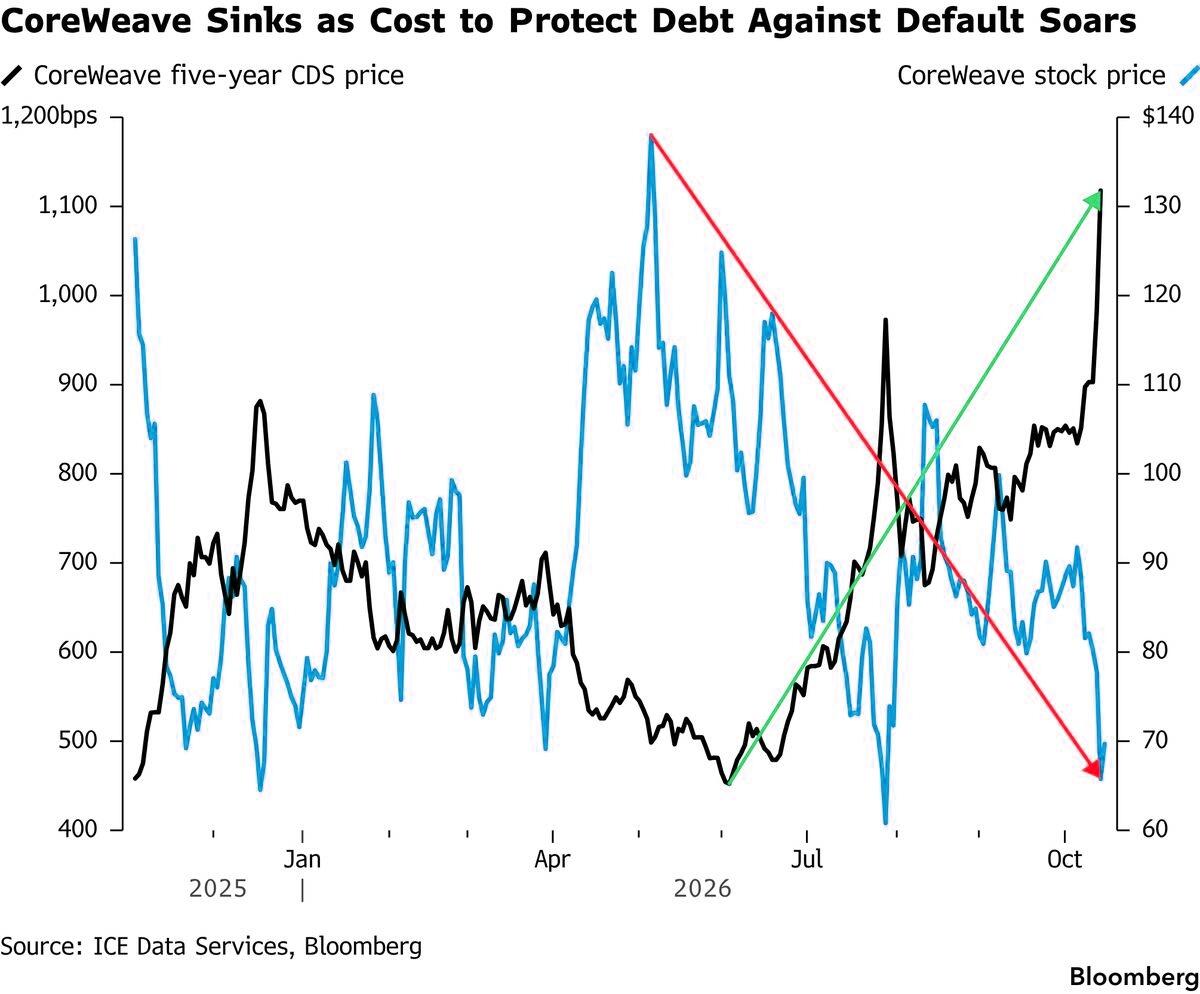
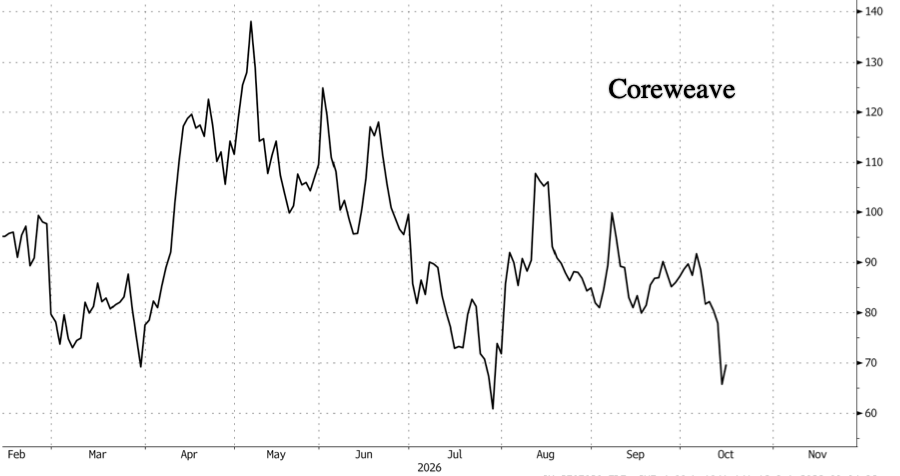
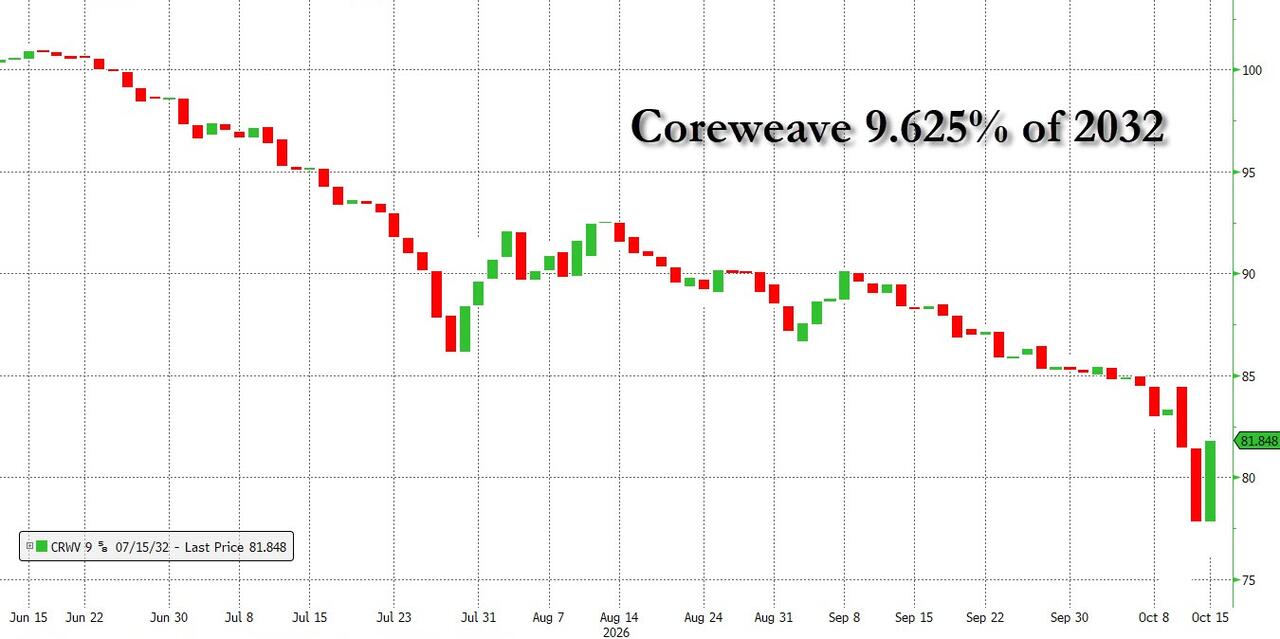
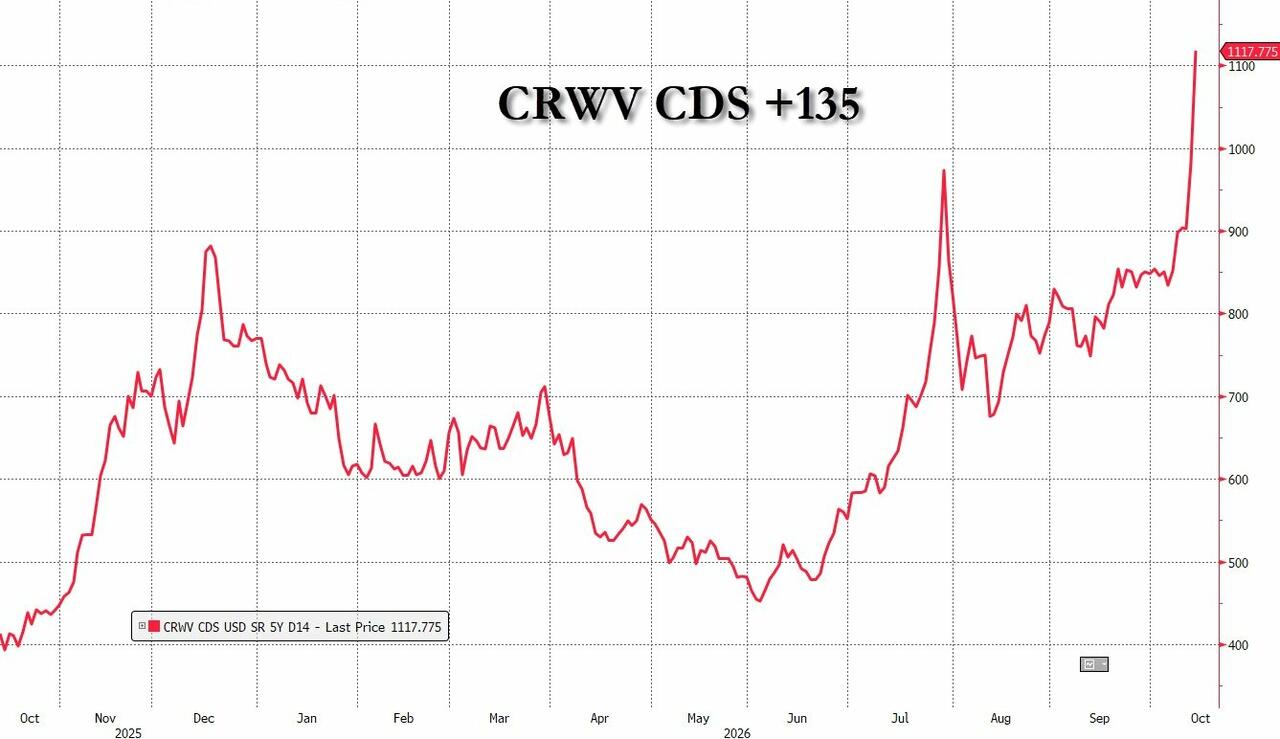
Then there is CoreWeave, which has become ground zero in a tug of war between investors who see rising bond yields as a potential rally killer for the AI trade and those who think compute demand will outweigh such concerns. As DB's Jim Reid recaps, CoreWeave's 5Y CDS initially widened another 76bps to 1194bps, its widest level yet, before ending 30bps tighter at 1086bps once Jensen Huang declared that "CoreWeave's strength is improving every day" (we discussed the credit fallout here and here). The stock is down another 3.9% premarket.

“Today’s rebound is partly a relief rally,” said Billy Leung, an investment strategist at Global X Management. “I’d be cautious about extrapolating today into a straight-line recovery. The fundamental AI/semiconductor story in Asia remains strong, but oil and US yields remain important constraints, so the market probably stays volatile and increasingly earnings-driven.”

The flow data shows a variety of trends: cumulative flows into tech funds are tracking a record year, according to BofA citing EPFR data, and leveraged ETF AUM is off its highs but still elevated, while the long-dated Treasury ETF has seen consecutive $1 billion outflows for the first time ever. And for those worried about narrow leadership, Bloomberg's historical analysis suggests thinner, leader-driven advances have often been followed by gains, particularly over the subsequent six to 12 months.

JPM's Market Intel desk under Andrew Tyler stays Tactically Bullish and sees "stabilization in price action" with RTY leading. The team argues that this week's price action looks more like rotation than broad-based deterioration, flagging the resilience of the equal-weight S&P, and expects the rotation to slow rather than end abruptly; it remains focused on selective dip-buying, likes Financials after generally positive large-cap bank earnings, and says all eyes are on next week's META earnings and Nvidia's GTC event. JPM's ETF desk (Jonathan Rogerson) notes the retail dip-buying impulse is "in full force": SOXL has taken in $3.2 billion over two sessions (16% of AUM created), while heavy supply in Ethereum ETFs carries "a strong scent of profit-taking."

Over at Goldman, Delta One head Rich Privorotsky calls the Asian bounce "a little lackluster relative to the scale of the selloff" and warns that "the problem remains oil, which is stubbornly high." He adds that "rates are finally beginning to reflect the same AI capex growth shock that equities have spent the week repricing." Sean Vogel's flows and positioning note puts it more bluntly: "In hindsight, the pain trade was long AI/ short bonds. Now we're watching both sides unwind." The data back that up: GS Prime's AI long/short ratio has fallen to 3.27 from a 4.34 peak (7th percentile over the past year), and NDX forward P/E is down to about 21x, the lowest since the AI cycle began in 2023. Sam Dunn on the US desk sums it up: "The AI trade is still long but now a 6 out 10 in terms of length and much cleaner than it was in Jun/July."

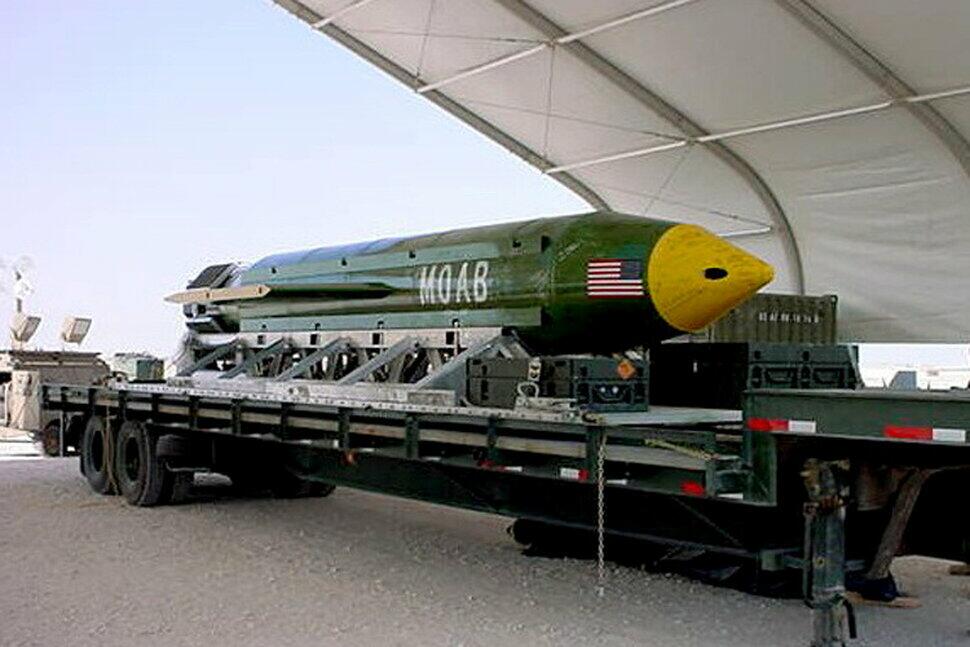
Elsewhere, China proposed adding advanced AI technologies to its export-control list, potentially restricting overseas transfers of AI models and chips, while Taiwan will curb AI chip exports to China as part of its US trade deal, and Beijing moved to prop up its own stock market by urging companies and state funds to buy shares while guiding some investors to curb selling. In the Gulf, CENTCOM confirmed that a container ship that sank in the Strait of Hormuz this week was struck by an Iranian projectile, Iran's navy said a "violating" tanker caught fire in a restricted zone east of Hormuz, and Trump declined to rule out using the "Mother of all Bombs" on Iran after the midterms, even as he said Tehran had asked for a halt to US attacks.

In Europe, the Stoxx 600 rises 0.6% to 643.72 with 471 members up and 122 down, heading for a third day of gains; media and autos are the best performing sectors while health care is the only one in the red. The DAX leads with a 0.9% gain and cyclicals do the heavy lifting, while the FTSE 100 lags as UK banks slide after Bloomberg reported Chancellor Healey will raise taxes on banks (the Guardian says via a 3% increase to the bank surcharge): Lloyds is down 2.3% (also cut at RBC) and NatWest 2.1%, while HSBC and Barclays are little moved. JPM's desk says Defense, Renewables, Software and Momentum Short are among the best performing baskets. Here are the biggest European movers:

  • Nestle shares rise as much as 1.5% after JPMorgan upgrades the stock to overweight, saying FY27 could be a “vintage year” for the consumer goods company.
  • Aixtron shares rise as much as 10% after the chip-equipment maker reported preliminary orders well above analyst expectations.
  • Nordex shares rise as much as 15% after the wind turbine manufacturer posted third-quarter earnings that smashed expectations and raised its margin goal for the full year.
  • Verbio shares rise as much as 11% as Jefferies upgrades the German biofuels manufacturer to buy from hold, saying the company is increasingly attractive now that its investment phase is largely behind it.
  • Brunello Cucinelli shares rose as much as 6.2% after the Italian luxury firm reported third-quarter earnings that beat expectations and raised its growth guidance for the year.
  • Man Group shares gain as much as 3.3% after the UK investment firm reported stronger-than-expected inflows for the third quarter, with growth across both alternative and long-only strategies.
  • Avanza shares declined 5.3% after the lender reported operating income for the third quarter that missed the average analyst estimate.
  • Wise shares drop as much as 2.7% after the payments firm reported cross-border volumes that missed analyst expectations.
  • Lloyds Banking Group shares fall as much as 2.7% after RBC Capital Markets downgraded the UK lender to sector-perform from outperform, noting that competition in the regional deposit market threatens to erode the benefits of its structural hedge.

Asian stocks rebounded, led by chipmakers after a four-day selloff on concerns over the AI boom, with the MSCI Asia Pacific Index jumping as much as 1.8% (Samsung, SK Hynix, BHP and Alibaba the biggest contributors), though the gauge was still on track for its worst weekly loss in more than three months. Japan's Topix and Nikkei both rose 1.9%, the Hang Seng gained 1.2% and the CSI 300 0.8% as state-backed buying returned with a record 18.8 billion yuan inflow into the E Fund CSI 300 ETF on Thursday, Taiwan's Taiex added 0.7% and the ASX 200 1.1%. Korea's Kospi, which tumbled nearly 8% on Thursday, climbed as much as ~4% and closed 2% higher at 5,668. TSMC slipped despite better-than-expected results and a strong outlook, a sign that tech sentiment remains fragile. The outlier was Indonesia, where the JCI plunged 11%, the most since January 1998, after MSCI proposed reclassifying the country from emerging-market to standalone-market status; Goldman's GIR estimates outflows of $5.0 billion to $7.8 billion depending on the scenario, and IndoGBs sold off 30bps. Goldman's Asia desk (Enna Hattori) dubbed it a "soft bounce", with flows finishing only 1.2x better to sell, and cautioned that the market "will require some fundamental reassurance before being able to regain MTD losses."

In FX, the Bloomberg Dollar Spot Index is down 0.4%, falling a second day, as traders pare bets on an October Fed hike after Warsh steered clear of any policy signals. Risk-sensitive currencies lead G10, with NZD/USD up 0.9% and AUD/USD up 0.6%; the euro rises 0.2% to around 1.1245 and is set to end a five-week losing run (ING's Francesco Pesole sees it largely confined to a 1.10-1.15 range in the coming months), and the pound hit a three-week high of 1.3337 despite the bank tax story. The yen is flat around 157.9 per dollar. In EM, Bank Indonesia intervened to support the rupiah as the MSCI shock fuels bets on a rate hike, a few days after Asian central banks dumped dollars to defend their tech currencies.

In rates, Treasuries slide, led by the long end, as the rebound in global stocks reduces the appeal of haven assets and Warsh's comments did little to alter the rate outlook; 10-year yields are up 5bps at 5.11%, with 2s little changed and the curve bear steepening, unwinding part of Thursday's 12.7bp bull flattening rally which came in spite of a PPI print that was the hottest since March 2022 (because when AI capex gets wobbly, inflation apparently stops mattering). Money markets now price a 14% chance of an October hike, down from 26% earlier. European bonds are also weaker, with bunds and gilts down about 15 ticks; gilt traders are looking for clues on how Chancellor Healey will balance spending and revenue ahead of the Oct. 28 Budget, with a bank tax the latest idea. There are no coupon auctions today, but at noon ET Treasury releases its primary dealer questionnaire ahead of the Nov. 4 refunding, and some on the Street expect 20Y and 30Y auction sizes to be cut by $3 billion each (with speculation the 20Y could be cut altogether).

The short-lived nature of the Treasury rally suggests that the safe-haven status of US bonds is continuing to wane, said Steven Barrow, head of G10 strategy at Standard Bank.

In commodities, crude is on the back foot, with WTI Dec'26 down 1.2% near the bottom of a $95.29-96.39 range and Brent Dec'26 down 0.8% within $104.91-105.94, after Trump said Iran had asked for a halt to US attacks and that negotiations are ongoing; the IEA also said member countries agreed to complete the release of 100 million barrels still outstanding from the March intervention. Even so, oil is set for a second weekly advance as mounting Middle East supply risks outweigh the reserve release: Iran's navy said a "violating" tanker caught fire east of Hormuz, Saudi Arabia and the Houthis continue to trade strikes, and Ukraine has resumed attacks on Russian refineries. Spot gold trades in a $4,147-4,189 range and eyes its 21-DMA near $4,200, silver is up 0.8% at $57.82, and LME copper gains 1% toward $14,500/t as sentiment improves.

US economic data slate includes September import/export prices (8:30am), industrial production and capacity utilization (9:15am), the federal budget balance (2pm) and August TIC flows (4pm). Fed speaker slate includes Goolsbee on Bloomberg TV (6pm) ahead of the communications blackout that begins Saturday. Travelers, Truist, M&T Bank, Citizens Financial and Regions report before the open.

Market Snapshot

Top Overnight News

  • Federal Reserve chair Kevin Warsh has signaled that hotter-than-anticipated inflation has not swayed his views on the US economy, prompting traders to further scale back bets on a rate rise this month. FT
  • Goldman economists say Warsh’s comments indicate the FOMC is set to pause in October; they continue to expect a second and final hike in December. GIR
  • President Donald Trump said he would not use nuclear weapons against Iran, telling Newsmax that the U.S. “doesn’t have to.” Trump also said he did not foresee sending U.S. ground troops into Iran. CNBC
  • Iran’s Navy identified a “violating” oil tanker “a few hours ago” that caught fire in a restricted zone east of the Strait of Hormuz, state-run IRIB News reports; the tanker had turned off its tracking systems. BBG
  • US Central Command confirmed that a container ship that sank in the Strait of Hormuz this week was struck by an Iranian projectile; Trump declined to rule out using the “Mother of all Bombs” on Iran after the midterms. BBG
  • The US is considering moves to ease restrictions on “shadow fleet” tankers linked to Russia and Iran as it struggles to bring down soaring diesel prices ahead of November’s midterm elections. FT
  • The International Energy Agency said member countries agreed to complete the release of 100 million barrels of oil still outstanding from an intervention in March. BBG
  • China moved to stabilize its equity market by urging companies and state funds to buy shares while guiding some investors to curb selling, people familiar with the matter said. Financial regulators held a meeting Thursday to discuss stabilization measures for the stock market. BBG
  • Taiwan is preparing to tighten export controls on AI chips to further align with US restrictions, according to a senior official in Taipei, joining a Trump administration clampdown on the smuggling of cutting-edge semiconductors to China. BBG
  • China proposed adding advanced AI technologies to its export-control list, potentially restricting overseas transfers of AI models and chips. BBG
  • Indonesian stocks suffered their worst rout in nearly three decades after MSCI warned the country’s emerging-market status is at risk, stoking fears of removal from global indexes and foreign capital flight. BBG
  • Ukraine's resumption of strikes on Russian refineries is a 'disgrace' that keeps global energy prices elevated, US President Donald Trump said. Ukraine struck a Russian oil refinery after President Volodymyr Zelenskiy declared that Kyiv was abandoning a ceasefire covering energy sites that Trump had announced, and criticized his willingness to strike deals with Moscow. RTRS
  • Progress toward a U.S.-Mexico tariff deal has stalled after opposition from Commerce Secretary Howard Lutnick, people familiar with the talks said, the second time that he has had a hand in upending advanced negotiations with a North American partner. WSJ
  • PM Mark Carney urged Albertans to reject separatism in an Oct. 19 referendum, calling national unity critical. The province will vote on whether to remain in Canada or start a process that may lead to secession, subject to a second ballot. BBG
  • UK Chancellor Healey will raise taxes on banks, likely by increasing the bank surcharge; UK lenders fell in early trading. BBG
  • Three CoreWeave co-founders have sold $3.3 billion in company shares since last year’s IPO. BBG
  • Some Anthropic investors discussed a more tempered $1.5 trillion valuation on the back of slowing revenue growth. RTRS via BBG
  • JPM Econ (Abiel Reinhart) keeps its September core PCE forecast at 0.31% m/m (3.1% y/y) after PPI; GS raised its estimate to 0.34%. JPM/GIR
  • US President Trump is to deliver remarks in Dalton, Georgia at 14:45 EDT/19:45BST on Friday.
  • US President Trump said no real reason for him to go to Maine and thinks he will go to Minnesota, while he said he is not involved in that when asked regarding probe into Democrat Rep. Omar.
  • Japan is to sidestep 3.5% defence spending target despite US pressure: Asahi
  • US President Trump said he will be going to Iowa state on Thursday, October 22nd and Sunday, November 1st.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly higher as global markets regained composure following the recent tech bloodbath. Elsewhere, Indonesian stocks are the outlier with double-digit percentage losses as the MSCI consults on a proposal to reclassify Indonesia from Emerging Market to a Standalone Market Status. ASX 200 gained with the upside led by tech and miners, while recent weak jobs data also supported the case for a pause from the RBA at the next meeting. Nikkei 225 recouped some of the losses from the prior day's turmoil. KOSPI outperformed but still has far to go after falling by as much as 8% yesterday. Hang Seng and Shanghai Comp conformed to the broad recovery in risk assets, while PBoC Governor Pan also recently reiterated that China would maintain a moderately loose monetary policy.

Top Asian News

  • South Korean Finance Minister and Central Bank Governor held a meeting with the Fed and US Treasury Department.
  • China is reportedly moving to lift the stock market with selling curbs and buybacks, Bloomberg reported.
  • Japan's Finance Minister Katayama said can't comment whether we would need extra budget or not, adds even if needed, the extra budget would be limited to urgent policy priorities.

European bourses (STOXX 600 +0.5%) have an upward bias to start the final trading session of the week, with cyclical-heavy indices outperforming as tech rebounds from this week's losses. Sectors highlight the positive bias. Autos lead, with Media and Telecoms following closely behind. To the downside resides Health Care, as the only sector in the red. UK banks are under pressure this morning after Bloomberg reported that UK Chancellor Healey will raise taxes on banks. The report follows a Guardian source stating that the proposal includes a 3% increase to the bank surcharge. Lloyds (-2.3%) and NatWest (-2.1%) are under the most pressure, while Barclays (-0.2%) and HSBC (+0.5%) are little moved given its large international business. US equity futures follow their European peers. Tesla (+5%) is getting a boost pre-market as it unveils its flying car, while Strategy (-2.4%) falls after MSCI announces new screening methodology that targets companies holding digital assets. Tesla (TSLA) Roadster uses thrusters to land after ramp jump, while Roadster can accelerate 0-60Mph in less than 1 second, while it will enter production in 2028.

Top European News

  • UK Ofcom proposes to cap Second Class stamp price for a further year, until March 2028.
  • Chinese Finance Minister met with the EU Economy Commissioner Dombrovskis, ECB President Lagarde and Eurogroup President Pierrakakis. Chinese side is willing to give full play to the role of China-EU financial dialogue and other mechanisms with the EU side.
  • Germany's Finance Minister said he is not against China, China is an important partner, but is not playing by the rules and we should not be naive.
  • Rio Tinto (RIO LN) CEO said that they are looking to build commodity trading capabilities.

FX

  • Snapshot: G10s are firmer against the broadly lower USD this morning. Antipodeans lead, benefiting from the risk tone, whilst the JPY holds towards the bottom of the pile, but still remains flat.
  • USD continues the prior day’s downside, which stemmed from AI-debt concerns and lower yields. Also fuelling the downside this morning is a speech from Fed Chair Warsh, where he ultimately provided no forward guidance ahead of the October meeting; as such, money markets pared back their bets of an October hike (now 14% vs 26% earlier). The docket for the remainder of the day remains exceptionally light aside from US Import/Export Prices and Industrial Production.
  • GBP is a touch firmer this morning, benefiting from the softer USD a little more-so than peers. Focus remains on the looming UK Budget (Oct 28), where source reports have generally been welcomed by markets. The latest was via Bloomberg, which suggested that Chancellor Healey could raise taxes on banks. The source adds that the move will likely involve increasing the bank surcharge that it added on top of the standard corporation tax rate. It seems as if markets are taking the potential tax on banks as a reliable way to improve the fiscal situation, without having a significant impact on growth.

Central Banks

  • Fed Chair Warsh said he may be over-scarred from the Global Financial Crisis, adds since September FOMC, world has broadly conformed to our expectations. Will be crystallising what is happening to output, employment and inflation. We will be meeting a couple more times this year, which will be the crystallising moment. Right now, we have structural growth and an investment surge. Obviously, the Fed's policies spill over to the rest of the world, but their policies spill back to the US too. Will make judgements at the October and December meetings. At the Fed, we made clear that we would deliver price stability; I do not believe in prejudging meetings. Do not prejudge meetings. Do not believe in signalling what I might do at meetings for the rest of 2026. AI is going to hit the demand side of the economy before the supply shock. AI will help central banks have confidence in data and monetary policy. AI will change the real economy, but near-term impact on employment is uncertain. AI will make economy more productive, more wealth, but path to them will be a bumpy one.
  • Fed's Goolsbee (2027 voter) said it's a discouraging month regarding inflation and still feel some optimism if drivers of inflation can go away in short order, if inflation is from overheating demand from AI, that's more disturbing and have to address it.
  • Fed's Hammack (2026 voter) said hearing more from lower-income Americans struggling with inflation, adds anecdotal information provides important economic guidance. Businesses are seeing a lot of input cost price pressures. Worries about formation of inflation mentality. Formation of inflationary mindset might force more aggressive Fed policy action. Hard to know what a neutral rate is. Financial conditions do not appear restrictive right now.
  • BoJ Governor Ueda said underlying inflation is approaching 2% and the BoJ will continue to raise policy rate in accordance with economic, price and financial developments. There is a risk of underlying inflation overshooting 2% price target.
  • ECB's Wunsch said further tightening would be reasonable given persistent inflation pressures and the resilient EZ economy. Inflation is running at almost 4%, domestic inflation stands at 3% and energy prices are likely to remain elevated for longer than previously expected. Not committing to anything due to the high degree of uncertainty. Market pricing of three rate hikes seems reasonable.
  • ECB's Nagel said Germany is getting fit for the challenges of the future and a fitness program of reforms is always important. Regarding bond market, Germany will remain the anchor of stability in Europe.
  • ECB's Rehn said growth outlook is better today than start of the year, adds not seeing second-round effects on inflation. Labour market not as tight, wage moderation ongoing. Must show vigilance on inflation outlook.
  • BoE Governor Bailey said it's too early to form strong views on strength of second round effects. So far signs of second round effects are subdued and businesses emphasizing cost cutting. UK economy is more resilient than we expected and not as strong as we need. News from Middle East is the biggest factor moving UK gilt yields. Second-round inflation pressures look subdued so far. More hopeful than a month ago that they will get more international alignment on AI testing.
  • RBNZ Chief Economist Conway said there is reasonable confidence that inflation has not become broad-based and that rate hikes help contain spillovers from an energy shock.
  • PBOC's Pan said that the PBOC is to support offshore CNY markets development; to further expand liquidity management tools.
  • PBoC injected CNY 60bln via 7-day reverse repos with rate kept at 1.40%.
  • PBoC set USD/CNY mid-point at 6.7220 vs exp. 6.6947 (prev. 6.7253).
  • Bank of Canada Governor Macklem said Canada hasn't raised rates yet, but the longer it goes, the harder it is to look through increases in energy prices.

Fixed Income

  • Fixed income benchmarks are a touch lower to start the final trading session of the week. USTs essentially flat, and look set to end with weekly gains despite a hotter CPI and PPI print this week, as Fed Chair Warsh fails to provide little guidance. As such, money markets pared back their bets of an October hike (now 14% vs 26% earlier).
  • Focus will be on the US Treasury primary dealer questionnaire, expected at 17:00BST/12:00EDT, ahead of the QRA on November 4th. Some analysts expect the Treasury to cut both 20-year and 30-year auction sizes by USD 3bln each, and to be replaced by T-bills. To add, there has also been speculation that the 20-year could be cut altogether.
  • Gilts and Bunds trade in tandem, posting losses of around 15 ticks.
  • Focus for Gilts this morning, and heading into the Budget, is on any clues to how Chancellor Healey chooses to balance spending with income. The latest being focused on the banking sector, with Bloomberg reporting that UK Chancellor Healey will raise taxes on banks. The report follows a Guardian source stating that the proposal includes a 3% increase to the bank surcharge.
  • Australia sold AUD 1bln in 3.25% April 2029 bonds, average yield is 4.8238%, bid to cover of 4.89.

Commodities

  • Crude benchmarks are on the backfoot, with mild underperformance in the WTI Dec’26 (-1.2%) vs Brent Dec’26 (-0.8%). The former currently holds towards the bottom end of a USD 95.29-96.39/bbl range, whilst the latter sits within a USD 104.91-105.94/bbl range. The mild underperformance seen in WTI is likely a bit of an unwind following yesterday’s relative outperformance, on the back of large weekly US headline inventory and as the US Treasury extended a sanctions waiver allowing Lukoil petrol stations to operate within the US.
  • The geopolitical environment remains tense on three major fronts: 1) The US-Iran situation remains unresolved, though President Trump did mention that Iran requested a halt to attacks and that negotiations are ongoing. A factor which is likely weighing on the complex this morning. 2) Saudi Arabia and the Houthis continue to strike each other, and 3) Russia and Ukraine have continued to strike energy facilities, despite Trump’s announcement of an energy ceasefire.
  • Spot gold currently trades within a USD 4,147-4,189/oz range, continuing to build on the prior day’s gains; the yellow metal now eyes its 21-DMA at USD 4.2k/oz. Strength today is facilitated by a slightly softer USD, which comes after Fed Chair Warsh avoided any guidance surrounding the October confab, which saw a slight paring of tightening bets.
  • Base metals are rebounding from recent losses as global sentiment improves. 3M LME Copper (+1%) currently trades at the upper end of a USD 14,296-14,482/t range, and now eyes USD 14.5k/t.
  • South Korea is reportedly to extend oil fuel price cap for another four weeks.
  • Russia and Iran is reportedly discussing gas pipeline route and pricing, TASS reported.
  • Japanese Chief Cabinet Secretary Kihara said Japan expects October crude procurement to be at the same level as last year.
  • China set 2027 corn import tariff quota at 7.2 mln tons and wheat import tariff quota at 9.64 mln tons.

Trade/Tariffs

  • China's MOFCOM is to revise the "Catalogue of Technologies Prohibited and Restricted from Export in China," and temporary registration management will be implemented for the export of related technologies.
  • Taiwan is to curb AI chip exports to China as part of the US trade deal, Bloomberg reported. Servers and high-end chips will be added to the controlled items list.
  • France is said to have agreed to support UK inclusion in the bloc's proposed "Made in Europe" legislation, although Britain would need to align with the EU's approach to tariffs on Chinese EVs.
  • Japan is to open anti-dumping probe on Chinese pigments and preparations made from Chinese rutile titanium dioxide.
  • US Commerce Secretary Lutnick throws future of US-Mexico trade talks into further doubt as he has objected to significant reductions in tariffs on Mexican steel, aluminum and automobiles, according to WSJ.

Geopolitics: Iran

  • US President Trump said wouldn't use nuclear on Iran, while he is talking to Russia and China regarding denuclearisation, adds may have to go to Pickaxe Mountain and don't see troops on the ground in Iran. Iran has asked for a halt to US attacks and negotiations are still ongoing.
  • IRGC Brigadier General Akraminia said "we have introduced new equipment into our combat formations", Al Mayadeen reported.
  • IRGC Brigadier General Akraminia announces new operational plans to push back more American ships and flee ever further; reiterates that the Army Navy has complete operational control over the Sea of Oman, SNN reported.
  • Iranian Army Commander Major General Amir Hatami said three ships entered the Sea of Oman and were fired upon by Iranian forces, severely restricting maritime traffic.
  • Iranian Ambassador said that "The United States is not demonstrating serious political will to negotiate with Iran", Tass reported. Iranian Ambassador to Moscow's Kazem Jalali.
  • US President Trump answered he doesn't trust anyone when was asked if he trusts Israeli PM Netanyahu.

Geopolitics: Ukraine

  • US President Trump said Ukrainian President Zelensky is not a good guy to deal with, adds Zelensky is more difficult than Putin to deal with. He is allowed to do a self-pardon. Plenty of other targets besides refineries to hit. Need an election in Ukraine.
  • US President Trump said Ukraine's resumption of strikes on Russian refineries is a disgrace.
  • EU President of the European Commission Von Der Leyen said that they are working on the 22nd package of sanctions against Russia, adding that no sanctions will be lifted unless Russia stops its war.
  • Russian forces struck a vessel sailing to Ukraine's Odessa, according to IFX.
  • Temporary restrictions introduced at Pulkovo Airport in St. Petersburg, Russia, according to TASS.
  • Ukrainian drones are attacking Russia's Moscow region and reportedly hitting industrial warehouse facilities.
  • Massive fire breaks out in Ukraine's Khmelnitsky region following a reported strike on a fuel depot.
  • US senators are demanding an investigation into disruption of a satellite system supporting Ukraine, according to an Al Jazeera correspondent.
  • Order to limit Ukraine's access to Starshield system came from inside the White House, according to sources.
  • Ukraine's Air Force said jet drones spotted over Kirovohrad region heading west.
  • Russian local governor said drones hit industrial facilities in Russia's Rostov region.
  • Russian President Putin said Ukraine failed to grasp consequences of returning to targeting refineries.

Geopolitics: Middle East

  • Saudi army conducted missile attack on areas of Amran and Saada provinces in northern Yemen, according to IRNA.
  • Yemen Houthi official said Saudi Arabia must answer for the massacre of civilians in Yemen and called for independent international probe into the Saudi war on Yemen.
  • Saudi-led coalition noted there 20 Houthi attacks on Riyadh in October and that recent strikes included an attack on King Khalid International Airport that killed 12 on October 10th.
  • Explosions reported in the city of Dammam, Saudi Arabia, SNN reported.
  • Yemeni armed forces strike military positions in Aden, hitting military operation headquarters managed by Saudi officers which killed four.
  • Saudi-led coalition said it intercepted and destroyed a drone launched towards Saudi Arabia's Eastern Region.

Geopolitics: Other

  • Chinese Foreign Minister told Israel's President promoting peace and reconciliation in the region is the cornerstone of China's Middle East policy, and China consistently held that the Palestinian question is greatest historical injustice of this century. Immediate priority is to fully open access to the Gaza Strip. Israel should stop and reverse its forced establishment of settlements in the West Bank.
  • South Korea asks the US for a tax break for Alaska LNG project, according to Maeil.
  • South Korea-US ties are said to be straining over intelligence sharing restrictions, trade disputes, and reduced military cooperation, raising concerns about Seoul's ability to counter North Korea's nuclear threat. South Korean President Lee Jae-myung is seeking to rebuild trust with Washington while improving ties with Beijing as trade tensions and potential Trump-Kim talks add uncertainty.
  • US Secretary of State Rubio spoke with Israeli PM Netanyahu and spoke with Lebanon's President Aoun regarding recent developments including the seizure of a truck carrying Hezbollah explosives. Rubio also urged direct military-to-military communication between Lebanese and Israeli forces for deconfliction.

Crypto

  • Bitcoin (+1%) and Ethereum (+3%) attempts to rebound from recent losses as the risk tone improves.

US Event Calendar

  • 8:30 am: Sep Import Price Index MoM, est. 1.0%, prior 0.7%
  • 8:30 am: Sep Import Price Index YoY, est. 8.2%, prior 7.0%
  • 8:30 am: Sep Export Price Index MoM, est. 0.9%, prior 0.6%
  • 8:30 am: Oct NY Fed Services Business Activity
  • 9:15 am: Sep Industrial Production MoM, est. 0.4%, prior 0%
  • 9:15 am: Sep Capacity Utilization, est. 76.5%, prior 76.3%
  • 12:00 pm: Treasury primary dealer questionnaire (ahead of Nov. 4 QRA)
  • 2:00 pm: Sep Federal Budget Balance, est. -$30b, prior $197.94b
  • 4:00 pm: Aug Total Net TIC Flows, prior $83.7b
  • 4:00 pm: Aug Net Long-term TIC Flows, prior -$27.9b

Central Bank Speakers

  • 6:00 pm: Fed's Goolsbee Speaks on Bloomberg TV

DB's Jim Reid concludes the overnight wrap

It's been yet another fascinating 24 hours with CoreWeave 5yr CDS initially widening another 76bps intraday to 1194bps, its widest level yet, before turning around and ending -30bps tighter at 1086bps. This turn around was seemingly sparked by Nvidia CEO Jensen Huang coming to the AI computing company’s defense amid its sharp selloff in recent days. The comments likely contributed to a broad dip buying in Tech seen during the US trading session. The Philly Semi index was down over -4% in early trading before rebounding to closing down “just” -0.88% lower but still for its 7th consecutive loss. 10yr US Treasury yields were down -12.7bps due to the risk-off and yet 378 names in the S&P 500 were higher on the day and the index managed to end up with a +0.33% gain and stay within a percent of its record high. Even the NASDAQ itself pared back its losses, having hit an intraday low of -1.44% at the open, to scrape a slight +0.08% gain. The KOSPI is back up over 4% this morning as well.

Drilling deeper into the continued AI volatility, CoreWeave's equity also recovered from being down -9.54% at the lows to close up +5.94% yesterday. In terms of other comments from Nvidia CEO Huang, which turned around the session, he noted that “CoreWeave’s strength is improving every day”, before adding “I’m optimistic. Their cost of capital is actually decreasing.” While that is true given when the company issued its current debt, the market is pointing to a higher cost of capital now and increased refinancing costs in the future, so it's one to continue to watch. I explored some of these moves in more depth in my chart of the day yesterday (link here), which showed that for now at least, AI-linked financing costs aren’t excessive relative to the rest of the credit stack but there are outliers starting to emerge. Indeed, Oracle is the other main outlier and the stock was down -8.83% at the lows yesterday before recovering to close +2.02% higher.

Overnight, Kevin Warsh has just spoken at the IMF conference and perhaps the most important thing was what he didn’t say. With the Fed about to enter its blackout ahead of the October 27-28 meeting, Warsh declined to push back against rate expectations, saying he doesn’t “prejudge meetings”, despite this week’s hotter inflation numbers. Instead, he was strikingly upbeat about the US economy, talking about a “massive investment surge” and the potentially huge productivity benefits from AI. Markets took the lack of hawkishness as good news, with October hike pricing dropping to around 15% from roughly 30% as he spoke, while S&P and Nasdaq futures are both +0.15% higher having been negative for most of the session before he spoke. Stoxx futures are +0.68% higher.

A recovery in Asian equity markets had already been in full force before Warsh but has continued after. South Korea's chip-heavy KOSPI (+4.28%) is leading gains after tumbling nearly 8% yesterday, a move that pushed the index to its lowest close since April. Elsewhere, the Nikkei (+1.83%) is also trading firmly higher, recovering a portion of Thursday's steep losses as semiconductor stocks have regained ground. Chinese equities are likewise advancing, with the Hang Seng (+1.25%), CSI 300 (+0.75%) and the Shanghai Composite (+0.95%) all higher. In contrast, Indonesia's Jakarta Composite is plunging nearly -11.0% in its steepest one-day decline since January 1998 after MSCI proposed reclassifying the country from emerging-market to standalone-market status.

Warsh's comments overnight actually followed another hawkish round of Fed speakers ahead of the upcoming Fed blackout period. Federal Reserve Bank of San Francisco President Daly said that she had changed her view from earlier this year that the Fed should “look through” supply shocks, saying “Do the conventional pieces of wisdom — where our tool doesn’t really work for supply shocks and they dissipate on their own — does that really apply when the shocks are overlapping and they’re long-lived?” Federal Reserve Bank of Cleveland President Hammack joined her in these concerns, adding that “at some point businesses start building in an expectation that more of these are going to come, and that prices are just going to keep going up.”

However the theme of the day was a big global rate rally, as the prospect of slower AI growth pushed yields lower across the board. So, the 2yr yield (-5.9bps) fell to 4.74%, whilst the 10yr yield (-12.7bps) was down to 5.06%. And this was a global pattern as well, with yields on 10yr bunds (-5.3bps), OATs (-8.5bps) and BTPs (-6.7bps) all falling over the session.

But even as bonds were rallying, a striking feature was it took place despite another batch of hawkish US data. So in other words, AI growth concerns continued to outweigh the inflation impulse when it came to yields. Most notably, there was a huge upside surprise in PPI inflation, with headline inflation up +1.3% in September (vs. +0.6% expected). In fact, it was the strongest monthly jump in producer prices since March 2022, shortly after Russia’s invasion of Ukraine. Moreover, the core measures were also stronger than expected, with the measure excluding food, energy and trade services up +0.5% on the month (vs. +0.3% expected). So as with the CPI, the release helped to fuel concerns that inflation was broadening out beyond energy. Taking into account the PPI and CPI components, our US econ team is projecting a +0.37% monthly increase for PCE.

The hawkish data impulse was also clear in the labour market, as the weekly initial jobless claims also remained low in the week ending October 10, coming in at just 199k (vs. 200k expected). So that kept the 4-week moving average broadly steady at 198.5k, only up slightly from its 198.25k level the previous week. In addition, the retail sales number was also stronger than expected, rising +0.8% in September (vs. +0.3% expected). So with the latest data, that left the Atlanta Fed’s GDPNow estimate at an annualised pace of +3.6% for Q3.

Earlier in Europe, markets put in a relatively stronger performance, as they remained more insulated from the AI-related issues. So the STOXX 600 (+0.38%) actually put in a second consecutive gain, taking the index to a 3-week high. That included particularly strong gains for the FTSE 100 (+1.08%) and France’s CAC 40 (+0.78%), although Italy’s FTSE MIB (-0.72%) was a relative underperformer. In the meantime, gilts saw a relative underperformance, with the 10yr yield only down -5.0bps on the day which came as the UK GDP release for August was stronger than expected. That showed GDP up +0.1% (vs. -0.1% expected), which meant the rolling 3-month growth rate was at +0.7% compared to the previous three months (vs. +0.5% expected).

Looking at the day ahead, and it’s a quiet one ahead. However, we will get data on US industrial production and capacity utilization for September. In the Euro Area, there’s also the final CPI print for September.

Tyler Durden Fri, 10/16/2026 - 08:28

CoreWeave Founders Cashed Out $3.3 Billion Before The Meltdown

Zero Hedge -

CoreWeave Founders Cashed Out $3.3 Billion Before The Meltdown

Before CoreWeave imploded, its three co-founders had been busy dumping stock, a lot of it, totaling $3.3 billion since the company's March 2025 IPO. The AI cloud provider rents access to Nvidia-powered data centers that fuel the AI circular financing scheme. Its unsecured bonds due in 2032 have crossed into distressed territory, and its five-year CDS spreads have blown out as debt levels at hyperscalers and neocloud providers come into question.

Michael Intrator, Brian Venturo and Brannin McBee sold $2.4 billion this year alone, according to Bloomberg's new report on corporate filings.

Intrator has sold more than $907 million in shares this year. McBee's sales since the IPO total $1.06 billion, equivalent to 40.4% of his undiluted stake at the listing. Venturo has sold more than $1.2 billion, representing over 35% of his original holding.

As musician Kenny Rogers once sang, "You got to know when to hold 'em, know when to fold 'em, know when to walk away, and know when to run..."

CoreWeave shares have plunged more than 50% from their May peak, erasing $15 billion of the founders' paper wealth.

By late in the week, CoreWeave's 2032 bonds traded at deeply distressed levels. The 9.625% notes due in 2032 tumbled to nearly 76 cents on the dollar, a level that typically signals distress.

CoreWeave's CDS spread had also reached a record of 1,117 bps by the end of the week, implying 63% odds of a default within five years.

On Thursday, we laid out why Gartner expects over 80% of neoclouds to fold, and we hinted at the big problem: CoreWeave is the borrower on its own unsecured bonds, and it is also the tenant that is supposed to pay the rent on a big chunk of the junk-rated data center bonds issued by other companies. If CoreWeave's cost of capital is "decreasing" at 16%, what does that make the cost of capital for the companies whose bonds are backed by CoreWeave's lease payments?

Related:

Deutsche Bank chimed in:

Charting CoreWeave's top executives dumping stock:

Michael Intrator

Brian Venturo

Brannin McBee

Kenny Rogers said it best: "You got to know when to hold 'em, know when to fold 'em, know when to walk away, and know when to run..."

Tyler Durden Fri, 10/16/2026 - 08:20

Americans' Trust In Fellow Voters Falls To Fifty Year Low; Survey Finds

Zero Hedge -

Americans' Trust In Fellow Voters Falls To Fifty Year Low; Survey Finds

Authored by Bryan Hyde via American Greatness,

Americans' trust in their fellow citizens' voting judgment has fallen to its lowest recorded level in more than five decades, according to a recently published Gallup survey.

American voters' growing distrust of political leaders and institutions now extends to one another, with Democrats and Republicans showing similar levels of skepticism.

According to Gallup, 51% of U.S. adults have a great deal or fair amount of trust in Americans as a whole to make democratic judgments - the lowest reading since Gallup began tracking the measure in 1974.

Axios reports the distrust cuts across party lines with just 53 percent of Democrats, 51 percent of Republicans and 49 percent of independents trusting Americans' ability to make democratic decisions.

While the public's skepticism was historically aimed at political leaders and government institutions, the growing partisan divide has now caused citizens to lose faith in one another, reflecting a deeper systemic shift.

According to the Pew Research Center, public trust in the electorate's democratic judgment has been on a downward trajectory for several decades, accelerating sharply in recent years.

Trust stood at 86 percent in 1976 and 78 percent in both 2002 and 2005, but has stayed below 60percent since 2018, according to Gallup.

The Gallup survey found that Americans have more trust in their local government (67 percent) and state government (55 percent) than in their fellow citizens' democratic judgment (51 percent), according to Axios.

Democrats are more likely than Republicans and independents to trust both local and state governments.

Gallup reports Republicans still largely retain trust in the federal government, albeit somewhat less than a year ago.

The survey also revealed that 42 percent of Americans say they trust politicians who hold or seek public office, while 33 percent trust the news media.

The erosion of peer-to-peer trust is particularly concerning to political scientists who say the trend poses a unique challenge to democratic norms.

When voters view the opposing side not merely as political rivals but as fundamentally incapable of sound democratic decision-making, it undermines the willingness of the defeated party to accept election outcomes as valid.

Gallup surveyed 1,000 U.S. adults by landline and cellphone Sept. 1-17, 2026 with a margin of error of plus or minus 4 percentage points.

Tyler Durden Fri, 10/16/2026 - 08:05

Beijing Tightens Grip On Solar Exports: Will Trump Play America's Quartz Card?

Zero Hedge -

Beijing Tightens Grip On Solar Exports: Will Trump Play America's Quartz Card?

Beijing's new restrictions on advanced solar technologies and equipment suggest the Trump-Xi meeting in Washington did little to ease trade tensions. The new measures aim to preserve China's technological advantage as the US and India expand domestic solar manufacturing. This reinforces ongoing concerns about critical materials, where Beijing has placed export controls on tungsten, germanium, gallium, and antimony.

Bloomberg cites a statement released by China's Ministry of Commerce earlier this morning announcing that it would add 12 solar-related technologies and core equipment to its export-control list, citing national security concerns. The changes form part of a broader revision covering 40 technologies, including AI and biopharmaceuticals.

"In recent years, the application of solar technology in sensitive fields such as aerospace, national defense, unmanned equipment, and high-security-level infrastructure has been continuously expanding," the ministry said in the statement.

The statement continued, "The national security risks that may be caused by the export of solar technology have been constantly rising. It is necessary to implement timely and appropriate supervision."

The measures include a ban on exports of production technology for perovskite and solar modules, advanced technologies that offer higher efficiency and potential use in space-based solar power. Restrictions will also apply to certain technologies used to produce polysilicon, a key solar-panel material.

According to BloombergNEF analysts, the new controls could complicate efforts to diversify the global solar supply chain. Manufacturers in the US and India still depend on China for some critical materials, equipment, and technologies.

The question now is how the Trump administration will respond, if it can.

Trump administration trade officials could restrict exports of US high-purity quartz to China through export controls and licensing requirements.

China's solar dominance remains vulnerable to restrictions on US-sourced high-purity quartz, giving Trump potential leverage.

Tyler Durden Fri, 10/16/2026 - 07:45

Britain Is Accelerating Towards Crisis

Zero Hedge -

Britain Is Accelerating Towards Crisis

Authored by David Betz and Michael Rainsborough via The Daily Sceptic,

Something is going badly wrong across Western societies, and the sense of political dislocation is no longer a fringe concern. Trust in institutions has fallen, established political parties are losing support and arguments over immigration and national identity have become sharp dividing lines.

In Germany, the President now warns openly of a return to the political divisions of the Weimar era. In France, a protest movement that began in schools has spread across the country, bringing arson, mass arrests and violent clashes with riot police to cities from Strasbourg to Marseille. Across Europe, insurgent parties of Left and Right prosper on dissatisfaction with political systems that seem increasingly unable to correct themselves. Britain exhibits the same symptoms. The question is why governments confronted by such conditions so often appear to aggravate the problems rather than address their causes.

Aggravating the conditions driving the crisis follows the logic of accelerationism. Most closely associated with the British philosopher Nick Land, accelerationism holds that an existing order contains forces which, once unleashed, drive change forward and ultimately overwhelm attempts to restrain them. Rather than arrest the process, accelerationist thought embraces its intensification, although versions of the idea on Left and Right differ markedly over where it might lead. The essential rationale remains: if the existing order contains forces capable of destroying or transforming it, remove the restraints and let them run their course.

Judged by that standard, Britain's ruling classes are accelerationists par excellence. They oversee economic stagnation, mounting national debt, growing welfare dependency, the decay of town centres and public services, and deepening social divisions, compounded by rapid demographic change and repeated failures to deliver effective immigration controls. Their own reports document segregation, declining trust and failures of integration, yet governments refuse to change the policies contributing to those problems. As opposition becomes more organised and disruptive, the state responds with surveillance and speech restrictions, as well as two-tier policing and justice. Grievance produces resistance, resistance produces stronger enforcement, and stronger enforcement fuels the grievance.

We first raised the likelihood of Britain moving towards violent social breakdown in a short article 'The British Road to Dirty War' in January 2019. At that time the prognosis was seen as controversial, not least within our own university. We were 'cancelled' and removed from our positions of authority in the Department of War Studies for daring to raise this heretical possibility.

Now, the prospect is no longer confined to supposedly dissenting academics. In June 2026, Conservative leader Kemi Badenoch warned that communal divisions risked taking Britain towards civil war. What was once been dismissed as an alarmist prediction was now being voiced by the leader of the opposition. Recognising the danger is one thing, though; reconsidering the policies contributing to the problem is quite another.

Governments are not spectators to the forces at work, which raises the most fundamental - and still largely unanswered - question in the civil war debate: why, despite endless warnings about growing social fracture and the prospect of civil strife, do Britain's ruling classes continue pursuing policies that exacerbate these tensions? Why persist on a course that threatens to unleash forces capable of sweeping away the very political order upon which their own survival depends?

Is it simply incompetence?

The current debate over immigration illustrates this paradox most clearly. So, let's begin from the obvious explanation: that it is all a case of ineptitude.

There is plenty of evidence of incompetence, but as an explanation for the failure to tackle the wider problems generated by unconstrained immigration, legal and illegal alike, it doesn't quite wash. For example, consecutive administrations have promised to reduce immigration but then consciously moved in the opposite direction. Brexit should have removed one familiar explanation for the inability to control national borders. Instead, the system introduced in 2021 widened access to overseas labour by lowering skills and salary thresholds, removing the cap on skilled workers and abolishing the resident labour market test. Net migration subsequently reached 944,000 in the year ending March 2023. The rules were later tightened, and the figures fell but remain historically high.

Nor can governments claim that the negative social consequences are a surprise. As far back as 2001, the Cantle Report after the riots in Bradford and Oldham described communities living "parallel lives". As Home Secretary, Theresa May warned in 2010 that poorly managed immigration placed pressure on public services and damaged community relations. David Cameron declared state multiculturalism a failure in 2011. The Casey Review reiterated many of these findings in 2016. In November 2024, the Government stated that its intent was to restore order to a "broken" immigration system. In 2025 Keir Starmer warned of Britain becoming an "island of strangers", while the Government's 2026 social cohesion plan acknowledges similar problems.

The recurrence of such warnings points towards more than poor judgement. Other forces are clearly at work. For example, large employers, notably in the health and social care sectors, have come to depend heavily upon international recruitment, giving them a powerful interest in maintaining existing arrangements, while the detrimental social impacts are borne by the population at large, including fiscal costs, pressure upon housing, infrastructure, health and welfare services, wage suppression and rising crime, especially in sexual offending.

These social costs did not have to be distributed in this way. Employers could have been encouraged to invest more heavily in domestic recruitment, training and retention. Such choices would have imposed burdens of their own, but political decisions necessarily involve trade-offs. Governments instead accommodated business demands for access to overseas labour while leaving the wider population, especially those on lower incomes and in already deprived areas, to bear the burden.

Over time, the logic acquired a momentum of its own. Dependence upon overseas labour was increasingly cited as a reason why immigration could not substantially be reduced. Policy created dependency; dependency became the argument for continuing the policy. Cue the inevitable smug Question Time audience member who bewails that without migrants, who will staff the NHS, and more importantly, who will serve us in Pret?

Incompetence alone cannot explain why governments pursue policies that heighten the danger of civil strife. Governments have certainly miscalculated, but they have also made deliberate choices, sustaining existing arrangements long after the resulting social tensions had been officially admitted.

Another failure, another report

Faced with declining social cohesion, governments have proved far readier to devise new administrative remedies than to reconsider the policies contributing to the problem. The latest example is Protecting What Matters, the Government's 2026 social cohesion plan. It acknowledges that large-scale migration makes community bonds harder to maintain, points to continuing segregation and records falling trust and worsening tensions.

Having diagnosed the problems, Whitehall proposes national integration standards, local cohesion plans, new mechanisms for detecting communal friction and a Social Cohesion Measurement Framework. After 25 years of reports documenting deepening societal divisions, the answer is apparently another programme for managing the consequences, while leaving the policies contributing to those divisions untouched. One set of policies creates the problems that justify another.

To illustrate the contradictory thinking at work, in March 2026 Home Secretary Shabana Mahmood accepted that people seeing illegal small-boat arrivals and the pace of immigration more generally had good reason to feel that matters were "out of control". Yet having conceded the failure of control, she turned to what she regarded as the more grievous threat: the growth of ethno-nationalism. Government policies, in other words, had provoked precisely the political reaction she now proposed to combat.

Combating the rise of the 'far-Right' gives government a new set of tasks. Anger over immigration is treated as a threat to social cohesion; hostility towards immigration becomes a potential source of extremism; communal tensions require monitoring and intervention. The policies generating much of the discontent stay in place, while government expands its efforts to contain the political reaction.

The accelerationist dynamic can therefore be summarised as a feedback loop. Policies that generate discontent are maintained; government seeks to contain the reaction they have caused; containment further exacerbates the grievance against the state. By treating the political expression of that grievance as a problem to be suppressed, the authorities intensify the very forces they are trying to control.

When political correction fails

Democratic politics depends upon the possibility of correction. Governments can be removed, policies reversed and lost arguments fought again at the next election. People can profoundly dislike a policy while accepting the political system, provided they retain confidence that democratic institutions offer a peaceful means of changing the direction of policy.

The scale and pace of recent immigration have tested that bargain. Governments of both major parties have promised greater control, yet policy has either barely changed or failed to deliver the promised results. The lesson is corrosive: when elections fail to translate public demands into political change, the appeal of seeking redress through other means inevitably grows.

Loss of faith in the capacity of elections to bring about meaningful change also extends to the institutions responsible for implementing government policy. The civil service, courts and police cease to appear as neutral instruments of democratic governance and come to be seen as obstacles to popular will, seemingly unresponsive to demands expressed through the ballot box.

Mismanaged immigration also accelerates the communalisation of politics. Competition over housing, schools and public resources, alongside disputes over cultural norms and practices, becomes organised increasingly around ethnic or religious identities. Government reinforces these divisions when it consults faith and community organisations, directs programmes towards particular groups and seeks representatives to speak on their behalf. A state that encourages minorities to consolidate politically along communal lines should hardly be surprised when the majority begins to do the same, and nativist demands follow.

If elections fail to change policy, while institutions meant to arbitrate political disputes are themselves seen as favouring competing communal interests, confidence that the system offers a peaceful route to political change begins to collapse. Opposition then moves beyond electoral politics. Protest becomes more confrontational, direct action more attractive and resistance easier to justify.

When containment becomes escalation

As opposition moves from protest to direct obstruction, the full weight of the state is brought to bear against those who resist. At Eastney Marina in Portsmouth, the authorities facilitated the landing and onward transport of migrants brought across the Channel by criminal smuggling networks, despite fierce local opposition. The determination to secure their passage stood in stark contrast to the refusal to reconsider the policies that had provoked the confrontation.

Such confrontations become tests of government authority: whether the state can enforce its decisions in the face of organised resistance. For those resisting, the same confrontation raises a question of legitimacy: whether governments that have consistently ignored demands for political change can still claim the obedience of their citizens.

Once resistance challenges the state's authority, changing course becomes politically more difficult than an earlier correction would have been. A policy reversal secured through ordinary politics can be defended on its merits; one made under pressure from direct action risks demonstrating that disruption works. The policy becomes a test of the government's resolve, giving ministers another reason to hold their ground.

For those resisting, the lesson is precisely the opposite, providing another reason to question the state's legitimacy. Elections, manifesto promises and official reviews have failed to deliver the promised reductions in immigration. Yet a government perceived as unwilling to secure the national borders proves ready to deploy its coercive powers against those challenging its decisions. The contrast reinforces the belief that open defiance is the only language the state appears to understand.

The two responses feed upon each other. Resistance gives government stronger reasons to assert its authority; the resulting enforcement deepens the grievances driving resistance. A classic escalatory dynamic develops, with each side supplying the other with reasons for its next move.

The confrontation over illegal Channel crossings thus develops into a more fundamental struggle over political power: whether change can still be secured through ordinary politics, or whether the outcome will increasingly be settled by force.

The self-preservation trap

As things deteriorate, the state is much better equipped to suppress a protest than to address its underlying causes. No comparable machinery springs into action when a policy fails for 20 years. Revising immigration policy requires ministers to confront organised interests, institutional dependencies and assumptions embedded across government. Arresting someone who blocks a port is considerably easier than reconsidering the policies that brought them there in the first place.

The grievances behind such protests have accumulated through years of political choices whose costs have been deferred, dispersed or transferred elsewhere. Some difficulties have arisen from governmental inaction; others are the direct result of policies deliberately pursued. Yet governments that have shown little inclination to address these problems become remarkably decisive when the resulting tensions threaten their authority. The authoritarian impulse asserts itself as those in power seek to defend the political order over which they preside.

Accidental accelerationists?

Accelerationism ordinarily implies intention. There is little reason to presume that Britain's ruling classes consciously seek the social upheaval or political destruction that accelerationist ideas envisage. Governments, however, are hardly innocent bystanders to the forces they help set in motion. They decide which interests to accommodate, determine which costs they are prepared to impose and follow the same course long after the dangers are plain to see. Absence of intention does not imply absence of responsibility.

Mass immigration and multiculturalism provide the clearest illustration. Neither simply happened to Britain. Both reflected political choices and, in some quarters, ideological convictions about diversity, national identity and the kind of society Britain ought to become. No democratic mandate was ever sought for so profound a transformation of British society.

The political and institutional interests sustaining mass immigration and multiculturalism also evolve over time. One government liberalises immigration for economic reasons; another preserves the system because public services have become dependent upon overseas recruitment; institutions built around multicultural policies acquire constituencies, practices and assumptions of their own. Later governments inherit both the policies and the costs of dismantling them. Choice becomes interest, interest hardens into dependency, and dependency is then presented as necessity.

Britain's present difficulties are therefore no mere accident. The policies contributing to them were consciously chosen, defended and sustained despite successive official warnings about their effects.

So, are they accelerationists?

Why, then, do Britain's ruling classes continue along a course that increases the danger of civil conflict? The answer lies in how the different forces we have examined combine to reinforce one another. Six propositions bring the argument together.

1. Incompetence explains part of the failure but cannot explain the refusal to change course. Governments make bad decisions, misjudge consequences and fail to deliver what they publicly promise. But such failings cannot adequately explain why, when the dangers have long been recognised, governments of both major parties nevertheless pursue much the same policies.

2. Powerful interests have a stake in maintaining the status quo. Employers and public services have become heavily dependent on overseas recruitment. Their interests are organised and well represented in government. Governments face stronger incentives to accommodate these organised interests than to address the consequences borne by the population at large.

3. Ideology shapes what governments are prepared to recognise and reconsider. Immigration and multiculturalism reflect convictions about diversity, national identity and the desirability of social transformation. Such beliefs influence which outcomes governments welcome, which difficulties they tolerate and which objections they regard as legitimate. Political commitments can survive mounting evidence that the resulting changes are generating serious divisions.

4. Political choices create institutional dependencies that make reversal progressively harder. Employers and public services organise staffing around overseas recruitment, while government builds institutions around the society its policies have helped create. Over time, decisions acquire powerful defenders and become embedded in administrative practice. Reversing these policies then requires governments to confront interests, assumptions and dependencies that their predecessors helped establish.

5. The failure of democratic correction encourages opposition beyond ordinary politics. Voters are promised greater control over national borders, but governments fail to deliver. Reports identify problems without resolving them; elections change governments without changing the direction of policy. As confidence in democratic redress weakens, resistance becomes more organised and disruptive. The failure to address grievances through established political channels creates the conditions in which more confrontational methods acquire greater appeal.

6. The defence of political authority can become a source of further escalation. Once resistance challenges the state's ability to enforce its decisions, changing course risks appearing to reward direct action and weaken formal authority. Governments therefore become more inclined to suppress opposition, even as the causes of discontent go unaddressed. Stronger enforcement, in turn, reinforces the conviction among opponents that the democratic process offers no effective remedy. The effort to preserve authority risks intensifying the confrontation that threatens its legitimacy.

So, are Britain's ruling classes the ultimate accelerationists? Not in the literal sense, of course. Accelerationism consciously embraces forces within an existing order whose intensification drives towards its destruction or transformation. Britain's ruling classes, one assumes, do not subscribe to any such doctrine. Yet their policies have set in motion a recognisably accelerationist dynamic. As elections repeatedly fail to produce the promised changes in policy, governments become more determined to assert their authority over those who resist. Governments unable to address the causes of political conflict prove considerably more capable of policing dissent. Suppressing resistance is easier, at least in the short term, than correcting the conditions that generate resistance.

Britain's ruling classes need not seek the destruction of the existing order. They need only defend it until self-preservation becomes self-destruction.

David Betz is Professor of War in the Modern World, King's College London. Michael Rainsborough is Professor of Strategic Theory and Director of the Centre for Future Defence and National Security, Canberra.

Tyler Durden Fri, 10/16/2026 - 07:20

"Perfectly-Integrated" African Migrant On Trial For Strangling, Dismembering His Wife

Zero Hedge -

"Perfectly-Integrated" African Migrant On Trial For Strangling, Dismembering His Wife

Via Remix News

An African man, who was described as "perfectly integrated," is on trial in Bonn on charges connected to the strangling murder of his wife, whom he then dismembered. The woman's remains were later found in several locations across Germany, according to court proceedings.

Asmerom G., 42, an Eritrean national, faces the charges in Bonn Regional Court in North Rhine-Westphalia. The case stems from events in mid-November 2025 involving his wife, Weghata A., 32. The couple had married in Ethiopia in 2019, and she arrived in Germany in 2024 through family reunification.

The defendant allegedly met his wife, 32-year-old Weghata A., inside his car, where they began arguing on their way back from a church visit. According to Bonner Generalanzeiger newspaper, Asmerom G. later told police that his wife told him their 3-month-old girl was not his biological child. He reportedly could not remember what happened next.

According to prosecutors, Asmerom G. then strangled his wife in the back seat of the car in a parking lot in Bonn, directly in front of the baby who was sitting in a child seat.

After the crime, the defendant is said to have driven with the body and the baby in the car to the Monastery of Saint Anthony, 160 kilometers away, where he abandoned the little girl in the stroller when it was only 2 degrees Celsius (35 degrees Fahrenheit).

Fortunately for the girl, monks found the child just 40 minutes after she was dropped off.

Asmerom G. then went to work dismembering Weghata's body, including packing her hands and head in plastic bags.

He left the torso behind, which was found at the end of November 2025. Asmerom G. left the body parts on the side of the autobahn, on the A45. The head of the woman was discovered by garbage collectors in April 2026.

Asmerom G. was arrested in Ethiopia and extradited to Germany. He has a prior conviction for aggravated assault. On the first day of the trial, he declined to comment on the allegations. Defense attorney Martin Kretschmer has said the case rests largely on DNA evidence and mobile-phone data.

Kretschmer told Bild newspaper, "Until his arrest, he was considered perfectly integrated."

German media was even singing his praises in 2016. The man from Eritrea had landed a job as an electrical assistant at a firm in Rheinbach, in North Rhine-Westphalia, and gave interviews about leaving his homeland three years earlier to escape political persecution.

He wanted German citizenship, he said. His boss at the time was quick to describe Asmerom G. as talented, reliable, and "capable of anything," according to Bild newspaper.

However, then trouble began. Within a year, Asmerom G. was in trouble with the law. A brawl led to a conviction for grievous bodily harm at Siegburg District Court, earning him a six-month suspended sentence.

He moved on from Rheinbach and took up work behind the wheel of a freight truck. Somewhere along the way, he made a trip back to his home country - for reasons that remain unclear - and returned to Germany with a woman named Weghata A., who was 31 at the time, his wife under Eritrean law. On July 26, 2025, she delivered their daughter.

The child is now in the care of authorities. Lawyer Gesine Ickert, representing the daughter and the deceased's father, has stated that the child is well looked after under the circumstances.

The trial continues.

Tyler Durden Fri, 10/16/2026 - 06:30

Legendary Swiss Bank "Thinks The Unthinkable"; Report

Zero Hedge -

Legendary Swiss Bank "Thinks The Unthinkable"; Report

Swiss banking giant UBS is considering abandoning its home country and relocating to the United States as a bitter battle over government regulations threatens to upend one of the world's most powerful financial institutions.

The Zurich-based banking powerhouse and its advisers have drawn up contingency plans to move its headquarters abroad if Swiss lawmakers impose sweeping new capital requirements, according to The Wall Street Journal.

The bank has also received approaches from potential American deal partners, although no negotiations are underway and no formal steps toward a transaction have been taken.

Such a move would mark a stunning rupture between Switzerland and a financial institution synonymous with the country's centuries-old reputation as a global banking haven.

Among the options reportedly under consideration are acquiring a U.S. financial institution and redomiciling, merging with a European rival or selling UBS to an American banking giant.

The escalating confrontation traces back to the spectacular 2023 collapse of Credit Suisse, which forced UBS to absorb its longtime rival in a government-backed emergency rescue.

Last month, Switzerland's upper house of parliament backed a proposal requiring UBS to support its foreign subsidiaries with 90% common equity tier 1 capital.

UBS estimates the measure would force it to hold roughly $16 billion in additional capital, phased in over seven years.

The proposal still requires approval from parliament's lower house, where it could be watered down, and a final decision is not expected before next year.

An earlier government proposal was even more aggressive, with UBS estimating it would have required approximately $24 billion in additional capital.

UBS has fiercely resisted the measures, warning that the requirements would leave it at a severe competitive disadvantage against American and European rivals.

The regulatory battle has also sparked a backlash from major shareholders.

Investment firm Artisan Partners, which manages more than 60 million UBS shares, urged the bank's board in an October 1 letter to abandon Switzerland, blasting the proposed regulations as "punitive" and arguing there was no compelling reason to remain a Swiss company.

Activist investor Cevian Capital has similarly warned that the reforms would make it "not viable" to operate a global bank from Switzerland.

The threat of a dramatic departure has been building for months.

UBS was first reported to be exploring a potential relocation in early 2025, while Chairman Colm Kelleher later held private discussions with Treasury Secretary Scott Bessent about what moving the bank's legal home to America might entail.

Losing UBS could deal a devastating blow to Switzerland's status as one of the world's premier financial centers.

The bank holds roughly $1.7 trillion in assets, equivalent to approximately 150% of Switzerland's entire economic output.

However, Swiss officials are no showing any signs of backing down.

Swiss Finance Minister Karin Keller-Sutter dismissed the relocation threat, warning that abandoning the country would be "far more expensive and legally complex" than complying with the proposed regulations.

"It would also cease to be a Swiss bank," she said in an interview with Schweiz am Wochenende, arguing that UBS's business model depends on Switzerland's legal system and political stability.

"UBS certainly doesn't have to leave Switzerland. Many analysts and specialists agree that the requirements are reasonable and easily manageable for UBS," she added. "The capital inflows experienced by private banks during the conflicts in the Middle East clearly demonstrate the confidence in Switzerland as a business location."

Swiss National Bank President Martin Schlegel echoed those concerns.

"Ultimately, the choice of headquarters is a decision for UBS," Schlegel told public broadcaster SRF. "Of course, it's a large bank and brings benefits to Switzerland. But Switzerland, of course, also brings benefits to UBS."

No final decision has been made, and UBS could ultimately choose to remain in Switzerland.

Tyler Durden Fri, 10/16/2026 - 05:45

Trump Says Montana To Get Pentagon's New 'Super Range' For Weapons Testing

Zero Hedge -

Trump Says Montana To Get Pentagon's New 'Super Range' For Weapons Testing

President Donald Trump announced at a campaign rally in Kalispell, Montana, on Oct. 14 that the Department of War has chosen the state to host a new weapons testing site. He did not say where in Montana it will be, but we're sure residents are 'overjoyed' at the news.

President Donald Trump speaks during a rally at the Majestic Valley Arena in Kalispell, Mont., on Oct. 14, 2026. Travis Gillmore/The Epoch Times

"Montana will help ensure the American military always reigns supreme," Trump told the crowd at the Majestic Valley Arena, adding: "A lot of other people wanted it also."

He called the project a "super range for testing advanced weapons and technologies, including potential autonomous weapons, space and electronic warfare technology, supersonics, and hypersonics."

As the Epoch Times notes further,

The announcement is part of the Trump administration's agenda to rebuild the national defense base and accelerate innovation with modernization efforts, including the testing of advanced weapons systems and integration of artificial intelligence.

Details of the new project, including timeline, budget, and operational processes, are limited. The Epoch Times has reached out to the War Department for comment.

It is unclear whether the site will be a standalone operation or an expansion of existing defense infrastructure in the Treasure State, including the Montana Spaceport & Test Range and the Limestone Hills Innovation & Test Campus.

The state's broad spaces and sparse populations make them top candidates for weapons testing.

Midterm Races

Trump was in Montana stumping for Republican candidates running in the midterms. More than 7,000 people waited through traffic jams that took hours to resolve as cars made their way into the parking area to see the president speak.

Voters will soon decide which party controls the legislative branch of government.

Key issues for Montanans include the price of energy and the cost of living.

"Fuel prices are the main thing. Everything runs on diesel," Charles Chandler of Libby, in Lincoln County, told The Epoch Times, noting his desire to see the war with Iran end "one way or the other."

Others in the crowd agreed, repeatedly listing the price of food and fuel as top-of-mind issues. Several said the new weapons site could bring much-needed economic activity to the region.

One of the races on the national map that is being seen as competitive is taking place in the state's First Congressional District, where Republican Aaron Flint is battling Democrat Sam Forstag to replace retiring Rep. Ryan Zinke (R-Mont.).

"We're going to elect a true American patriot," Trump said, backing Flint. "He's going to Congress to be a warrior."

Flint, a fifth-generation Montanan, enlisted in the Army after the 9/11 attacks and served in the military for more than 20 years. He criticized his opponent, originally from Portland, Oregon, as a West Coast implant.

"If ever there were a race in the United States of America that was the definition of common sense versus crazy, this is the race," Flint told voters at the rally.

Forstag, a Forest Service smokejumper, union leader, and former lobbyist, is running on a platform prioritizing healthcare and housing reforms and a campaign finance overhaul, including a promise to overturn the Supreme Court's 2010 Citizens United ruling.

Republican Kurt Alme is vying for the U.S. Senate seat left vacant by outgoing Sen. Steve Daines (R-Mont.) He faces Democrat Alani Bankhead and Independent Seth Bodnar, with recent polling showing the conservative with a slight edge over the split field.

Montana Gov. Greg Gianforte promised to continue his partnership with the Trump administration to support border security, tax cuts, and "unleashing American-made energy by embracing an all-of-the-above strategy, including beautiful, clean Montana coal."

While some media outlets have shown photos of empty seats at the president's recent rallies - seats located behind press risers that blocked attendees' view of the stage - the rodeo arena was standing-room-only, with additional supporters left outside watching on a big screen after the venue reached capacity.

Enthusiastic attendees of all ages, from months-old babies to a 105-year-old local highlighted by speakers, watched the president's address, and many waved signs and chanted "USA" throughout the rally.

Trump made a similar locally connected military announcement in Youngstown, Ohio, on Oct. 12, when he broke the news about a new submarine component production and repair facility.

The president visited Alaska on Oct. 13 before stopping in Arizona earlier Oct. 14. His rally schedule next takes him to Dalton, Georgia; Highland Height, Kentucky; Wichita, Kansas; and Greenville, North Carolina.

Tyler Durden Thu, 10/15/2026 - 21:30

Pentagon Eyes 'Mother Of All Bombs' For Future Iran Strikes

Zero Hedge -

Pentagon Eyes 'Mother Of All Bombs' For Future Iran Strikes

Anonymous Trump admin officials are apparently once again 'leaking' Iran war military plans to the media. The newest claim is that among potential Pentagon 'options' for a new bombing campaign against the Islamic Republic include deploying the "mother of all bombs".

Prior mainstream media reports suggested President Trump is mulling the resumption of a bombing campaign possibly even before the November midterm elections. But the president's public statements have indicated otherwise.

via Reuters

There now seems a keen and much-belated awareness at the general unpopularity of this war among the US public on the part of the administration. After all, top White House officials including Trump himself had repeatedly promised at the outset of Operation Epic Fury that it would be a swift and decisive campaign.

Officials like Rubio went from saying it could take 'days' to then offering 'four to six weeks' or else saying a couple months. But now we are seven months in, and the end-goal or point that might mark a 'mission accomplished' exit moment has never really been defined. It all along has seemed like a bombing campaign in search of a strategy.

In the meantime, outlets like CNN are running with headlines of Washington's next 'threat' against a defiant and intransigent Iranian leadership, which is busy attacking shipping in the Strait of Hormuz at levels never seen before:

The US military has developed new strike plans that include potentially using the so-called “mother of all bombs” to target Iranian energy infrastructure and nuclear sites should President Donald Trump give the order to resume combat operations either before or after the midterm elections, according to multiple US officials familiar with the matter.

Using the GBU-43/B Massive Ordnance Air Blast Bomb or MOAB, the largest non-nuclear bomb in the US arsenal, for the first time in the conflict with Iran would mark a notable escalation, even though there are doubts over how effective it would be in accomplishing any of Trump’s stated strategic objectives or tipping the balance of the war, multiple sources familiar with internal military planning discussions about potentially deploying the weapon said.

CNN does also note that "Trump is facing pressure to bring an end to the deeply unpopular war — as Republicans brace for potential political backlash from voters in the upcoming midterm elections and there is little indication the two countries are close to a negotiated resolution after more than six months of US bombing."

One wonders what the aim or purpose of such headlines touting the use of the "mother of all bombs" is. The Iranians have not changed their position. Their Ayatollah and many top officials have already been assassinated, and Tehran is signaling readiness for a prolonged war.

Iranian Parliament Speaker Mohammed Bagher Ghalibaf in a televised speech on Wednesday invoked the Iran-Iraq War, which lasted from 1980 to 1988, when speaking about what his country is ready to endure with the United States.

This suggests Iran is ready to resist for years if necessary, despite the cratering wartime economy amid sweeping Washington sanctions and unprecedented isolation from energy markets.

Tyler Durden Thu, 10/15/2026 - 21:05

Is There Any Way To Save Social Security, Or Is It Doomed?

Zero Hedge -

Is There Any Way To Save Social Security, Or Is It Doomed?

Authored by Brandon Smith via Alt-Market.us,

The young do not think about getting old, and this is to the greatest benefit of governments which spend and inflate younger generations out of any future subsidies they might one day come to rely on. For most people in Gen Z, though, there is at least a tacit acknowledgment that they are paying into a system that might not be there for them when they retire. However, their only point of reference is usually the rantings of their socialist college professors or a mob of crazed activists on TikTok.

So, naturally, the only solution they can come up with is MORE power for government, more taxation, more communism and more redistribution of wealth. In other words, give more control and more cash over to the state which already misspent their money.

The idea of pillaging the wealth of others as a shortcut to security for a single generation is not new. This plan is doomed to fail, as it has failed in nearly every socialist system with a population larger than around 10 million people.

Even in "market-capitalist welfare states" that are often cited as "successful" like Norway, Sweden, Denmark and Finland, the ability to continue retirement funding at a rate which provides a livable wage is only possible if the retiring population is much smaller than the working population.

Across the west at present, the larger Baby Boomer generation is aging completely out of the labor pool and these systems are being depleted rapidly. The demographic squeeze is tightening and in the US, those special Treasury securities are now being redeemed - Social Security is set to decline starting in 2034.

Current SS reserves are at $2.56 trillion. These reserve funds are being depleted every year by a spending deficit. The deficit is not fixed and fluctuates wildly, but the overall trend shows it is clearly growing. In 2025 the shortfall was $160 billion (that's the amount of extra money the government has to tax or borrow in order to fully cover the costs of Social Security beyond normal revenues). That deficit is projected to rise to $393 billion by 2033.

As these reserves disappear due to deficits, eventually social security payments will be reduced as a consequence.

By the time I am old enough to collect, Social Security payments will be cut by 22% (accounting for steady inflation). By the time Gen Z is old enough to collect, their SS payments will shrink by 35% with inflation included. The fund does not necessarily implode but the benefits will becomes more and more useless over time.

At bottom, the fund will be dead because it will no longer be able to adapt to inflation. Costs will continue to rise and SS will shrink exponentially. Relying on the system for retirement would be impossible. This is also assuming there is not an economic crisis event in the future which completely derails government funding for SS much sooner.

This brings up a lot of questions...

Is Social Security actually a necessary program? In the US there are currently 71 million beneficiaries of SS and out of that group around 14 million depend entirely on SS checks as their only source of income. An even larger portion of the population needs these checks as supplemental income.

In other words, the program could be scrapped, but it would be devastating to a large percentage of the public. I would argue that if the government is going to operate as an economic backstop for any group, then the elderly should be that group. Anyone who has cared for an elderly relative understands that we will all one day hit an age-wall that prevents us from generating incoming on the fly. We'll either be wealthy and flush with savings and assets, or we will be dependent on the charity of others.

Is Social Security the answer? No, not as it stands now. Many Americans believe that SS is like a savings account where their money is held until they meet the conditions of retirement. This is false. Others might consider it an insurance program, but this is also debatable. Social Security is managed more like a subsidy than a savings account or insurance. The money you paid into the system over your lifetime is long gone.

Public anger is rising among younger generations because they have to pay into subsidies that they have no expectation of benefiting from in the future. Marxist NGOs and activists take advantage of the angst and try to convince people to adopt bigger government and socialist wealth redistribution as the answer to all their problems. This will lead to calamity for the country.

So what is the solution? The vast majority of people would prefer to know that they will be taken care of in their old age. How do we ensure that the elderly are provided for without continually crushing the economy with debt? Let's go through a list of solutions...

Fundamentally Change The Way We Look At Aging And Family

Before 1935 there was no such thing as Social Security, so how did people aging out of the workforce survive? They largely relied on family to help take care of them. For hundreds of years this was the norm in the western world. At the turn of the century around 70% of elderly people lived with their children or other family members, but this practice declined rapidly from the 1920s onward.

This is why the Social Security program was popularized in the first place; far too many older Americans no longer had a family safety net and so they jumped onboard the SS train in response. This is not to say that kids should be "required" to take care of their parents, but the principle should be encouraged.

And, if you think about it, this might also help to encourage better parenting practices and more respect for the nuclear family. Who would want to be a deadbeat parent when their kids will one day be the people they rely on most in old age? Who would want to abort their children when those children are their future safety net? Who would want to get a divorce and break up their family at the risk of being destitute when they hit their twilight years?

Yes, this sounds rather mercenary, but it's foolish to discount selfish incentives as a means to keep civilization functioning. Many people don't need incentives to do the right thing, but many other people DO.

Returning to the old tradition of caring for relatives as a family or tribe would help to prevent mass destitution and suffering of older Americans should Social Security and other programs fail. This doesn't save SS, but it does make the public less dependent on the program.

At-Home Work For The Elderly

The knee-jerk reaction from many people (especially Baby Boomers) on the idea of delaying retirement is anger and outrage. I agree, to a point. These people worked their whole lives, raised families, struggled through national and global crisis events, and made it through to the other side. At 67 years old, they probably deserve a rest.

That said, life is not necessarily fair and expecting the government to be there for you is not exactly the best plan. In order for a safety net to exist for the most desperate people, those who are cognizant and functional might need to adapt. Also, there are many older Americans who would like to earn an income and keep busy but they have aged out of the normal labor pool.

With more older Americans staying in the workforce longer, Social Security deficits could be balanced and the funds could continue to flow for decades to come. For the first time in human history, senior citizens have access to digital jobs and at-home work. It's possible for many older people to function in these fields with proper training programs (and maybe tax incentives for companies that hire the elderly).

I would rather have elderly Americans taking on such work and making money at home than corporations importing a bunch of third world migrants through H-1B visa programs.

Investment Of Social Security Into Appreciating Assets (Stocks And Commodities)

This is another idea that creates deep divides among voters, with the primary question being: What happens to Social Security if there's a market crash and assets plummet in value?

But look at it this way - Over the past decade, if SS savings parked in treasuries were invested in gold and silver instead, the fund would currently have an extra $7 trillion. That would add another 12+ years to the lifespan of those savings. Investment in equities on the Dow Jones would have yielded an extra $8 trillion.

This is only a portion of SS funds and the gains would be undeniable. Is it gambling with the future, and with taxpayer money? Yes, in a way. But risks can be mitigated by diversifying between treasuries and other assets. I would argue that if we don't take radical measures like this, social security is certain to fail, so what do we have to lose?

End Early Draws On Social Security

This is one of the uglier options available, which is to stop all early drawdowns by people ages 62-66 who take SS. They already get a 30% penalty, and ending early draw would slow the drain of funds for much older people.

Cut Funding For The Top 20% Of Earners

Is this punishing people for being successful? Yes. But denying social security for the top 20% of American earners with extensive savings and assets would save $500 billion per year. This would eliminate the current deficit and any future deficits for many years to come.

If someone can live comfortably without SS after retirement, then maybe they should forgo the monthly checks so that SS can exist for others who are not so well off. Again, this is not fair, and I'm not saying I agree with the measure on principle, but if we're talking about survival of the program, this is an obvious strategy.

Increase Fertility Rates And Population Growth

Across the board, not just in the west but in the majority of countries around the world, fertility rates are dropping and populations are growing older. Without enough young people filling the workforce the elderly subset will greatly outweigh the available tax base. In other words, too many hands waiting for too little cash.

This incoming crisis has led to some nefarious people justifying some horrific options. For example, multicultural progressives use the fertility decline as an excuse for mass immigration from the third world. Hey, that's millions of new taxpayers to help support retirement funds, right? Except that these migrants destroy welfare structures and collapse funding even faster.

Other leftist governments (like Canada) are increasingly suggesting government assisted suicide as a way to reduce the elderly population and solve welfare (and healthcare) deficit problems. This is, of course, monstrous and immoral, but fears over debt collapse will lure some people into supporting many otherwise unpalatable evils.

How do we increase population naturally? The only sure way is to increase individual wealth. How do we do that? That's the question of the ages. Socialism is certainly not the answer - No socialist system has ever actually increased the wealth of the middle class without turning to free market means, and even then they tend to stifle productivity and entrepreneurship. If there's a cap on success, individual wealth will fail. This is a fact.

Is There A Better Way?

A lot of people are going to question if Social Security is even worth saving. After all, there has to be a better way. I'm not saying it is or is not worth it, that's a topic for a separate article. The only question here is, CAN Social Security be saved? The answer is yes, given the above measures along with reduced government spending.

The secondary question is - Do we have time? Only if there's not a debilitating crisis that prevents more conservative action. A new inflationary event or a monetary crash would create much bigger worries than whether or not SS will remain intact for another couple decades.

The best overall option is to not rely on SS in the first place. Investing wisely in ones own future and family while preparing for economic disruptions is the only way to ensure your later years are not an exercise in penny pinching misery.

Tyler Durden Thu, 10/15/2026 - 21:05

Justice Alito: Originalist In Full

Zero Hedge -

Justice Alito: Originalist In Full

Authored by Cully Stimson via The Epoch Times,

Justice Samuel A. Alito's new book, "So Ordered: An Originalist's View of the Constitution, the Court, and Our Country," is not a conventional judicial memoir - and that is precisely its strength. It is a carefully curated collection of 19 lectures and speeches delivered between 2007 and 2025 on subjects constitutional and cultural, solemn and unexpectedly personal. Organized around five themes, the volume offers something rarer than autobiography: a sustained encounter with the mind of one of the Supreme Court's most consequential jurists.

U.S. Supreme Court Justice Samuel Alito attends an event organized by the U.S. Embassy to the Holy See, in Rome, Italy, on Sept. 20, 2025. Vincenzo Livieri/Reuters

The settings are as varied as the subjects. Alito draws lessons from baseball, examines the globalization of judicial review, revisits the Gettysburg Address, celebrates Italian-American achievement, and reflects upon mankind's search for meaning. Across these topics, the famously reserved Justice emerges in fuller dimension. The result is not a miscellany, but a portrait of a judge who understands that law does not operate in a vacuum - and that the Constitution is inseparable from the history, habits, and character of the nation it governs. The book's five themes - originalism and textualism, the role of judges, religious liberty, threats to the Constitution, and the American experience - provide structure and urgency. Each lecture deserves attention. This review examines five of the collection's most illuminating selections, not as a substitute for the whole, but as an invitation.

Originalist Judging

Chapter One opens with a deceptively simple question: How should a judge interpret the Constitution? Alito's answer - originalism - is familiar. His treatment is not. Rather than offer another abstract defense of original public meaning, he asks what originalism looks like when practiced by judges who must decide actual cases, respect precedent, secure colleagues' votes, and live with the consequences of their rulings.

Academic theories enjoy the luxury of coherence, untroubled by circumstance. Judges do not. They operate within an inherited legal system, on multi-member courts, under the discipline of precedent, and with litigants whose liberty, property, and constitutional rights are not classroom hypotheticals. Alito therefore describes himself as a "working judicial originalist."

His organizing device is an originalist judge traveling down a highway and encountering seven exits. Six are wrong turns; the seventh - the road of academic originalism - is legitimate for scholars but often ill-suited for judges. The metaphor works because Alito's argument is not that originalism lacks direction. Rather, it is that originalists may lose their way by mistaking rigidity, antiquarianism, or theoretical purity for constitutional fidelity.

Originalism arose amid dissatisfaction with decisions of the Warren and early Burger Courts and against a jurisprudential background shaped by judicial restraint and deference to political actors. Yet originalism is not simply a doctrine of restraint. Sometimes the Constitution requires judges to invalidate the acts of elected officials. Fidelity may demand boldness.

That insight animates Alito's critique of "insecure originalism." Originalists should not recoil from considering whether their method generally produces sound results. Nor should they congratulate themselves when originalist analysis yields an absurd outcome, as though an unattractive result proved intellectual purity. The law must be followed where it leads, but the conscientious judge should recheck the map before driving over a cliff.

Alito also rejects "show it to me in black-and-white originalism," the notion that every constitutional rule must appear expressly in the document's words. Constitutional structure carries meaning. Federalism, separated powers, and institutional independence may produce necessary implications even when no clause spells them out. Originalism begins with text; it need not end with a refusal to perceive constitutional architecture.

At opposite extremes stand "Icarian" and "archaeological" originalism. The former rises so high into abstraction that constitutional language becomes a vessel for modern aspirations. If broad principles may be detached from the public understanding at ratification, originalism becomes indistinguishable from the theories it was developed to oppose.

Archaeological originalism makes the inverse mistake. It searches obscure historical materials for a legal relic that mechanically answers a modern question. Alito's discussions of Torres v. Madrid and United States v. Jones illustrate the danger. A 17th-century rule on civil arrest or an old property tort may illuminate history, but neither necessarily establishes what ordinary Americans understood the Fourth Amendment to mean. Original public meaning is not an esoteric code decipherable only by specialists equipped with pith helmets and trowels.

"Partial originalism" is similarly unsatisfactory. A ruling cannot fairly be called originalist when an originalist premise is bolted onto non-originalist doctrines that determine the outcome. Nor should "philosophical originalism" treat the Constitution as though it secretly incorporated John Locke or another favored thinker. Founding-era ideas matter, but the public ratified the Constitution, not a pantheon of political philosophers.

Academic originalism presents not error but choice. Scholars may reconstruct doctrine from first principles. Judges must contend with stare decisis, institutional stability, and the practical need to assemble a majority. Alito's discussion of McDonald v. Chicago, a 2010 Second Amendment case, shows why a historically attractive theory may be judicially imprudent if it would unsettle a century of law and open vast doctrinal territory without clear boundaries.

This is the chapter's central contribution. Alito does not dilute originalism; he disciplines it. Judging requires historical fidelity and judgment, principle and prudence, conviction and collegial compromise. Pretending judgment can be eliminated does not eliminate it. It merely conceals it.

Textualism

Chapter Two is at once a tribute, an intellectual history, and a warning. Its subject is Antonin Scalia - his methods, manner, and continuing influence - but its real concern is the rule of law. Alito argues that Scalia rescued statutory interpretation from an undisciplined search for legislative purpose, restored enacted text to its rightful place, and constrained judges who might otherwise mistake policy preferences for law.

Yet some of Scalia's heirs, Alito warns, have carried textualism beyond its sound foundations into "hypertextualism," a cramped method that ignores how language communicates meaning.

Alito wisely begins with the man. Scalia changed the Court's habits. Oral argument became sharper and more demanding. Judicial prose became clearer, livelier, and less embalmed in professional fog. Alito recounts Scalia's refusal to join his opinion in Hein v. Freedom From Religion Foundation, where Scalia called his reasoning "meaningless," inconsistent with the "rule of law," and not "sane." The anecdote demonstrates that Scalia's ferocity was directed at ideas, not persons, while revealing Alito's own measured temperament.

The chapter is strongest when reconstructing the interpretive disorder of the "BS" - before Scalia - era. Judges treated statutes as invitations to rummage through committee reports, floor statements, statutory purposes, and, when necessary, their imaginations. In Overton Park v. Volpe (1971), the Court effectively treated statutory text as a fallback when legislative history proved unclear. In Griggs v. Duke Power Co. (1971), Title VII's text was relegated to a footnote while purpose and legislative history did the work. That inversion should trouble anyone who believes Congress legislates by voting on words, not atmospherics.

Alito's stories from the Solicitor General's Office make the indictment concrete. A suspiciously convenient Senate colloquy captures legislative history's theatrical quality: lawmakers may manufacture interpretive ammunition without persuading either chamber to write the desired meaning into law.

Even better is Professor Robert Blakey's declaration, "I am the legislative history of RICO." The line is funny because, under the old regime, it was nearly plausible.

Scalia's corrective was simple: the text is the law. But Alito insists that this maxim begins interpretation; it does not end it. Judges are Congress's "faithful agents." Their task is to discern the public meaning conveyed by enacted words in context - not to divine secret motives, but neither to pretend that language consists of dictionary definitions lined up like tin soldiers.

Alito's examples involving breakfast, banks, and irony explain the difference between semantic and pragmatic meaning. Context resolves ambiguity, supplies what ordinary speakers understand without saying, and sometimes reveals that literal words convey something different from their bare semantic content.

This is not a retreat to purposivism. Alito endorses Scalia's "objectified intent" - the meaning a reasonable reader, familiar with contemporary usage and the circumstances of enactment, would attach to the text. Unexpressed intentions remain irrelevant; public meaning controls. But public meaning may include sensible inferences about what lawmakers communicated. The canons Scalia championed - noscitur a sociis, expressio unius, and ejusdem generis - work precisely because context permits those inferences.

Alito's discussion of Bostock v. Clayton County supplies the sharpest edge. He argues that the majority's reading of Title VII - treating discrimination because of sexual orientation or gender identity as discrimination "because of sex" - was not compelled by the statute's public meaning in 1964.

His criticism is methodological: the majority treated context that ordinarily illuminates meaning as categorically irrelevant. His Italian-restaurant hypothetical distills the objection: an agent who follows an instruction's literal words while knowingly defeating the principal's communicated meaning is not faithful; he is obtuse.

The chapter's vulnerability also marks its ambition. "Objective intent" is easier to invoke than administer. How much context is enough? Which evidence is reliable? When does context reveal public meaning, and when does it smuggle purpose back into the analysis? Alito does not fully answer these questions. Nevertheless, his central warning persuades. Scalia's revolution was not a command to read statutes woodenly. It demanded that judges respect enacted law, ordinary language, institutional limits, and democratic accountability.

Baseball's Lessons for Law and Life

Alito is an unapologetic baseball fanatic, and his loyalties lie firmly with the Philadelphia Phillies. His childhood hero was Richie Ashburn. He played second base and shortstop in Little League, attended Phillies Phantasy Camp while serving on the Third Circuit, and was greeted at his Supreme Court welcome dinner by the Phillie Phanatic. His chambers contain an entire corner of baseball memorabilia.

Chapter Nine opens as a genial meditation on the national pastime but becomes a compact treatise on judging, institutional legitimacy, equality, cultural cohesion, and technological hubris. Alito begins with the concrete - a checked swing, a neighborhood play, an afternoon at Connie Mack Stadium - and works toward first principles.

The organizing device is Chief Justice Roberts's comparison of judges to umpires calling balls and strikes. Alito neither rejects the analogy nor reduces it to a slogan. Rules matter. Most cases, like most pitches, have a discernible answer. But hard cases require judgment informed by text, precedent, experience, and institutional discipline. The discussion of checked swings and balks exposes a truth often obscured by legal theory: discretion is not the absence of law. Properly exercised, it is judgment bounded by law.

Alito is especially good when he turns from mechanics to character. Judges must not "sell" their calls like theatrical umpires. Their duty is not to win applause or satisfy the loudest faction, but to do justice even when the heavens - or editorial pages - appear ready to fall.

Judge Leonard Garth's admonition that "it takes courage to be a good judge" supplies the chapter's moral center. In Alito's chambers, a photograph of the two bears the inscription Fiat justitia, ruat caelum: "Let justice be done though the heavens fall." Judicial independence is not a perk for judges; it is a safeguard for litigants and the public.

The discussion of Chase Utley's notorious slide and baseball's old "neighborhood play" sharpens the inquiry. What should an official do when settled practice departs from the written rule? Courts routinely confront precedents that have drifted from constitutional or statutory text. Alito offers no easy formula. Instead, he shows why choosing between fidelity to text and fidelity to precedent is consequential, disruptive, and unavoidable. A judge who pretends otherwise is hiding the ball.

The chapter then widens its focus. Baseball once supplied a common vocabulary across regions, classes, and political persuasions. Its diminished status becomes a metaphor for national fragmentation. Alito's point is not merely nostalgic. A self-governing people need shared institutions and experiences.

His account of baseball's integration carries the lesson further. Jackie Robinson, Roy Campanella, Willie Mays, Henry Aaron, and others demonstrated that equality is both a moral imperative and a practical advantage. The Phillies' delay in signing black players was not only unjust; it was self-defeating. Merit ignored exacts a price.

Alito concludes with analytics and artificial intelligence. Baseball's statistical revolution produced more efficient strategies but a less attractive game: more strikeouts, fewer balls in play, less daring, and less joy. The analogy to law is sobering. A machine may predict outcomes, process authorities, and impose consistency. But efficiency is not the whole of justice. A legal system worthy of confidence must remain intelligible, accountable, and humane.

This is an argument that law, like baseball, depends on rules, judgment, courage, memory, and a willingness to preserve what is essential amid change. Beneath the chapter's easy cadence lies a serious charge: know the rules, honor the institution, judge people by their merits, and never confuse innovation with wisdom.

Religious Liberty and the American Republic

Chapter 10 is a history lesson, constitutional argument, and warning. Its central claim is unfashionable but straightforward: the American republic did not merely tolerate religion as an eccentric private preference. It recognized religious liberty as a preexisting right, gave it special constitutional protection, and understood religion as an ally of ordered liberty.

Alito begins with the American Catholic experience. From Maryland's founding as a refuge, through repeal of its Toleration Act, to accusations that Catholics owe their civic allegiance to Rome, he shows that anti-Catholicism is no historical curiosity. Paul Revere's "Mitred Minuet" and a modern cartoon depicting five Catholic justices in bishops' miters are separated by two centuries but animated by the same slander: that Catholic reasoning is foreign to constitutional government.

Modern cases give the chapter urgency. The contraceptive mandate, Masterpiece Cakeshop v. Colorado Civil Rights Commission (2018), Catholic Social Services, religious-school employment disputes, pandemic worship restrictions, and requests for spiritual advisers at executions expose a cultural collision. Alito identifies three accelerants: declining attachment to organized religion, the rise of a new moral code on contested social questions, and growing intolerance toward dissent.

His point is not that adherents of the new orthodoxy lack a right to their convictions. It is that constitutional peace becomes impossible when disagreement itself is treated as moral depravity.

Alito's strongest legal analysis focuses on the Free Exercise Clause. First, the Constitution singles out religion for special protection. Second, it safeguards religious exercise - not merely belief or worship, but conduct flowing from faith: teaching, evangelizing, serving the poor, observing holy days, following dietary rules, and wearing religious dress. Third, the right was historically robust enough to require exemptions from generally applicable laws, bounded by genuine threats to peace and safety. Founding-era accommodations for religious objectors - from oath requirements to militia service - make the point forcefully.

That history underwrites Alito's criticism of Employment Division v. Smith (1990), authored by Scalia, which reduced free exercise largely to a prohibition against deliberate discrimination. A regime that treats sacramental wine, kosher or halal slaughter, or religious head coverings exactly like secular conduct may be formally neutral while functionally hostile. Equal treatment is not always liberty.

The Establishment Clause discussion is equally important. Alito rejects the notion that the Constitution commands a sterile public square. The First Congress appointed chaplains while drafting the Bill of Rights; legislative prayer is therefore evidence of the constitutional design, not an embarrassing exception. The American settlement is not French laïcité. It prevents governmental establishment and control while preserving a public culture in which faith may speak, organize, educate, and serve.

The chapter's portraits of John Carroll, John England, Orestes Brownson, Tocqueville, and Washington show why American Catholics came to view the Constitution not as a grudging truce, but as fertile ground for faith. Limited government, federalism, property and speech protections, and respect for voluntary associations embody something akin to subsidiarity.

In America, separation of church and state could liberate the Church from political supervision rather than banish it from public life.

Skeptical readers may want more explanation of how courts should distinguish sincere claims from opportunistic ones, or how exemptions should operate when concrete third-party harms are established. Those questions do not defeat Alito's thesis, but they mark the difficult terrain on which it must be applied.

Chapter 10 nevertheless succeeds splendidly. The Religion Clauses are not museum pieces; they are articles of civic peace for a pluralistic nation. Their promise is not that Americans will cease disagreeing about ultimate truths, but that government will neither establish a creed nor punish citizens for exercising their faith within the traditional bounds of public order.

The Gettysburg Address

Chapter 15 is a compact meditation on why the Gettysburg Address endures. Alito places Lincoln's 272 words beside Edward Everett's two-hour oration and lets the contrast speak. Everett gave the crowd what 19th-century convention demanded: classical allusion, elaborate description, and grand rhetoric. Lincoln gave the nation biblical cadence, moral clarity, and a statement of national purpose.

Alito is especially strong on Lincoln's word choice. "Four score and seven" and "brought forth" were not ornamental flourishes. They drew upon the King James Bible, the common linguistic inheritance of Lincoln's audience. Lincoln achieved eloquence without displaying erudition. More importantly, those words framed America not as an accident of geography or power, but as a nation born to test whether self-government rooted in liberty and equality could survive.

The strongest section examines Lincoln's relationship to the Founding. Speaking amid the terrible consequences of a constitutional order that had tolerated slavery, Lincoln might have repudiated the Founders. He did not. He appealed to their principles while acknowledging their failures. Alito rightly describes this as conservative and progressive: conservative because Lincoln sought to preserve the best of the American inheritance, progressive because he summoned the nation to fulfill promises it had not kept.

Alito also emphasizes what Lincoln omitted. He did not blame the South, boast of battlefield progress, attack opponents, or make a conventional case for reelection. On ground consecrated by sacrifice, partisan rhetoric would have been too small. Lincoln transformed a cemetery dedication into a national recommitment.

This is not a historian's excavation, and Alito does not pretend otherwise. It is a judge's close reading of a foundational text. His aim is to recover the argument embedded in the Address: America is exceptional not because it is flawless, but because it remains dedicated to a proposition that judges every generation, including our own.

That theme captures the larger achievement of "So Ordered." Across subjects as varied as statutory interpretation, religious liberty, baseball, and Lincoln, Alito returns to a common idea: institutions endure only when citizens understand the principles beneath them and possess the courage to preserve those principles without resisting every necessary change.

The work of Gettysburg - preserving ordered liberty, widening opportunity, and securing equality under law - remains unfinished. It is still ours.

Samuel A. Alito Jr.'s "So Ordered" is not merely worth reading - it is essential reading for anyone who wants to understand the Constitution, the Supreme Court, and the disciplined judicial temperament required to safeguard the rule of law.

Reprinted from Civitas Outlook, a publication of Civitas Institute

Charles "Cully" Stimson is a senior legal fellow at The Heritage Foundation and the acting director of its Legal Policy Center.

Tyler Durden Thu, 10/15/2026 - 20:15

Shane Gillis Exposes The Narcissism Of Modern Women With A Single Joke

Zero Hedge -

Shane Gillis Exposes The Narcissism Of Modern Women With A Single Joke

Good comedy is generally one part sensationalism, one part truth and one part tragedy.  Often, the tragedy is in the lack of self awareness of the people being made fun of, and lets just say that modern western women are ripe for such ridicule.  No other group in history has enjoyed this level of unfettered privilege and protection.  So much protection, in fact, that you're not even allowed to make jokes about their bad behavior. 

The term "modern woman" largely refers to liberal women in first world countries, and the feminist idealism surrounding these women is truly bizarre.  The political left views them as untouchable pure spirits; the pinnacle of human evolution, the most benevolent and morally superior beings on the planet.  Everything they say is rooted in feelings, therefore everything they say is right.  Logic and reason are considered masculine evils that poison the waters and get in the way of the otherwise perfect feminine perspective. 

Of course, this is complete nonsense.  Liberal women are some of the most selfish, arrogant, petty, degenerate and violent creatures the human species has ever produced; they just express their violence through mob aggression and sabotage rather than direct action.  They prefer to get other people (or the government) to brutalize their enemies on their behalf (cancel culture). 

And the one thing that will make you an enemy of modern women faster that anything else is exposing their narcissism and laughing at their expense.  This is simply not done in a civilized and progressive society.

Comedian Shane Gillis is very familiar with this problem; he's been the target of feminist cancel culture more than a few times.  In 2026 the power of cancel culture is waning and comedy seems to be making a comeback, but that doesn't mean modern women are going to stop clinging to the power they once had.  They continue to look for ways to stifle and suppress honest speech, but all they have to fall back on right now is the old standbys of "shame" and their allies in the mainstream media.  

Gillis' most recent appearance on Saturday Night Live is a good example (a show he was fired from in 2019 because of old podcast clips in which he used naughty words to make fun of liberal candidates like Andrew Yang and Bernie Sanders).  Gillis ripped on modern women going to public gyms in "whore" clothing that makes them look almost naked.  In the process he may have inadvertently touched on the most taboo subject for feminists, which is their demand that women's promiscuity and addiction to attention be socially normalized. 

Men are not allowed to judge anything a woman wears, nor anything she does to feed that addiction.

The world of cellar crowd comedy is typically no-holds-barred and is meant to be offensive in order to cut to the ugly truth of an issue.  This is the kind of comedy America needs once again.  The fact that Gillis has been invited back on a left-leaning production like SNL is a testament to the public demand for scathing humor.  It's undeniable - everyone is tired of Karens trying to ruin our fun.  

In response, liberal women (and their beta male counterparts) are raging across social media while their cohorts in the mainstream media publish endless attacks against Shane Gillis.  Some have tried to connect his jokes to the "Cornell 7" controversy, which is ironic because evidence shows that the Cornell rape claims are completely fabricated by a woman who was seeking to silence negative criticism for her bad behavior.

Half of these women complain that they wear normal clothing when they go to the gym.  Which means, the joke wasn't about them, but they're so oversensitive that they're angry about it anyway.

Other women simply made Gillis' point for him.  Put any of these chicks in a public place 20+ years ago and yes, people would assume they are prostitutes.  At the very least, they should not be mad when men stare because that's the real reason why they wear this clothing, they just don't want to admit it. 

The exercise in vanity that the gym has become for women is renowned, but it's merely an extension of the problem of social media and its ability to twist and destroy the female mind.  If men are addicted to porn, then women are addicted to attention, and social media has become their go-to source for that sweet, sweet narcissist nectar. 

Half the internet has been making jokes about modern women at the gym for the past few years - Specifically their habit of wearing the most revealing skin-tight clothing and waiting for men to glance in their direction so they can put those men on blast.  Meanwhile, these same women are simultaneously humble bragging about how men can't help but stare at them at the gym.  It's a bizarre ritual in which feminists act out their victimhood fantasies while also fulfilling their secret and desperate need for the male gaze.   

Bottom line, ladies?  If you look naked, men are going to stare at you, and there's nothing you can do about it.  If you throw a fit and pretend you are pure as the driven snow, then men are going to make fun of you, and there's nothing you can do about it.  You can't have your cake and eat it too when you put your cake out there for everyone to see.

As for the issue of comedy being akin to "assault", no one cares about your feelings.  No one cares if a joke offends you.  Those days are long gone.  You heavily abused your cancel culture powers when you had them and now society is turning on you.  Get ready, because the ridicule is going to get a lot worse, and you deserve it.

Tyler Durden Thu, 10/15/2026 - 19:50

These Are The Top Races To Watch This Midterm

Zero Hedge -

These Are The Top Races To Watch This Midterm

Authored by Joseph Lord via The Epoch Times,

Voters' decisions in the upcoming November midterms are set to reshape the balance of Washington and beyond. Democrats are seeking to capitalize on favorability ratings that fell below 40 percent for Republicans in the latest RealClearPolitics summary of polling.

That's expected for the sixth year of a president's tenure, called the "six-year itch," a time when the president's party has historically lost seats in the House. With the House already closely divided, observers expect Democrats to reclaim the lower chamber this year. However, Democrats' new margins in the House could also be slim, as a flurry of mid-decade redistricting has panned out with a slight edge for Republicans.

The Senate is seen as a more hotly contested battleground. Currently, Republicans hold 53 seats to Democrats' 47. Just four pick-ups for Democrats - who are leading or holding their own in red states like Iowa and Ohio - would flip the balance of the upper chamber.

It comes also as several progressive and outsider Democrats - some of whom have open ties to the Democratic Socialists of America or democratic socialist ideas - have made headlines in races across the nation. Republicans have argued that Democrats are shifting too far left for the average American.
According to polling by Pew Research, Americans' top concern at present is the economy, and by a wide margin. That poll found that economic issues were the driving political force this cycle for 29 percent of Americans. Data centers are also a top priority for voters as the primary season comes to a close.

Here are the top elections and candidates to watch this cycle.

Senate
Georgia

In Georgia, Republicans are again seeking to flip one of the state's two Senate seats, which have been held by Democrats since 2020.

Sen. Jon Ossoff (D-Ga.), elected to his first six-year term in a January 2021 runoff, is up for reelection. Republicans selected Rep. Mike Collins (R-Ga.) to take him on.

Polls taken in the state have shown that Ossoff is favored to hold the seat, leading Collins in almost every poll so far.

In 2024, President Donald Trump won Georgia by around 2.2 percentage points - Republicans' lowest margins of victory in the Peach State since 1996.

Maine

In Maine, incumbent Sen. Susan Collins (R-Me.) will take on former state Senate President Troy Jackson for one of the year's top Senate fights.

Collins, a long-serving political juggernaut in the state, ran unopposed for her party's nomination.

Maine Democrats selected Jackson on July 25 as their party's nominee to challenge Collins, taking over after the previous nominee, Graham Platner dropped out of the race.

Platner, a progressive, was one of the first candidates to capture the populist mood of the national Democratic base, building a campaign that championed pro-working class policies. But after accusations of sexual and other misconduct emerged, which he denied, Platner ultimately departed the race.

However, Collins still faces a difficult fight to hold the seat, with polls showing she's running behind either Democrat in most polls conducted since March.

Michigan

Michigan's Senate race features a showdown between an establishment Republican and a progressive outsider after Democratic Sen. Gary Peters declined to run for reelection.

Democratic nominee Abdul El-Sayed, won his primary over Rep. Haley Stevens (D-Mich.) by a single point. He faced more than $60 million in outside spending in support of Stevens.

El-Sayed will take on former Rep. Mike Rogers (R-Mich.) in the race.

Currently, he leads in the polls by around 4 percent.

Analysts say El-Sayed's campaign reflects the outsider approach and populist energy seen among democratic socialist-aligned candidates.

Between 2017 and 2020, El-Sayed spoke at several events hosted by the Democratic Socialists of America.

But today, El-Sayed says he's distanced himself from the group - and the democratic socialist label - describing himself as a capitalist.

Rogers ran unopposed during his primary with Trump's endorsement.

Alaska

While Alaska is Republican-leaning, the Senate race between incumbent GOP Sen. Dan Sullivan and former Democratic Rep. Mary Peltola is proving competitive.

Sullivan has served in the Senate since 2015, while Peltola served in the U.S. House of Representatives between September 2022 and January 2025.

Because Peltola has shown viability in statewide elections in the single-district state, the Last Frontier is a top target for Democrats this year.

The ranked-choice race is complicated by the presence of a candidate on the ballot who shares a name with incumbent senator Dan Sullivan. The challenger, also named Dan Sullivan and also Republican, has insisted he's serious about running, despite allegations that he's just trying to divert votes away from the senator.

In the most recent poll taken of the race, Sullivan leads with 47 percent to Peltola's 46 percent. However, some other polls show Peltola in the lead.

Iowa

Iowa is also home to a competitive Senate race this year, this time between GOP Rep. Ashley Hinson and Democratic state Rep. Josh Turek, after Sen. Joni Ernst declined to run for a third term.

Like others, the state had been seen as reliably Republican over the past several cycles, since President Donald Trump first won the state back in 2016 with a nearly 10-point victory.

However, it was long known as a quintessential swing state.

As recently as 2012, the state drew intense national attention as a battleground. Now, some polls are showing that Iowa is in for a tighter Senate race this year, a pattern also being seen in neighboring Ohio.

Hinson has led in five polls conducted of the race since April, while Turek has led in four.

Cook Political Report recently moved the race from lean Republican to a toss up, reflecting the closely split nature of the race.

Ohio

Ohio is another key Senate battleground this year, with former Democratic Sen. Sherrod Brown set for a November fight against incumbent GOP Sen. Jon Husted.

Brown was unseated just two years ago in the 2024 election, losing to Sen. Bernie Moreno (R-Ohio) by around 3.6 percent - far outrunning Trump and Vice President JD Vance's approximately 11 point victory that year.

Without the benefit of the "Trump effect," describing Trump's impact on close down-ballot races during presidential election years, Husted faces a race against a politically powerful opponent with deep name recognition in the state.

Husted was appointed by Gov. Mike DeWine to fill the seat held by Vance. The winner will serve out the final two years of Vance's term.

Texas

In Texas, state Attorney General Ken Paxton is set for a heated November matchup against Democratic state Rep. James Talarico in one of the cycle's most-watched races.

Paxton won a contentious primary against incumbent Sen. John Cornyn (R-Texas) with the assistance of a strong endorsement from Trump.

The expensive and personal primary race centered heavily on Paxton's past controversies, including his impeachment for alleged bribery, whistleblower retaliation, and abuse of office.

In 2023, Paxton was impeached by the Texas House on 20 articles in a 121 - 23 vote and subsequently acquitted on all counts.

Talarico, a Presbyterian seminarian, has built a campaign based around his Christian values as a seminarian and on his track record as a state legislator.

Talarico has led in 15 out of the 16 polls of the race conducted since July, with Paxton leading in a poll conducted by Emerson College.

North Carolina

In North Carolina, former Republican National Committee Chairman Michael Whatley is set to take on former Gov. Roy Cooper in one of the 2026 cycle's most crucial matchups.

The two are fighting to replace outgoing Sen. Thom Tillis (R-N.C.) - an administration critic who announced last year that he wouldn't seek reelection - after winning their nominations in March.

Trump has loomed over the election in the state.

Whatley, appointed to lead the Republican National Committee on Trump's recommendation, has emphasized his loyalty, while Cooper has accused Whatley of being "anointed" by Trump.

While Republicans have held an advantage in the battleground state for nearly two decades, polls have shown that Cooper favored this cycle, leading in every poll of the race conducted since July 2025. In a sign that Republicans see the race as a potential lost cause, the Senate Leadership Fund has withdrawn funding from North Carolina, instead directing it to an unexpectedly close Senate race in Kansas. [delete]

Kansas

In Kansas, polls show Sen. Roger Marshall (R-Kansas) locked in a dead heat with pastor Adam Hamilton.

Hamilton is a United Methodist megachurch pastor and author, co-founding the Kansas-based Church of the Resurrection. Marshall is a freshman senator and an obstetrician-gynecologist, first elected in 2020 after beating out a crowded primary field.

This year, Marshall has been the subject of controversy in the state after The New York Times reported that he had sued hundreds of his former patients, leading to 81 arrests due to missed court dates.

While Marshall led in the first poll taken of the race released on Sept. 11, every poll since has shown him either tied with or running behind Hamilton.

In the 2020 election, which he won by around 12 percent, there were some warning signs: Shawnee County and Riley County backed the Democrat for the first time since the 1970s, while Johnson County voted Democratic for the first time in the state's history. President Joe Biden flipped the same counties in that election.

The race was originally rated lean Republican by Cook Political Report, which now rates it to be a toss-up.

Nebraska

In Nebraska, independent candidate Dan Osborn - who made national news following his close fight against Sen. Deb Fischer (R-Neb.) in 2024 - is making another bid for the office.

In that race, Osborn lost to Fischer by around 7 points after Democrats declined to make a nomination in the race. This year, Democratic nominee Cindy Burbank has dropped out of the race to make way for Osborn, similar to the situation seen in 2024.

This year, he's running against the incumbent Sen. Pete Ricketts (R-Neb.), and polls have shown a tight race. In surveys taken in September and October, Ricketts led by 4 and 5 points, respectively. Osborn led by around the same margin in polls taken in May and September.

Republicans maintain a structural advantage in the state. Although 53 percent of registered Nebraska voters live in rural areas, the urban and suburban population in Nebraska is reliably Republican - but has potential to swing in line with an anti-Republican national environment.

Omaha, Nebraska, is a crucial decision-maker in the race, as its population has trended away from Republicans in recent cycles, voting for Vice President Kamala Harris in 2024.

House Texas 34th Congressional District
In Texas' 34th Congressional District, representing one of the Lone Star State's most evenly-split seats, incumbent Rep. Vicente Gonzalez (D-Texas) is seeking to hold off a challenge from Republicans, who see the House district as a potential pickup opportunity.

The seat was among those redrawn by the state legislature last year at the request of the White House.

In the primary, Trump-endorsed candidate Eric Flores, a former federal prosecutor, defeated former Rep. Mayra Flores (R-Texas) for the Republican nod.

In 2022, Mayra Flores made headlines with a special election win in District 34 before its map was redrawn. But after she lost to Gonzalez in 2022 and again in 2024, the party is making a fresh bid with Eric Flores.

The Cook Political Report rates the race a toss-up.

North Carolina 1st Congressional District

In North Carolina's First Congressional District, Republicans selected retired Army Col. Laurie Buckhout as their nominee on March 3, setting up a November rematch against incumbent Rep. Don Davis (D-N.C.).

The district was altered to favor Republicans, although analysts still consider the seat competitive.

Davis won a second term in 2024 by less than 2 percent, becoming one of 13 House Democrats to win elections in districts won by Trump. He's been critical of the redrawing of his district, which will make reelection a tougher challenge this cycle.

Ohio House Races

Ohio will also host a handful of key House races that will affect control of Congress next year.

In the 7th Congressional District, incumbent Republican Rep. Max Miller faces a tough path to reelection amid abuse allegations by his ex-wife Emily Moreno, which Miller has denied.

Miller's Democratic opponent, union ironworker and Brook Park city councilman Brian Poindexter, has been endorsed by Sen. Bernie Sanders (I-Vt.).

Over in the 9th Congressional District, incumbent Democratic Rep. Marcy Kaptur hopes to hold onto her seat in a rematch from 2024 with former state Rep. Derek Merrin.

Kaptur has been in Congress since 1983, while Merrin is a former member of the Ohio House of Representatives and has touted his record in the state legislature.

Nebraska 2nd Congressional District

Democrat Denise Powell will face Republican nominee Brinker Harding in Nebraska's 2nd Congressional District as both parties continue to fight for the seat that's come to be known as Nebraska's "Blue Dot."

Since 2008, the Omaha-based, urban district has swung between the two parties, but has increasingly favored Democrats in recent cycles.

The seat is currently represented by Rep. Don Bacon (R-Neb.), who had managed to keep the trust of the district - which backed Harris in 2024 - even as it has otherwise swung toward Democrats.

The Cook Political Report rates the race as leaning toward Democrats. Powell would be Nebraska's only Democrat in Congress if she wins.

Pennsylvania House Races

Several critical races are being held in Pennsylvania, one of the most narrowly-split national battlegrounds.

This year, Pennsylvania voters - who backed Trump in 2024 - are heavily driven by economic concerns.

According to one recent poll by Franklin & Marshall College, only 14 percent of voters in the state say they're better off financially than they were a year ago. Nearly half - 44 percent - say they're worse off.

This year, the most closely-contested races in the state have Republicans playing defense.

Pennsylvania's Seventh Congressional District is represented by freshman Rep. Ryan Mackenzie (R-Pa.), who was first elected to Congress in 2024.

The district is a top target for Democrats. Firefighter union leader Bob Brooks, running with the endorsement of Pennsylvania Gov. Josh Shapiro, is their nominee.

Pennsylvania's Eighth Congressional District is represented by freshman Rep. Rob Bresnahan (R-Pa.), who was first elected to Congress in 2024.

Scranton Mayor Paige Cognetti will take him on in the swing district.

Pennsylvania's 10th Congressional District is represented by Rep. Scott Perry (R-Pa.), who has been in Congress for nearly 14 years.

Former news anchor Janelle Stelson, a Democrat, is running again for the seat after a 2024 loss.

Iowa 1st Congressional District

Several key House races will also be held in Iowa.

In the 1st Congressional District, incumbent Republican Rep. Mariannette Miller-Meeks is defending her seat against former Democratic state Rep. Christina Bohannan.

The seat featured one of the closest House race of 2024, with Miller-Meeks ultimately defeating the Democrat by just 799 votes despite Trump's 13-point win in the statewide presidential contest.

Iowa 3rd Congressional District

In the 3rd Congressional District, incumbent Republican Rep. Zach Nunn looks to be reelected to a third term.

He's facing Democratic state Sen. Sarah Trone Garriott.

Nunn led by 6 points in the only independent public poll of the race so far, conducted in March.

Virginia 2nd Congressional District

Incumbent Republican Rep. Jen Kiggans is seeking a third term, but faces a tougher fight this year with former Democratic Rep. Elaine Luria, who Kiggans defeated in 2022.

The Virginia Beach-based district is known for a strong military and veteran presence and a moderate approach to politics.

In 2024, Kiggans won reelection by 3.8 percentage points, facing a lesser known challenger at the time.

Washington 3rd Congressional District

Encompassing the southernmost portion of Western Washington state, the Third Congressional District is represented by Rep. Marie Gluesenkamp Perez (D-Wash.).

Washington state Senate GOP leader John Braun is aiming to unseat the moderate Democrat this year.

The seat has historically favored Republicans, although Gluesenkamp Perez's centrist brand has been popular in the region.

Trump won the district by 3 percentage points in 2024.

Wisconsin 3rd Congressional District

Encompassing western and southwestern Wisconsin, this district has been represented by Rep. Derrick Van Orden (R-Wis.) since 2023.

Democrats selected small business owner and waitress Rebecca Cooke as their nominee.

Trump won the district by 8 percentage points in 2024, but the Cook Political Report rates the match a pure toss-up.

California House Races

California will also host several key House races this year.

California's 13th Congressional District is represented by freshman Rep. Adam Gray (D-Calif.), who was first elected to the seat in 2024.

He's facing Kevin Lincoln II, the former mayor of Stockton, California.

California's 22nd Congressional District is represented by Rep. David Valadao (R-Calif.), who has been in Congress for a decade.

Randy Villegas, a teacher and business owner, is Democrats' pick.

Finally, retiring Rep. Darrell Issa's (R-Calif.) 48th Congressional District seat is a critical target for Democrats.

The district was redrawn as part of California's new congressional map that came about in response to redistricting in Texas.

San Diego City Councilwoman Marni von Wilpert, a Democrat, is facing San Diego County Board of Supervisors member Jim Desmond, a Republican, in the seat rated "Lean Democrat" by Cook Political Report.

South Carolina 1st Congressional District

In South Carolina's only swing district, Democrats are hoping for a repeat of 2018, when former Rep. Joe Cunningham (D-S.C.) pulled off an upset win in the Republican-leaning, Charleston-based district.

This year, incumbent Rep. Nancy Mace (R-S.C.) won't be on the ballot after she made an unsuccessful bid for South Carolina governor.

Instead, Democrat Nancy Lacore, a retired Navy vice admiral, will take on Republican Jenny Costa Honeycutt. Both candidates won their nominations in runoff primary elections.

Maine 2nd Congressional District

In Maine's Republican-leaning second congressional district, the race to replace outgoing Rep. Jared Golden (D-Maine) is a top priority for both parties.

Maine state auditor Matthew Dunlap will face former Gov. Paul LePage, who was endorsed by President Donald Trump.

Republicans hope LePage will be able to flip the seat, which houses a district that voted for Trump in 2024.

New York House Races

Key House races are also set to be held in New York.

In the Long Island-based 3rd Congressional District, incumbent Democratic Rep. Tom Suozzi (D-N.Y.) faces former state Assemblyman Mike LiPetri Jr., a Republican.

Suozzi has decried Trump tariffs and cuts to Medicaid.

In the 4th Congressional District, also located on Long Island, incumbent Democratic Rep. Laura Gillen looks to be reelected to a second term as she faces Republican Jeanine Driscoll.

In the 17th Congressional District, incumbent Republican Rep. Mike Lawler faces Democrat Cait Conley, a special ops combat veteran.

The race for Lawler's seat is a top priority for Democrats.

In the 19th Congressional District, incumbent Democratic Rep. Josh Riley is running for a second term, while Republican state Sen. Peter Oberacker looks to unseat him.

New Jersey 7th Congressional District

In the 7th Congressional District, incumbent Republican Rep. Tom Kean Jr. is seeking a third term, while Democrat Rebecca Bennett looks to unseat him.

Kean, who has represented the district since 2023, came under fire for his absence from Congress between March and June. Upon his return, he said he was dealing with a diagnosis of depression for which he was hospitalized. He has missed more than 100 House votes.

Arizona House Races

Rep. David Schweikert (R-Ariz.) is retiring after serving in Congress since 2011, leaving his highly competitive 1st Congressional District seat open.

Democrats ultimately nominated former Arizona House of Representatives Rep. Amish Shah, while Republicans nominated former NFL kicker and analyst Jay Feely.

Arizona's 6th Congressional District, meanwhile, is represented by Rep. Juan Ciscomani (R-Ariz.), who has been in Congress since 2023.

Democrats nominated JoAnna Mendoza, a Marine veteran whose post-military career has centered around providing assistance and outreach services to veterans.

Florida 25th Congressional District

Rep. Jared Moskowitz (D-Fla.) won renomination to his 25th Congressional District U.S. House seat on Aug. 18, defeating Oliver Larkin, a union organizer endorsed by the Democratic Socialists of America.

Moskowitz currently represents the 23rd District. He ran in the 25th after Florida's Republican-led legislature redrew the state's congressional map this year at the call of Republican Gov. Ron DeSantis.

Former Boca Raton Mayor Scott Singer won the Republican nomination.

The Cook Political Report rates the match a toss-up.

Michigan 7th Congressional District

Incumbent Republican Rep. Tom Barrett faces progressive activist and Democrat William Lawrence.

Barrett was first elected in 2024.

He has broken with his party over the war in Iran as he has joined a few other Republicans along with Democrats in favor of war powers resolutions related to the conflict.

Gubernatorial Georgia

Former Atlanta Mayor Keisha Lance Bottoms looks to flip this seat to the Democrats, while billionaire Republican Rick Jackson seeks to keep it in Republican hands.

Bottoms' platform consists of lowering healthcare costs and building more housing.

Jackson is running on a promise to freeze property taxes and to reduce and then eliminate the state income tax.

The winner will succeed Gov. Brian Kemp, who was ineligible to run for reelection.

Iowa

Republicans are looking to hold this seat with farmer and businessman Zach Lahn, while Democrats look to win it back for the first time since 2011.

Lahn is a proponent of the Make America Healthy Again movement, running on a promise to fight what he said is a "cancer crisis" in Iowa.

The Democratic nominee, Rob Sand, is the state auditor.

Sand has led in every poll since June.

The winner will succeed Gov. Kim Reynolds, who declined to run for a third term.

Nevada

Gov. Joe Lombardo, a Republican, is up for reelection.

He has touted his record as governor during the campaign, referencing his work to expand state savings, cut regulation, and boost employment.

Lombardo's Democratic opponent is Nevada Attorney General Aaron Ford. He has promised affordable housing and addressing predatory practices by healthcare agents.

Lombardo, a former sheriff, was first elected in 2022.

Ohio

Just as Ohio has drawn national attention to its House and Senate races, observers are also paying attention to its gubernatorial race this year.

Republican entrepreneur Vivek Ramaswamy is running against Democrat Amy Acton, the state's former health director.

Earlier this year, the Cook Political Report shifted the race's rating to toss up, citing Acton's polling leads and ties over the race despite Ramaswamy's financial edge.

Arizona

In Arizona, Gov. Katie Hobbs faces reelection, fielding a challenge from Rep. Andy Biggs (R-Ariz.).

National issues - affordability, the impacts of Republican party-line cuts to Medicare and Medicaid, and data centers - are factors in the race.

Meanwhile, local issues related to water access for Phoenix - a rapidly growing metropolis situated in the desert - have also been key factors in the race.

Hobbs has led Biggs by nearly a double-digit margin in every poll of the race conducted in 2026.

Michigan

Republicans have been looking to take back the Michigan gubernatorial mansion since they lost the seat in 2019.

The Republican nominee, Rep. John James (R-Mich.), has campaigned on implementing a parental bill of rights and enabling school choice.

Michigan Secretary of State Jocelyn Benson is the Democrat facing James, running on a promise to increase the affordability of housing and other goods.

The winner will succeed Gov. Gretchen Whitmer, who is term-limited.

Kansas

Republican Ty Masterson will face Democrat Cindy Holscher in the closely-watched fight for the governor's mansion of Kansas.

Masterson, who was endorsed by Trump, won the crowded Republican primary on Aug. 4 in a landslide. Holscher, a state senator, came out on top in the Democratic race.

Masterson, who has been the president of the Kansas Senate since 2021, says he wants to cut taxes, bring jobs to Kansas, and raise pay for teachers, while Holscher is running on a platform to lower the cost of living.

Though Kansas is known as a red state at the federal level, contests have been closer on the state level. The mansion is currently occupied by Gov. Laura Kelly, a Democrat.

Tyler Durden Thu, 10/15/2026 - 19:25

Pages