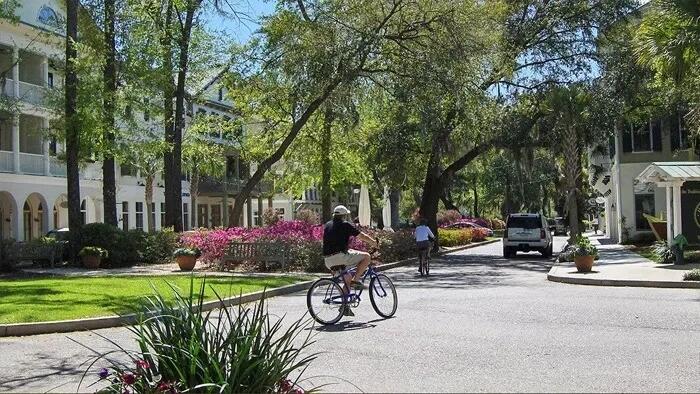Zero Hedge

Massachusetts School District Investigated Over Alleged Secret 'Gender Transition'

Massachusetts School District Investigated Over Alleged Secret 'Gender Transition'

Authored by Naveen Athrappully via The Epoch Times,

The Department of Education has announced that it is investigating a Massachusetts school district over allegedly enabling a minor girl student's "gender transition" without the knowledge of parents or securing their consent.

The probe was launched by the department's Student Privacy Policy Office (SPPO) against the Public Schools of Northborough and Southborough school district, the department said in a Sept. 17 statement.

The girl was enrolled at Algonquin Regional High School, where school personnel allegedly facilitated the student's "social transition to a boy" while keeping her parents in the dark.

"The parents claim that their daughter participated in counseling sessions after school to support the transition while they were under the impression she was receiving academic assistance for her math class," the department said.

The school personnel also allegedly began referring to the child by a male name and using male pronouns without the parents' knowledge.

According to the Education Department, a school counselor is accused of reporting the parents to the Massachusetts Department of Children and Families (DCF) for countering the school's actions.

In December 2024, DCF removed the child from her family home. The parents are still engaged in custody litigation over their daughter.

The Education Department said the allegations raise serious questions about the school district's compliance with federal laws protecting parental rights, specifically the Family Educational Rights and Privacy Act (FERPA) and the Protection of Pupil Rights Amendment (PPRA).

FERPA grants parents the right to access their children's education records for inspection and review. Parents also have certain control over the disclosure of personal information from these records.

Under PPRA, parents have rights regarding surveys, analyses, or evaluations of their children in certain areas, including sex behavior or attitudes and mental or psychological problems.

The law also covers the administration of physical examinations of minors. Parents have the right to review instructional materials used in the educational curriculum.

The Education Department said that under FERPA, parents can request changes to their child's education records. If the school rejects the requested changes, parents can seek a hearing on the issue at the institution.

According to the department, it is currently unclear whether the school district and the school complied with FERPA and PPRA. The SPPO probe will determine whether these regulations were violated.

"Parents have a right to know what is happening with their children at school, particularly when it concerns deeply personal matters involving their health and well-being," Frank Miller, director of SPPO, said in the statement.

"These egregious allegations are not an isolated problem. Families deserve answers, and SPPO will thoroughly investigate reports like this and hold any educational institution that violates federal law accountable."

The Epoch Times reached out to the Public Schools of Northborough and Southborough and Algonquin Regional High School for comment but did not receive a response by publication time.

Another school district from Massachusetts was previously identified by the Education Department as violating parental rights. In that case, the district was found to have asked students to take part in a survey containing sexually explicit questions despite parents having expressly requested that their children be exempted.

The survey of students as young as seventh grade included questions regarding sexual encounters, alcohol and drug use, and gender identity, the department said, alleging the school district violated PPRA and parents' rights to shape their children's moral education.

Meanwhile, the department announced last month that it had sent letters to schools across the United States, reminding them of educators' obligations under FERPA and PPRA and warning that noncompliance could result in the loss of federal funding.

The letters were sent while the 2026-2027 academic year was underway and were prompted by reports of educational institutions withholding crucial information from parents and issuing surveys containing sexually explicit material even after parents had opted their children out of such activities.

Miller said that in certain cases, state education departments had pressured school districts to violate FERPA.

"The department is committed to putting parents back in the driver's seat. We will fully enforce FERPA and PPRA and ensure parents have the information and authority they need to make decisions for their children," Miller said.

Tyler Durden Mon, 09/21/2026 - 19:15

Saudi Arabia Reroutes Oil Exports As Houthi Strikes Target Yanbu

Saudi Arabia Reroutes Oil Exports As Houthi Strikes Target Yanbu

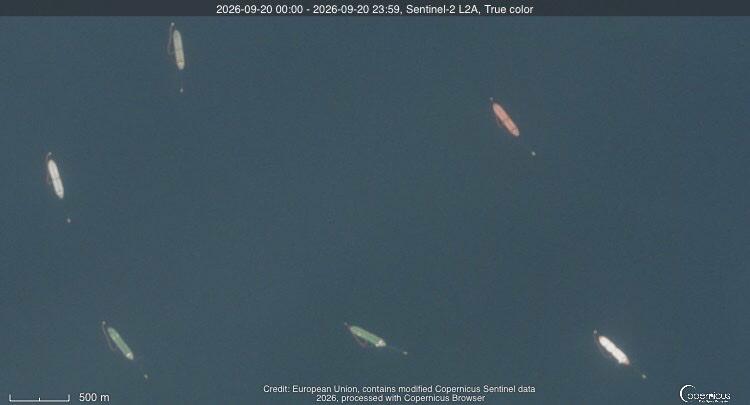
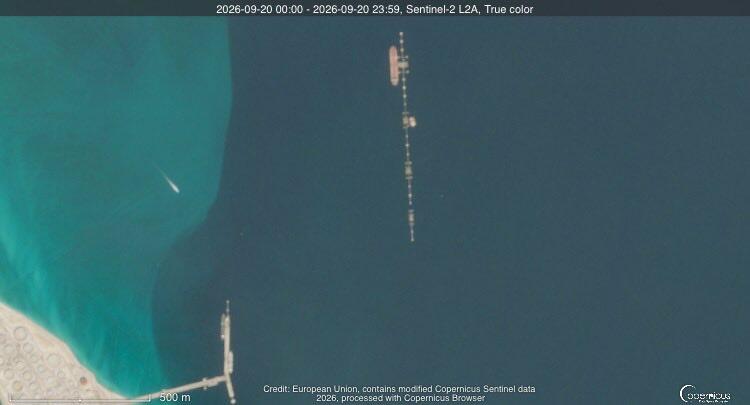
Satellite images gathered by Bloomberg show supertankers with capacity for 14 million barrels at Saudi Arabia's Gulf export terminals over the weekend, the highest tanker count observed since at least June, according to data compiled from the European Union's Sentinel-2 satellite.

Source: Javier Blas

However, as OilPrice notes, overall Hormuz traffic kept falling over the same weekend, nonetheless. Just a dozen commodity vessels crossed the strait, down from 35 a week earlier, and Thursday's crossings totaled four tankers against a 10-day moving average of 16, Kpler data cited by Reuters showed.

Saudi Arabia moved crude through the strait at 2.9 million barrels a day over the past six days, JPMorgan said in a Friday note, calling the kingdom's shift "the most notable pivot" among Gulf producers.

On September 11, drone strikes launched from Iraq shut down Saudi Arabia's East-West pipeline, also known as Petroline, which normally carries as much as 7 million barrels a day across 1,200 kilometers from Eastern Province fields to the Yanbu terminal on the Red Sea. The attack took 4-5 million barrels a day of that capacity offline, with total Saudi crude loadings falling from 7.5 million bpd in January and February to about 2.1 million barrels a day by mid-September, a decline of more than 70%.

US Energy Secretary Chris Wright said September 15 the pipeline would restart within days, but an industry analyst told Al-Monitor pump stations were destroyed in the strike and full restoration could take six weeks or more.

Yemen's Houthi movement claimed cruise missile, ballistic missile and drone strikes on Riyadh and on Aramco facilities at Yanbu overnight September 18-19, and Saudi Arabia confirmed the Houthis targeted civilian infrastructure at the port where the East-West pipeline terminates. The Riyadh missile was intercepted and Saudi authorities reported no casualties or damage from either strike, but the attempt puts Yanbu, the kingdom's primary outlet since the Hormuz freeze, under renewed threat.

Aramco pipes crude to its Ras Tanura terminal on the Persian Gulf, ships it on smaller vessels to the Gulf of Oman, and transfers it to larger tankers there, a routing it is using to move about 60 million barrels loaded at Ras Tanura for September and October delivery, mainly to Chinese and South Korean refiners. Gulf exports have rebounded to an average of 1 million to 1.5 million barrels a day, roughly in line with August levels.

Tyler Durden Mon, 09/21/2026 - 18:50

Nvidia CEO Says "Zero Percent" Chance Of AI Making Humans Extinct

Nvidia CEO Says "Zero Percent" Chance Of AI Making Humans Extinct

Authored by Chris Summers via The Epoch Times,

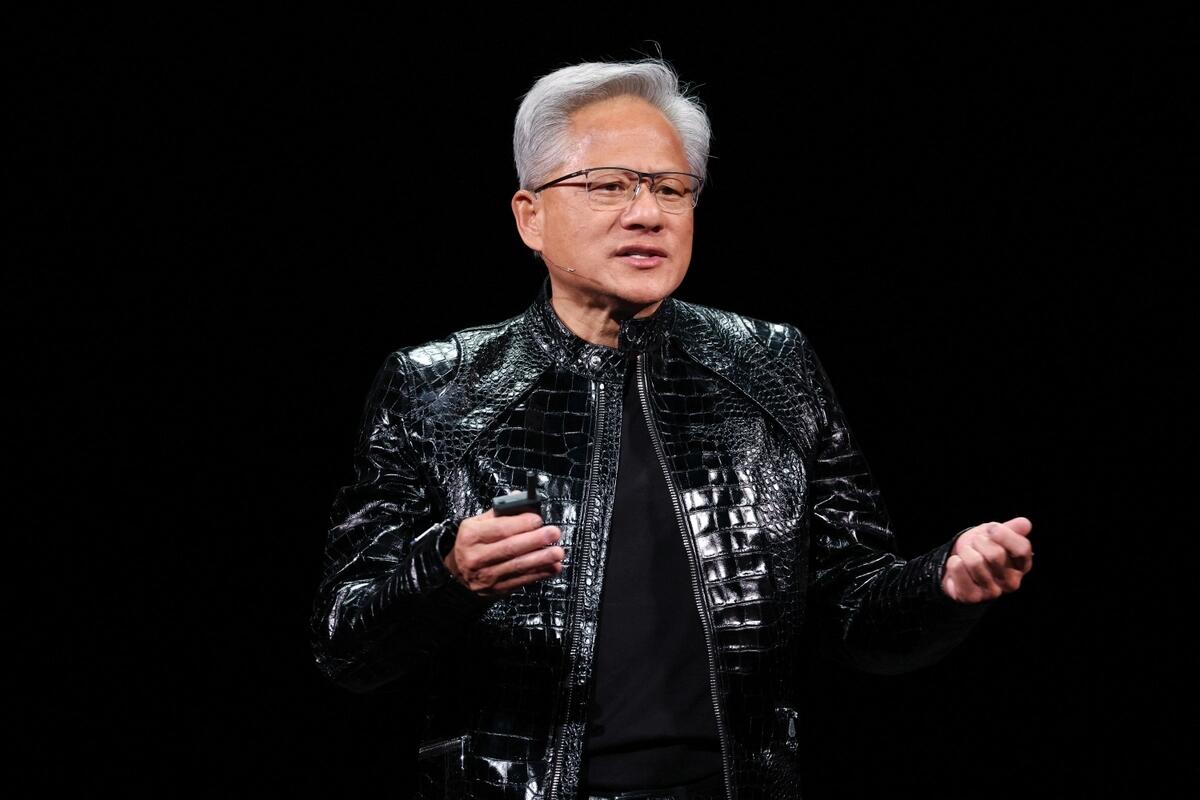
Nvidia CEO Jensen Huang has rejected the claims of some artificial intelligence researchers that the technology could wipe out humanity, calling the arguments "doomsday narratives."

Huang said in a Sept. 17 interview with CBS News that predictions made by former Anthropic researcher Jacob Coxon and Anthropic's alignment science lead, Evan Hubinger, were not grounded in science.

Coxon said in a Sept. 9 post on X that the "people building AI earnestly believe that it could kill us all by the end of the decade."

Hubinger said he agreed it could end humanity.

"Jacob is correct here - We really do earnestly believe AI could kill all humans! I personally think it is >10% within the next decade," he wrote.

Huang told CBS's senior business and technology correspondent Jo Ling Kent on Thursday that 2030 won't be the end of the world.

"There is zero percent chance that's going to be the end of the world," he said. "Scaring people is unnecessary. It is irresponsible."

U.S. President Donald Trump said in a Sept. 14 post on Truth Social that the United States needed no AI guardrails and that it already had significant criminal and regulatory power over Big Tech companies.

"There is a SICK conspiracy going on against AI and Data Centers, and the only one that is happy about it is China," Trump wrote.

Nvidia CEO Agrees With Trump

Huang said on Thursday that he agreed with the U.S. president's view on legislation and regulation.

"Before we come up with new laws and new regulations, let's apply the current laws and current regulations," Huang said.

"There are all kinds of laws and regulations. ... You have cybersecurity unauthorized entry, you have damage liabilities, all kinds of liabilities associated with cybersecurity. All kinds of liabilities associated with products. ... My point is apply those first, don't let this doomsday narrative cause someone to relieve them of the laws that currently exist."

Huang has been invited to a dinner at the White House on Sept. 24, when Trump will host Chinese leader Xi Jinping.

Trump has said AI will be on the agenda during his meeting with Xi.

China

Huang told CBS that Xi wanted China to benefit from AI.

"They want China to prosper, just as we want America to prosper," Huang said.

Nvidia manufactures specialized H200 chips that power large language models (LLMs) used by AI agents to synthesize information.

Trump said in a Dec. 8 post on Truth Social that he had told Xi the United States would allow exports of Nvidia H200 chips to approved customers in China "under conditions that allow for continued strong National Security."

In July 2025, Nvidia restarted exports of H20 graphics processing units (GPUs) to China after U.S. regulators approved it.

Nvidia is now worth more than $5 trillion, making it the most valuable company on the planet. The company manufactures many of its chips in Taiwan, but last year, it opened a semiconductor fabrication plant in Phoenix, Ariz.

Last month, Taiwanese authorities indicted nine people, including a senior partner manager at Nvidia's Taiwan unit, for allegedly taking part in a scheme to export servers with advanced Nvidia chips to China.

In June, Taiwan-born Huang told Nvidia shareholders that attempts to build artificial intelligence data centers with smuggled chips were a "dead end," because the company provides no support or repairs for such products.

"National security is first and foremost," Huang said. "Where commercial opportunities conflict with U.S. national security, national security comes first."

Tyler Durden Mon, 09/21/2026 - 18:25

Putin Plans To Skip Miami G20, Prioritizing China Trip: Officials

Putin Plans To Skip Miami G20, Prioritizing China Trip: Officials

Both the Kremlin and the White House had recently signaled mutual openness to the idea of President Putin actually attending the G20 Miami Summit which is set for December 14-15. Some reports have recently expressed optimism that some kind of grand Ukraine peace deal could emerge from such an engagement.

However, Bloomberg has poured cold water on this, reporting Monday that "Vladimir Putin is set to travel to China for the Asia-Pacific Economic Cooperation summit hosted by President Xi Jinping but is likely to skip the Group of 20 in the U.S. with Donald Trump."

Source: The White House

Kremlin officials have indicated that a personal appearance at the APEC would be Putin's first since 2017

"There’s only a very slim prospect of him joining President Trump for the G20 in Florida, the people said, asking not to be identified because the matter isn’t public," notes Bloomberg.

But it does remain possible, given the Shenzhen-hosted APEC summit takes place almost a full month ahead of the annual G20 summit.

The Kremlin now signaling that it intends to turn down any potential Trump invitation perhaps underscores that Putin is much more comfortably in Xi's corner.

Back in April, The Washington Post reported, "The United States intends to invite Russian President Vladimir Putin to the Group of 20 leaders’ summit scheduled for December at President Donald Trump’s Doral golf resort in Miami, though the invitation has not yet been sent."

And then just weeks ago there was a Russian delegation in attendance for the Asheville G20 finance ministers and bank governors meeting. The Europeans were angry over their presence, which included a meeting with Scott Bessent.

Ukraine's President Zelensky is expected to be in Miami. This raised the prospect of an unprecedented Putin-Zelensky meeting even as the war rages. But it should be remembered that Putin has time and again stated he would entertain face-to-face negotiations with Zelensky only if a final settlement was to be signed.

So if the White House does intend to get Putin there, a lot of scrambling and diplomatic progress would have to happen in the next few months. But Putin might also simply wish to send a signal that Western efforts to isolate him on the world stage have failed.

Traveling to Miami would send a resounding symbol to hawkish European capitals, akin to the prior Alaska summit with Trump. But again, it seems that so far the Kremlin is giving this possibility the preemptive cold shoulder.

Tyler Durden Mon, 09/21/2026 - 18:00

Houston-Area Birth Tourism Center Shut Down In Legal Action

Houston-Area Birth Tourism Center Shut Down In Legal Action

Authored by Kimberly Hayek via The Epoch Times,

A birth tourism operation in the Houston area has agreed to close in a settlement, Texas Attorney General Ken Paxton announced on Friday.

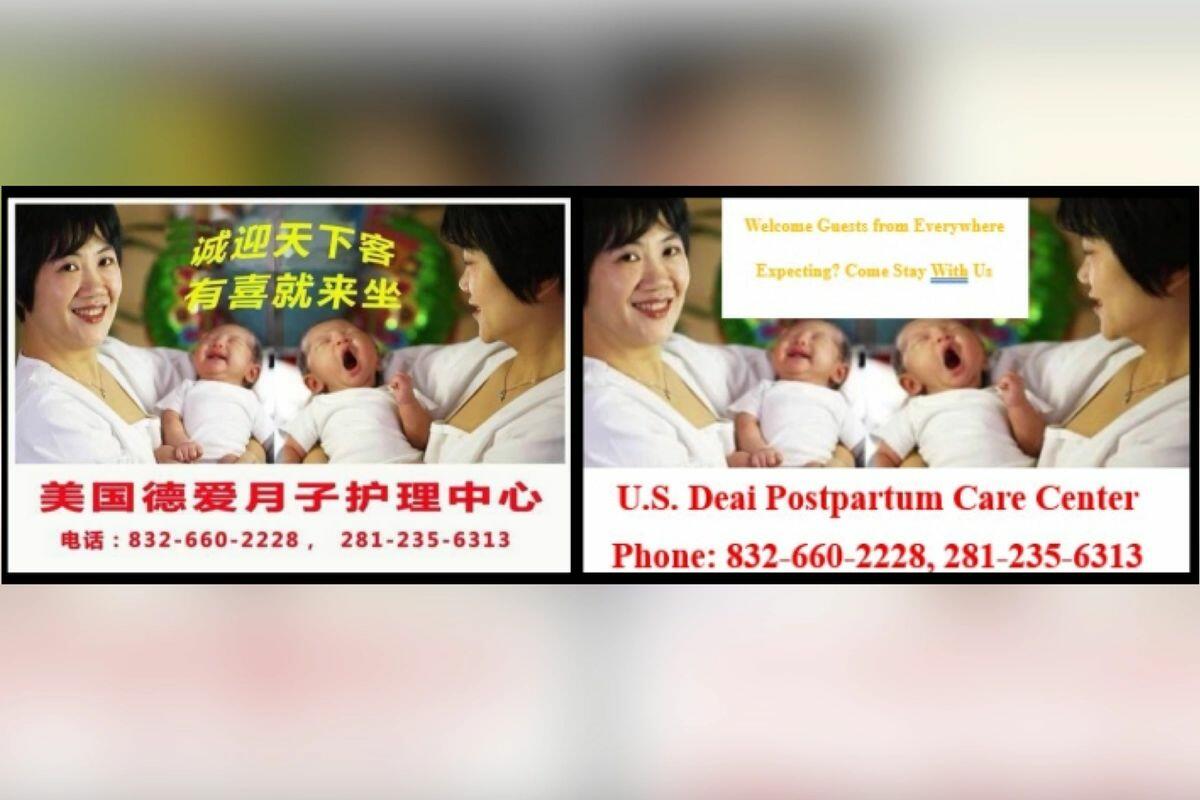
An advertisement for a Houston-area “birth tourism” operation known as De’Ai Postpartum Care Center. The Texas attorney general filed a lawsuit against the center, claiming it has operated an unlawful “birth tourism” business. Courtesy of the state of Texas Attorney General's Office

The center "unlawfully facilitated over 1,000 births to foreign Chinese nationals," Paxton posted on X.

Paxton's office first sued the operation in late April, stating the De'Ai Postpartum Care Center primarily helped Chinese nationals travel to Texas to give birth and secure U.S. citizenship for their children.

The center had operated for years across multiple Houston-area properties. Locations included sites in Sugar Land, Houston, Richmond, and Rosenberg, according to details from the original state lawsuit.

Gov. Greg Abbott on July 21 ordered Texas state agencies to start investigating and eliminating illegal birth tourism schemes and hold accountable any licensed healthcare providers that participate in them.

"Texas will not tolerate the exploitation of our immigration laws by individuals traveling to the United States illegally or under false pretenses to give birth and secure citizenship for their child," Abbott said in a statement at the time.

The De'Ai Postpartum Care Center did not respond to The Epoch Times after multiple attempts to contact them. The De'Ai Postpartum Care Center did not appear to maintain a public website in English, but it had two Chinese-language websites that have since been closed.

State investigators described facilities at the center that could house multiple families and an operation that was capable of handling up to 20 births per day, according to the attorney general's office.

"The Center's scheme not only facilitated an invasion of Texas, but it also involved shielding and facilitating violations of immigration law. Birthright citizenship is a scam that threatens national security, and I will do everything in my power to stop unlawful 'birth tourism' schemes like this one." Paxton said in an April 29 statement.

The lawsuit alleged the center coached clients on how to navigate immigration procedures and evade laws when seeking visas and citizenship for themselves and their children. That alleged coaching included encouraging Chinese nationals to conceal that the primary purpose of their travel was to give birth.

"To make matters worse, operators of the Center were aware that U.S. visas are prohibited for birth tourism purposes," Paxton's office said in a statement after filing the lawsuit.

"In fact, just last week, the Center noted that the federal government is 'strictly' policing birth tourism and recommended that women apply for visas 'before pregnancy' in order to avoid detection," his office stated at the time.

Expectant families could spend tens of thousands of dollars on the center's services, the suit claimed. Once a child born through the operation turned 21, that child could petition for permanent residency for parents and siblings.

Marketing occurred through social media platforms, private messaging applications, word of mouth, and Chinese websites, according to the complaint.

The lawsuit noted that since Jan. 24, 2020, the United States has expressly denied tourist travel "for the primary purpose of giving birth in the United States to obtain citizenship for the child," and has maintained that all birth tourism visa applications "will be denied."

Tom Gantert and Jill McLaughlin contributed to this report.

* * * (there's also an extra large compass)

Tyler Durden Mon, 09/21/2026 - 17:40

Diesel Hits New Record Above $6.50 As Export Ban Fears Mount, Gasoline Squeeze Looms

Diesel Hits New Record Above $6.50 As Export Ban Fears Mount, Gasoline Squeeze Looms

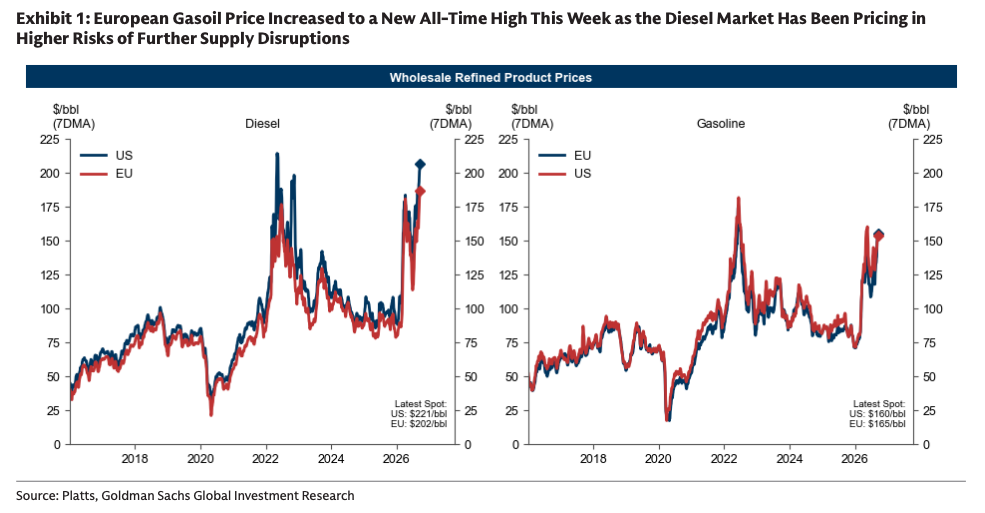
UBS analysts warned that the global diesel squeeze could get worse as two major suppliers potentially pull barrels from an already strained petroleum products market. Russia may extend diesel export restrictions through October, while chatter in Washington about a US fuel export ban continues to grow.

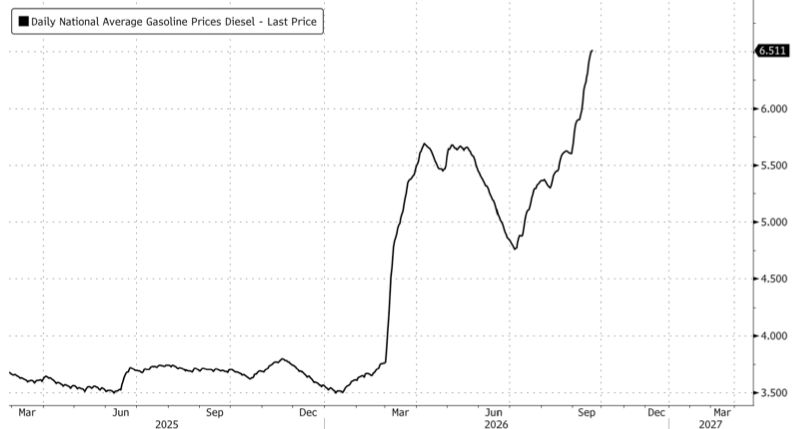
As of Monday morning, AAA data show the national average for diesel has reached $6.51 per gallon, with prices gaining a staggering 88 cents so far this month. Prices are rising nearly every day and surging beyond the peak set in 2022 during the early days of the Russia-Ukraine war. 

UBS energy expert Anna Kishmariya says a Russian extension would derail her team's assumption that exports would begin recovering in October as a domestic diesel surplus emerged. She said keeping restrictions in place could suggest more extensive damage to refinery units and a longer repair cycle than previously expected.

The bigger risk is a policy decision coming from Washington, as the US has accounted for roughly 30% of global diesel and gasoil exports this year. Any US export ban would leave major overseas importers highly exposed.

Iowa Sen. Chuck Grassley wrote on X this weekend that diesel prices at the pump in his state were hitting $6.57 a gallon and proposed the idea: "Why doesn't Pres. Trump put an embargo on diesel exports like presidents in the 70s put embargoes on ag products bc food prices were inflated."

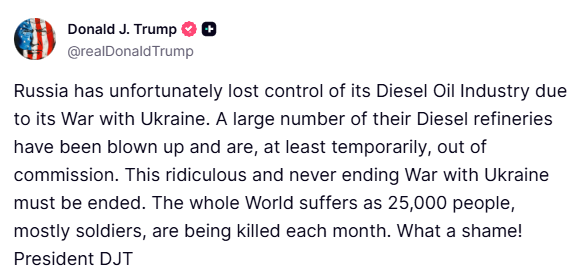
On Monday morning, Trump said Russia had "lost control" of its diesel industry due to the war with Ukraine, calling for an end to the "ridiculous and never-ending" war.

Trump was quoted by the Financial Times earlier today as saying he had been on a call with Ukraine's Zelensky, pressing him to stop drone attacks on Russian refineries.

The fuel shock is coming at an uncomfortable time for the Federal Reserve as it confronts broader inflation pressure. Policymakers raised interest rates by 25 bps last week, and Minneapolis Fed President Neel Kashkari warned that excessive inflation extends beyond energy.

Goldman Sachs commodity experts Yulia Zhestkova Grigsby and Daan Struyven warned last week that the diesel crisis could soon push gasoline prices higher, setting the stage for the next major squeeze.

"The key reason for this new recommendation is that refiners' switching output from gasoline to diesel is rapidly tightening gasoline markets, where less elevated price levels leave room for sharp price upside if the Mideast and Russia-Ukraine conflicts continued to constrain refining output for longer or if more energy infrastructure were damaged," Grigsby and Struyven wrote in the note. 

On the inflation front, Citi US economist Veronica Clark asked clients: "Will rising diesel costs push up goods prices?" 

Clark's take: 

We were surprised to see the median core PCE forecast in the September SEP rise to 3.4% from 3.3% in June. We think it is likely that most Fed forecasts do not include upcoming revisions and that core PCE will ultimately be lower than many officials are expecting this year. 

We continue to track core PCE around 3.0-3.1%Q4/Q4. A renewed substantial increase in energy prices has caused fresh concerns about pass-through to core inflation, particularly as elevated diesel prices mean higher transportation costs for various goods. But recent historical evidence is limited about the correlation between higher diesel prices and core goods in CPI. 

We are still hesitant to conclude there will be substantial pass-through as long as real income growth remains soft. Market rents have picked up slightly in recent months but remain softer than pre-pandemic, suggesting shelter inflation should continue to slow.

As for the proposed US export ban, Height Capital Markets research director Benjamin Salisbury noted, "While it may be politically tempting, we still expect Republicans to resist the urge to ban diesel or other petroleum exports." 

* * *

Tyler Durden Mon, 09/21/2026 - 17:20

Kunstler: Suburban Sprawl Is A 'Death Trap' For America's National Spirit

Kunstler: Suburban Sprawl Is A 'Death Trap' For America's National Spirit

Authored by James Howard Kunstler via Clusterfuck Nation,

The Late, Great Debate About Suburbia, An Apologia

"It is difficult to design a place that will not attract people. What is remarkable is how often this has been accomplished."

- William H Whyte

Greenland, yes, yes, okay ! Smooth move. . . !

But. . . today we put aside the vagaries of national and geo-politics to return to a longstanding affliction in American life that is evermore absent from the public discourse and deserves an airing: the quandary of our suburban sprawl living arrangement, and what can be done about it.

First, get this: the demolition derby we live in day-by-day is responsible for as much misery, injustice, economic failure, and ill-health as anything else in our collective doings.

Its sheer ugliness - the horror of the six-lane highway with its ensembles of strip-malls, burger shacks, muffler shops, topless bars, Big Box stops, screaming signage, and the vast wastelands of parking. . . the suicide-inducing housing pods marching out remorselessly through forest, prairie, upland, lowland, basin and range. . . the depressing freeways with their monster entanglements of on-and-off-ramps. . . this epic mutilation of our continental landscape - is an evil quite beyond our ordinary imaginings. This inescapable, immersive ugliness, I remind you, is entropy-made-visible. And entropy, of course, is the force in nature that you really don't want to mess around with because it is the agent of death.

I do not exaggerate. It's a death trap, the way we live in this country, for the mind, the body, the family, the community, and the national spirit. Until fairly recently this was widely apprehended (or at least suspected). But the politicization of everything has wrecked what had been a growing and pretty robust national discussion about it.

To re-cap briefly: this is a big country. It had once been composed of cities, towns, farmlands, and wilderness, a coherent transect of human habitation. The invention of the motor car changed all that, starting in the 1920s.

The ambiguous territory outside these cities and towns represented vast potential fortunes in property development. . . and the race was on.

The Great Depression and World War 2 interrupted the suburban expansion, but it resumed on steroids afterward when the rest of the world was a smoldering ruin and we could sell them anything (and lend them money to buy it). The construction of all the new suburban infrastructure alone was a major component of the late 20th century US economy, and then it became the scaffold for our so-called consumer economy, comprised of furnishing that scaffold with so much stuff that it overflowed into thousands of self-storage sheds.

The decanting of our cities that ensued - the steady dribble of the middle-classes moving out, along with the commerce that served them - left most of those cities ruined. Eventually even the small towns got whacked, the farms paved-over, too. What we're left with is a weird hybrid landscape that is neither town nor country, has few of the civic amenities that add-up to a genuine sense of community, and none of the rural charm formerly found in the countryside. It became painfully obvious that a suburban house was a cartoon of a house in the country, and living in a cartoon is just not spiritually rewarding. Cue the Prozac. . . .

The whole kit, aided by the dogmas of zoning and government lending schemes, became easily reproducible from one locale to the next. For the development industry, the template became a habit. . . and so it boogied on through the decades. By the 1990s, the generation coming into power (yeah, the Boomers) started a revolt against all that. It crystalized in the New Urbanism movement and its signature org, the Congress for the New Urbanism, CNU. We can do better than this, this. . . this. . . national clusterfuck, they declared.

I was excited by this movement, wrote a couple of books about it, got to know the excellent people behind it - architects, urban planners, civic officials, property developers. They were smart, skilled, visionary. They believed that walkable communities and disciplining the automobile would produce places worth caring about and worth living in - and it seemed to me that such an effort would go a long way to curing the desperate anomie of American life. Over the next several decades, the New Urbanists produced scores of great projects. Some were actual new towns, some projects were renovations of existing towns, neighborhoods, business districts, and small town Main Streets. The results of their work are visible all over the country now.

But then, the political crack-up of the country commenced around 2009 with the Great Financial Crash and the ascent of Obama-inspired Wokeness, and really accelerated with the reaction to the advent of Mr. Trump in 2016. From that point on, as a nation, we've been arguing about everything but the disastrous arrangement of daily life on-the-ground in America. Some new twists in the spin of history have made matters worse.

One is that suburban sprawl is, by default, the favorite pattern of MAGA (and I happen to be a Trump voter). To them, suburbia is all tied up with ideas about economic liberty, as is the whole apparatus of Happy Motoring. They are still mentally stuck in the imagery of the TV car commercial - the lone sedan gliding through the sine-cosine curves of the empty seacoast highway, the romantic epitome of freedom! It's a lie, pretty much, because the more universal experience of motoring these days is getting stuck at a crawl in freeway traffic with a thousand other motorists per mile, half of whom desperately need to take a pee and can't do a darn thing about it.

And then there's the fallacy of the suburban housing development being a "community" - bwa-ha-ha-ha-ha-ha! See: I don't even have to explain that. But, MAGA tends to see it this way, along with all the activity that enables it - the mortgage system, the production home-builders ("it's more than a house, you understand, it's a home!"), all of which is so central to a booming economy. So, you don't dare inveigh against suburbia - except I will, because it is making America worse, not great again, and somebody's got to say it.

Yet another thing has come along to wreck the New Urbanist dream of reconstituting the American city and small town, and that thing is the World Economic Forum's (WEF's) proposal they call the "15-minute City." Superficially, it seems to resemble the traditional neighborhood model that the NU's espouse. But deeper down the 15-Minute City is much more about a surveillance and tracking apparatus - and this has caused many conservatives (especially them) to reject anything that looks like traditional urban design.

It's a most unfortunate situation, but that's where things stand, and it's one reason that the debate over suburban sprawl has stopped. A final and equally unfortunate development is that the CNU org came to be taken over the past decade by political Wokesters more interested in Diversity, Inclusion, and Equity BS than in their original mission of providing workable remedies for the tragic fiasco of American suburbia.

And now you know why it is so hard to talk about this geography of nowhere anymore.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden Mon, 09/21/2026 - 16:20

Judge Rules EPA Must Reinstate $7 Billion Biden-Era Subsidies For Solar Promotion

Judge Rules EPA Must Reinstate $7 Billion Biden-Era Subsidies For Solar Promotion

Authored by Jeremy Lott via The Epoch Times,

A $7 billion federal government grant program for solar promotion, authorized during the Biden administration, was reinstated by a federal judge on Sept. 18 in a ruling that rebuffed the Trump administration's efforts to cancel it.

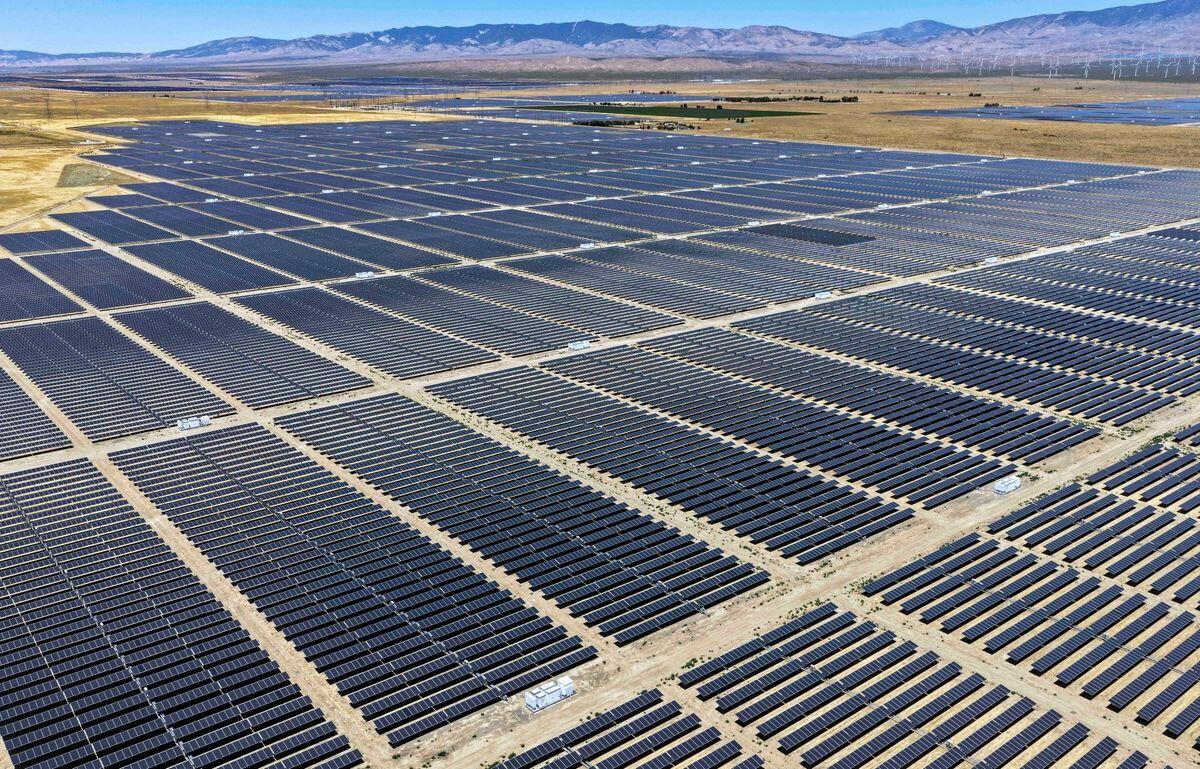
Solar panel array at a solar farm near Lancaster, Calif., on June 17, 2026. Mario Tama/Getty Images

Judge Mary McElroy of the U.S. District Court for the District of Rhode Island wrote in her ruling that the current Environmental Protection Agency's (EPA's) "termination of the Solar for All program is declared unlawful."

Money was appropriated in 2022 for a Greenhouse Gas Reduction Fund under the Inflation Reduction Act that later spawned the $7 billion Solar for All grant program in June 2023. Congress at the time dedicated billions of dollars to the program and a separate smaller amount in the millions of dollars for its administration by the EPA.

Funds for the grant program would be used to "create and expand low-income solar programs that provide financing and technical assistance, such as workforce development, to enable low-income and disadvantaged communities to deploy and benefit from residential solar," the Biden-era EPA wrote.

Current EPA Administrator Lee Zeldin criticized the program on Sept. 7, 2025, saying that canceling it would save taxpayers billions of dollars.

"The One Big Beautiful Bill eliminated the Greenhouse Gas Reduction Fund, which included a $7 billion pot called 'Solar for All,'" he said in a statement announcing the program's cancellation.

"EPA no longer has the statutory authority to administer the program or the appropriated funds to keep this boondoggle alive."

An audit of the program found that as of early August 2025, the program's 60 grant recipients had "drawn down approximately $71 million, or 1.02 percent, of the obligated funds for various aspects of project planning and implementation."

The Trump-era EPA canceled the program. Under the One Big Beautiful Bill Act, the current Congress canceled some funds for administering the program and rescinded Greenhouse Gas Reduction Fund money that was not already obligated.

The EPA noted that none of the plaintiffs suing the government were actually grant recipients. Instead, they were prospective subrecipients or third-order beneficiaries, such as unions. The government argued that they lacked standing to sue.

McElroy disagreed on the standing question. She also interpreted the text of the One Big Beautiful Bill Act to mean that "existing grants were not to be rescinded" and that only minor "unobligated" funds could be clawed back.

Practically, all of the funds were spoken for by designated recipient organizations. What that means is that, unless reversed on appeal, the current EPA may find itself obligated to give out the remaining nearly $7 billion in solar promotion subsidies from the Biden era.

Patrick Crowley, president of the Rhode Island AFL-CIO, one of the parties that brought suit, told The Epoch Times that he was "very pleased with the ruling."

The union president said he did not "think the federal government should appeal," as the ruling makes "very clear that this program should never have been stopped by the EPA in the first place."

Carolyn Holran, a spokesperson for the EPA, indicated that Crowley might be disappointed by her agency's next steps.

"EPA is reviewing the decision and considering options for appeal," she told The Epoch Times.

Crowley said the total Rhode Island slice of federal funding should come to $49 million, which would provide "thousands of good-paying union jobs."

Unions and the Trump administration have often been at loggerheads over green projects. Crowley said that they had notched up legal victories on offshore wind projects and solar grants, and promised more.

"We won't back down in our efforts to protect our members' jobs while we build a new carbon-free economy," he said.

Tyler Durden Mon, 09/21/2026 - 15:45

Verizon Says Cut Cable Behind FAA Ground-Stops East Coast Airports, Not Their Fault

Verizon Says Cut Cable Behind FAA Ground-Stops East Coast Airports, Not Their Fault

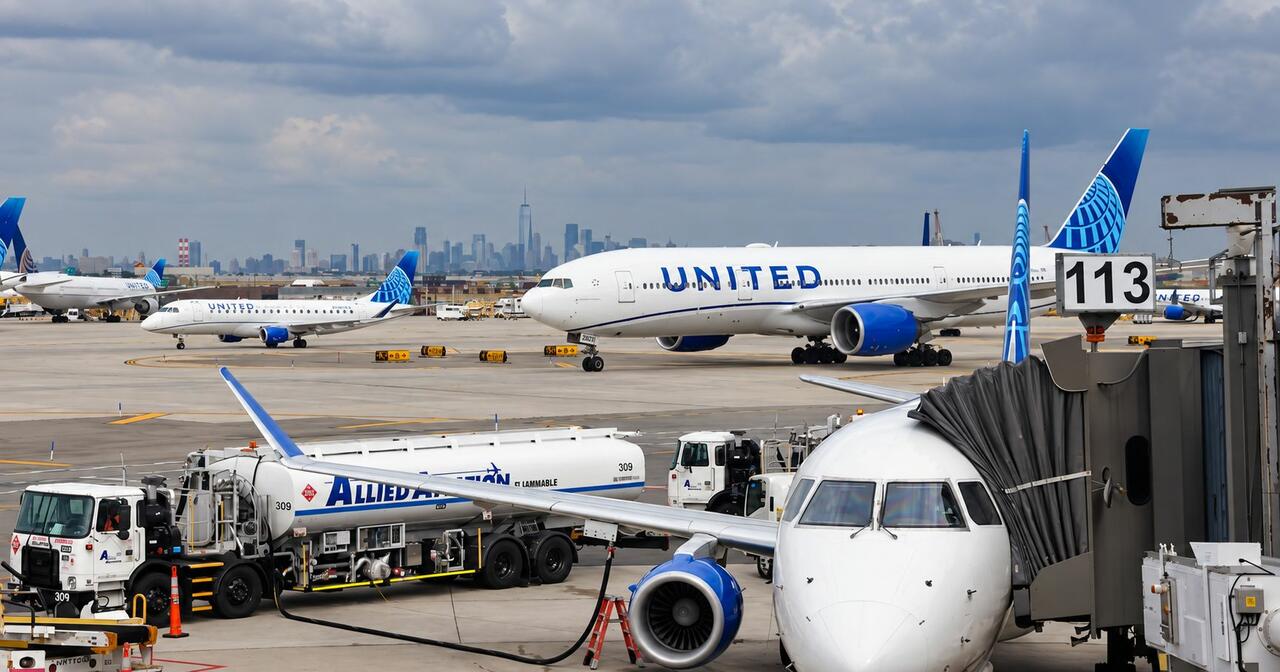
(Update 1540ET): Verizon confirmed the "unknown equipment issue" behind the massive ground stop in the tri-state area was a cut fiber cable in New Jersey. The company says construction contractors working near an Amtrak rail line dug it up, that Verizon's facilities were fully functional until that happened, and that the carrier bears no responsibility for the incident. Technicians are on site, and the company says it is working to repair the damaged cable and restore connectivity.

FAA Administrator Bryan Bedford told reporters an older circuit serving Philadelphia TRACON failed this morning. Controllers tried to flip to the backup fiber the agency had installed as part of its modernization push, and the backup was already dead. The agency did not know the fiber was cut until the primary circuit went down, Bedford said. The damaged stretch is roughly 600 feet between New Brunswick and Newark. Repairing that line, he said, could take about 13 hours. "It's massive, I'm told."

Transportation Secretary Sean Duffy put it more bluntly: an Amtrak construction crew cut into the fiber and forced the FAA to pause Northeast traffic.

By mid-afternoon LaGuardia had resumed in some form, and Philadelphia and JFK were being walked back from full ground stops toward delay programs. Newark and Teterboro were still the problem children. That is the airspace Philadelphia TRACON was handed in 2024, the same facility that had radio-frequency trouble last August and a string of radar and comms failures through 2025.

The FAA is trying to stand up a replacement circuit rather than wait out a 13-hour splice. Until the data is flowing again, inbound traffic into the remaining restricted fields stays on the ground at origin, which is still a ground stop, still the most restrictive tool the agency has. World leaders are landing in New York this week for the UN General Assembly.

* * *

The FAA has issued ground-stop orders to arrivals into every major New York-area airport: JFK, LaGuardia, and Newark. Teterboro, Westchester, and Philadelphia are in the same pile. Official reason: equipment outage.

What happened

The first restrictions hit Newark, Teterboro, and Philadelphia after problems with radio frequencies at Philadelphia TRACON, the terminal radar facility that handles arrivals and departures in that airspace. The FAA later added JFK, LaGuardia, and Westchester.

The agency has not publicly detailed which systems failed, how long repairs will take, or whether New York TRACON (N90) is separately affected. That lack of specifics is why the disruption is being described as an "unknown equipment issue."

A ground stop holds aircraft destined for the listed airports on the ground at their origin. It is one of the FAA's most restrictive tools and is used when controllers cannot safely accept more inbound traffic.

What actually broke? Frequencies, per the first FAA statement. Then just "equipment / outage" on the national status board. No system named, no timeline, no "we kicked the rack and it came back."

Philadelphia TRACON is not a random facility: it is the same one that took over Newark approach control in 2024 and then suffered repeated radar and radio failures through 2025, severe enough that controllers went out on trauma leave. On Aug. 28 of last year, the FAA ground-stopped Newark for roughly two hours over what it called equipment issues affecting "some radio frequencies in the Philadelphia TRACON area," with arrival delays averaging about 90 minutes - the same facility and the same stated cause as today. 

Impact

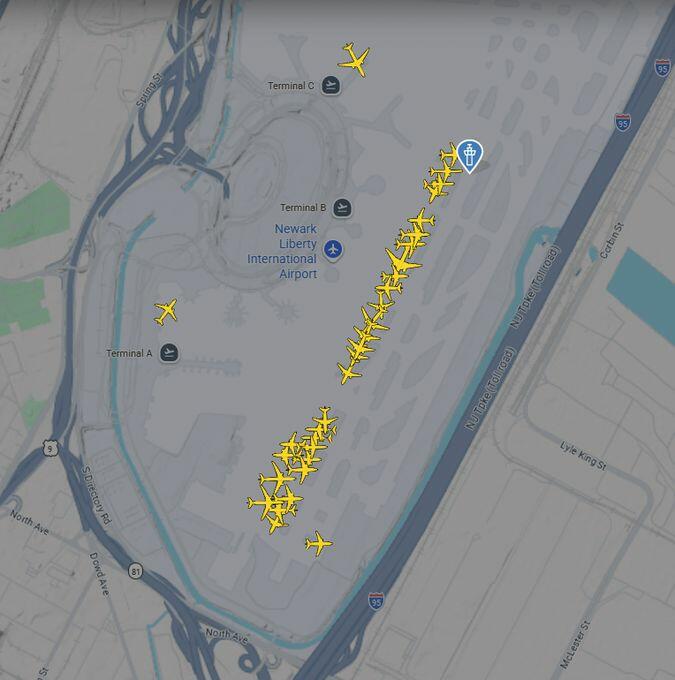
Newark saw the earliest and heaviest effects. As of 11:07 a.m. ET, FAA data showed average departure delays out of Newark running about 90 minutes and increasing, with the ground stop set to expire at 11:15 a.m. and a 30-60% chance of extension. Flight-tracking data showed dozens of jets queued on the pavement, along with dozens of cancellations and diversions. Teterboro departure delays were steeper.

Via @Bogs4NY

Boston Logan also has restrictions, though those are listed as volume and weather rather than the same equipment problem.

Because JFK, LGA, and EWR sit on one of the busiest corridors in the country, the stops ripple nationally: crews and aircraft get out of position, later banks get late, and connecting passengers miss onward flights.

Maybe another rogue AI escaped a sandbox? 

Tyler Durden Mon, 09/21/2026 - 15:40

Bessent Declares All Iran Airlines To Be 'Shut Down Around The World' Wednesday

Bessent Declares All Iran Airlines To Be 'Shut Down Around The World' Wednesday

Treasury Secretary Scott Bessent declared on Monday that by Wednesday Sept. 23, "all the Iranian airlines will be shut down around the world."

"If they land, you cannot provide them with fuel, you cannot provide them with landing services, you cannot sell them tickets, or you will be knocked out of the dollar system," he described.

The new warning and 'promise' was issued after the US earlier this month imposed sanctions on "all remaining Iranian airlines" which had yet to face such penalties - thus Bessent's new declaration is that these entities are about to collapse under the weight of Washington actions, which now is to include secondary targeting.

The Treasury Department has also lately targeted Iranian companies and industries supporting Iran's aviation sector.

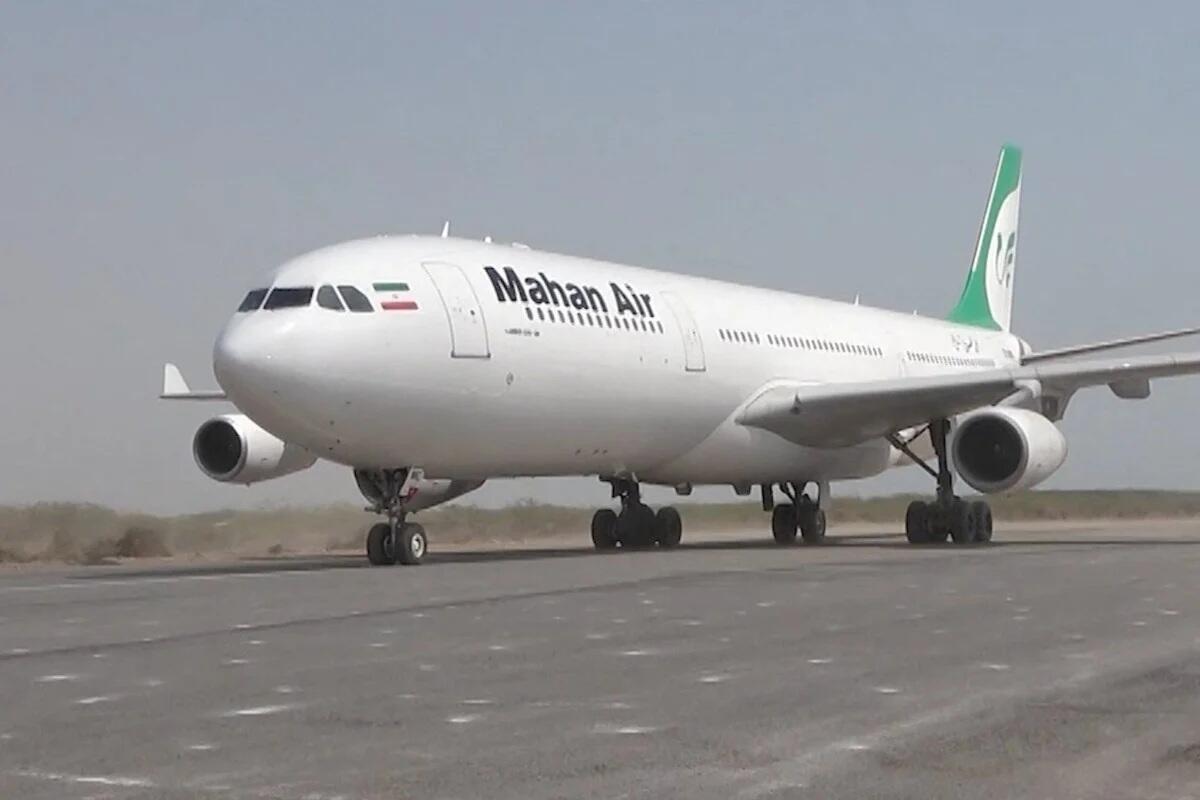
Some 27 airlines have already been sanctioned - also most recently the major Mahan Air has faced expanded sanctions (after first being targeted by Washington all the way back in 2011).

The Treasury has famed all of this as part of efforts to deny the Iranian government the ability to move "weapons, personnel, and illicit cargo".

Bessent stated to CNBC that all Iranian airlines will be shut down globally on Sept. 23 - given that any fuel, landing, and ticket providers involved with the companies risk dollar-system exclusion.

Ironically, Iran's President Masoud Pezeshkian and his delegation is expected to fly into New York City just the day prior, on Tuesday - to attend the UN General Assembly. He is set to give a formal address to the UN body on Wednesday.

This will provide rare opportunity for potential White House diplomacy to take place on the sidelines, which could happen as early as Tuesday.

As for the heavily sanctioned aviation industry, in recent years the Islamic Republic has suffered some significant aerial disasters, which included the May 19, 2024 death of President Ebrahim Raisi. His military helicopter went down in a rugged, mountainous area of northwestern Iran.

via Reuters

Some speculate that lack of airline parts and aging aircraft, due to the long-standing US targeting of the industry, has only served to increase the chances of aviation disasters.

Tyler Durden Mon, 09/21/2026 - 15:30

US Opens Foreign Funding Investigations Into Duke, University Of North Dakota

US Opens Foreign Funding Investigations Into Duke, University Of North Dakota

Authored by Naveen Athrappully via The Epoch Times,

The State Department and the Department of Education are investigating Duke University and the University of North Dakota over allegedly violating foreign funding disclosure rules.

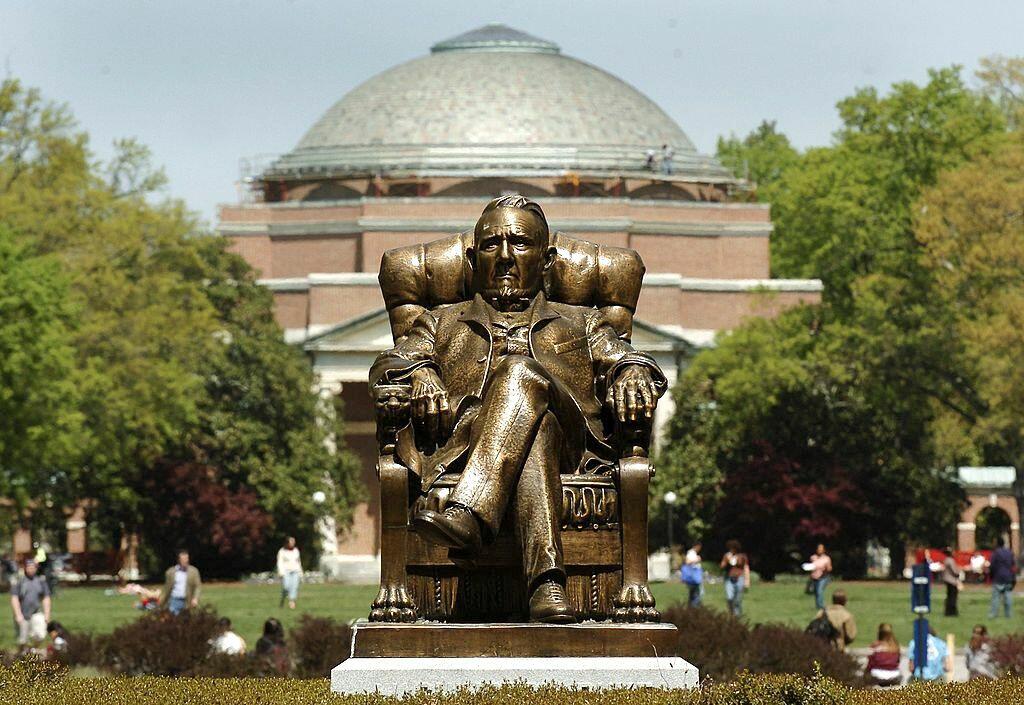
The statue of Washington Duke on Duke University's East Campus with Baldwin Auditorium is shown in Durham, N.C., on April 11, 2006. Sara D. Davis/Getty Images

Section 117 of the Higher Education Act of 1965 requires postsecondary institutions that receive federal financial assistance to disclose the source of foreign gifts and contracts with an annual value of $250,000 or more, according to a Sept. 16 statement.

The law aims to counter undue foreign influence in America's higher education sector. Both universities receive taxpayer support to develop crucial technologies.

However, a review of records submitted by the universities "indicated the submission of incomplete, inaccurate, and untimely disclosures," the Department of Education said in the statement.

In a Sept. 15 letter to Duke University president Vincent E. Price, the department raised concerns about the institution's research collaboration with China's Wuhan University. This agreement between the universities has led to the establishment of Duke Kunshan University in Jiangsu, China, in 2013.

Wuhan University is overseen by China's Ministry of Education and another state entity that oversees China's nuclear weapons and military research programs. The institution plays an important role in the country's national defense science and tech innovation.

China's Ministry of Education requires joint-venture universities, such as Duke Kunshan University, to have a Chinese Communist Party (CCP) unit to monitor their operations. These units can also influence administrative tasks. Moreover, Duke Kunshan University's Board of Trustees appears to include key Chinese regime officials, according to the letter.

The Education Department's review of Sec. 117 disclosure reports from Duke shows that the university has reported 1,266 qualifying foreign funding transactions since July 2020, totaling roughly $1.01 billion. The institution allegedly engages in "systemic reporting errors related to timely disclosure of contracts with foreign sources," the department said in the letter.

As for the University of North Dakota (UND), the department's Sept. 15 letter to the institution's president Andrew Armacost highlighted the university's critical role in America's national security efforts.

Specifically, UND's School of Aerospace partners with the North Dakota Army and Air National Guard, the U.S. Air Force, and private sector defense contractors. UND also provides a training environment to support U.S. drone dominance in uncrewed air systems.

Since July 2020, the university has reported 71 transactions that would qualify under Section 117, valued at around $98 million. Many of these transactions "appear to have involved Chinese aviation companies," the letter said.

The Department of Education instructed both universities to submit records of tax compliance; Section 117 compliance structure; international research collaborations; foreign government talent program compliance; foreign gifts, grants, and contracts; and international faculty, research personnel, and student agreements.

"Unfortunately, it appears that both Duke and UND have provided untimely and incomplete foreign funding disclosures, which include erroneously identifying certain governmental partners as 'non-governmental,'" Under Secretary of Education Nicholas Kent said in the statement.

"We expect these universities will cooperate fully. The Department of Education and the Department of State will continue to work together to vigorously ensure the integrity and accountability of our nation's colleges and universities in reporting their foreign gifts and contracts," Kent said.

The Epoch Times reached out to Duke University and the University of North Dakota for comment but did not receive a response by the time of publication.

In an email to The Chronicle, Duke's student-run news organization, a spokesperson from the institution said they were "reviewing the letter carefully." The university is "committed to complying with the law and will continue to do so in a manner that is consistent with our academic mission," the spokesperson said.

The recent investigations come after the Education Department announced its partnership with the State Department in February, aimed at improving transparency of foreign contracts and gift reporting in higher education institutions.

According to a fact sheet published at the time, the partnership aligns with President Donald Trump's April 2025 executive order, Transparency Regarding Foreign Influence at American Universities.

In the order, Trump wrote that it is the administration's policy to "end the secrecy" regarding foreign funds flowing into the country's educational institutions.

Last month, the Pentagon announced it had asked 30 academic institutions to audit their research, academic, and financial collaborations with foreign entities that are deemed to threaten national security.

The Pentagon's notices were sent to universities linked to certain research facilities or foreign schools in China, Iran, or Russia.

Tyler Durden Mon, 09/21/2026 - 15:00

Big Tech's Next AI Battleground Is Your Face, Loop Capital Says

Big Tech's Next AI Battleground Is Your Face, Loop Capital Says

Smartglasses are set to be the "next major computing platform," according to Loop Capital analysts, as Meta currently leads the space, with Google, Samsung, Apple, and SNAP preparing their own AI-powered eyewear.

Loop Capital analyst Rob Sanderson wrote in a note on Sunday that an "inflection point" has arrived for smart glasses, which are "transitioning from wearable camera accessories to what is becoming a primary hardware interface for conversational AI."

Sanderson and analyst Anthony Chukumba spoke with wearable-tech executive Jon Li about the smart glasses industry and where it's headed into the new year.

Li shared our view that Meta dominates the smart glasses industry with its Ray-Ban Meta smart glasses, while Google is building an ecosystem around Android XR and Snap holds an advantage in more advanced augmented reality. He said Apple could remain on the sidelines until 2028 or 2029 before introducing its own smart glasses.

Here are the key points from the conversation between Loop Capital analysts and Li:

Jon Li is a seasoned technology executive with extensive product management, user experience design, and business development experience. Mr. Li is currently Managing Partner of strategic consultancy Asentio where he advises companies on product strategy, commercialization, and human-AI collaboration. He previously served as US General Manager for XREAL, where he was instrumental in driving the company's expansion into the US market through the development of strategic and retail distribution partnerships. Earlier in his career he held senior product and program management positions with Indigo Technologies, SERES EV, and YouSpace and senior design positions with Motorola, Philips, and FLIR Systems.

Bullish on Android XR broadly... Mr. Li is bullish on the Android XR smartglasses operating system (OS), which Google has developed in partnership with Samsung and Qualcomm. He noted Android XR leverages Google's existing Android OS, large developer base, and mature developer framework and tools. In addition, Mr. Li views Android XR as a "true digital assistant" with the ability to utilize users’ calendars, tasks, documents, location, etc. to provide contextual assistance in real time. He noted one significant difference between Android OS and Android XR is Google plans to more tightly control distribution of the latter by working with a limited number of partners (e.g., Samsung, XREAL). Mr. Li expects Android XR and Gemini AI features to be updated every few months, while hardware changes would occur at most once a year.

...and Warby Parker's Intelligent Eyewear more specifically. Mr. Li is also fairly upbeat about Warby Parker's forthcoming Intelligent Eyewear launch, which he views as a key component of mass market smartglasses adoption. Mr. Li believes Warby Parker is a compelling Android XR partner given the optical retailers' history of transforming the eyeglass purchase process (i.e., online and in store) as well as ability to educate first-time buyers and provide initial fittings and post-purchase support. All that said, Mr. Li questioned the strength of Warby Parker's post-purchase customer relationships given the fact Google, not Warby Parker, controls the digital assistant consumers will be interfacing with.

Views Snap as having a multi-year lead on full AR. While previous versions were not released for commercial distribution, Snap's recently introduced SPECS are the company's 5th generation hardware design. Mr. Li believes Snap's long-term focus and extensive experience with augmented reality on smartphones gives it a multi-year lead over competitors and expects the cadence of multiple iterations will shrink and cost-reduce its offering. Mr. Li sees enterprise suitability and highlights the base of customers in industrial production, manufacturing, healthcare and other verticals left stranded by Microsoft's discontinued HoloLens platform as an area of obvious interest. Mr. Li believes it will ultimately be the developer community and partner ecosystem that drives category adoption and sees Snap's ~450K developers using Lens Studio as a meaningful advantage.

Apple launch probably later than sooner, will lift overall market. Mr. Li believes Apple is unlikely to enter the smartglasses market until 2028/2029 given the company's long history of learning from competitors' earlier products to introduce a superior version later (e.g., iPod, iPhone, AirPods). Mr. Li believes Apple will initially introduce a premium, higher priced product (i.e., ~$800 as compared to $499 for the top-of-the-line Ray-Ban Meta Wayfarer Optics) and focus on user experience as opposed to hardware specifications; ultimately, he thinks Apple's success will hinge on the strength of the AI assistant and level of integration with the broader iOS ecosystem, stating Siri AI is not yet where it needs to be. Mr. Li thinks an Apple entry will be a net positive for existing industry players by drawing more attention to and legitimizing smartglasses, pointing to the impact the company's recent introduction of the iPhone Duo is having on foldable smartphones. 

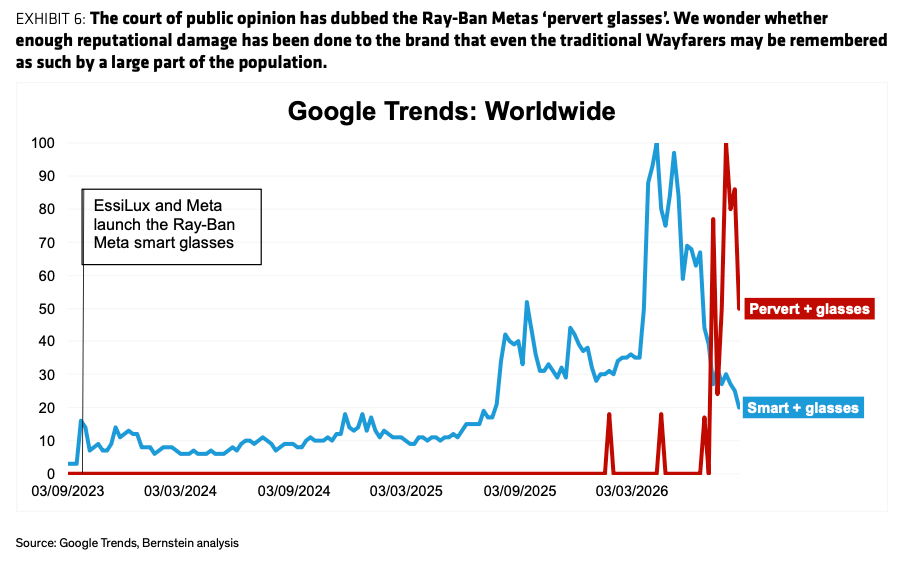
Beyond Loop Capital and their insights into the smart glasses industry via an insider, Luca Solca, Bernstein's senior equity analyst and global luxury-goods sector head, covering companies including EssilorLuxottica, LVMH, Hermès and Richemont, and recently pointed out emerging backlash in the public domain of these glasses, with some trends on social media going viral, such as "pervert glasses," and such. 

We suspect Meta, Snap, Google, and other players will eventually need to confront the "pervert glasses" narrative with a counter narrative of their own. Good luck solving that with a marketing campaign.

Tyler Durden Mon, 09/21/2026 - 14:45

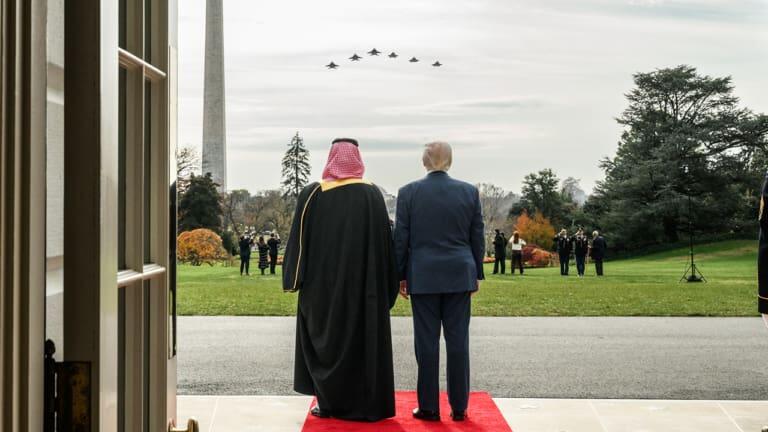
Trump's 48-Hour Houthi Strike Whiplash Was Triggered By Desire To 'Help His Friend' MbS

Trump's 48-Hour Houthi Strike Whiplash Was Triggered By Desire To 'Help His Friend' MbS

President Trump's abrupt Saturday return to the White House from Camp David, where he had been slated to spend the whole weekend, had set off an avalanche of speculation on potential military escalation in the Middle East.

The NY Times and Axios are reporting that the Commander-in-Chief was close to a ordering new anti-Houthi intervention but that he backed out, TACOing once again but this time in pretty rapid order.

Source: White House

"President Trump over the weekend considered ordering a strike against the Houthis in Yemen before deciding to hold off for now, two U.S. officials said," Axios writes Monday. "Trump was caught between wanting to help his friend and ally, Saudi Crown Prince Mohammed bin Salman, and avoiding getting entangled on a new front in the Middle East."

So now the nation stands on the brink of yet a separate Mideast adventure while the Iran conflict has yet to end, this time in Yemen, because Trump desires to "help his friend". But in the end he did not pull the trigger, for now at least.

The NY Times on Sunday laid out a wild, whiplash of a fast-paced timeline in terms of decision-making:

Mr. Trump had met with advisers just the day before and told them he did not favor strikes. But after speaking with the Saudi crown prince, he reversed himself and told the Pentagon to prepare for airstrikes against the Houthis.

But by midday Sunday, the president appeared to have reversed himself again. There would be no U.S. airstrikes against the Houthis — at least not for the time being, according to administration officials. The officials spoke on the condition of anonymity because they were not authorized to discuss military planning.

One wonders if Congress might ever be consulted, instead of going to war after a single phone call with 'friends' in Saudi Arabia and Israel?

Trump has reportedly been mulling what to do about the Yemen crisis for the last two weeks, especially as the Shia group backed by Tehran has ramped up attacks on Aramco facilities in the kingdom.

So far, the White House is only said to have authorized intelligence and targeting assistance. Still, the Houthis keep advancing, regional reports say, after having conquered Yemen's Red Sea coast. To review of some of our Monday morning coverage:

Brent crude oil prices are also lower despite news that Donald Trump had cut short a trip to Camp David to return to Washington, reports that Iran had activated its highest military readiness alert amid claims that the US is preparing to resume attacks, Houthi attacks on the Saudi capital Riyadh, and Pentagon Pizza Report activity suggestive of something afoot.

All of this was accompanied by fresh alerts for American travelers issued by US embassies across the whole Mideast region.

For a little trip down memory lane...

Even if Trump were to authorize new direct strikes on Yemen, any purely aerial campaign would be very unlikely to dislodge the Houthis. It could also serve to further divide already stretched-thin US forces and assets in the region. US assets operating over the Gulf area might have to be diverted.

The Houthi rebels have already endured literally dozens of major air raids from the US and Israelis stretching back through the Gaza war. The attacks seemed to only embolden them, and now they can put the chokehold on Red Sea shipping at any time they want.

Tyler Durden Mon, 09/21/2026 - 14:30

Critical Metals Shares Soar On Trump's Greenland Deal As Mining Stocks Eye Rebound After Summer Slump

Critical Metals Shares Soar On Trump's Greenland Deal As Mining Stocks Eye Rebound After Summer Slump

Critical Metals jumped 37.5% to $9.22, while Greenland Energy surged 126% and Greenland Mines soared 136% on news this past weekend that President Trump had announced a security deal with Denmark and Greenland. This is fueling Wall Street's expectations of greater US access to the territory's mineral resources.

Trump said Friday in a lengthy Truth Social post that the US had reached a deal with Denmark and Greenland granting it control over Greenland's security. Danish and Greenlandic officials said the agreement preserves Greenland's sovereignty.

"At my direction, we worked with representatives of Denmark and Greenland to guarantee that the United States will FOREVER have the complete ability to do what is necessary in Greenland to secure and defend the security of Greenland, and the United States of America," Trump stated.

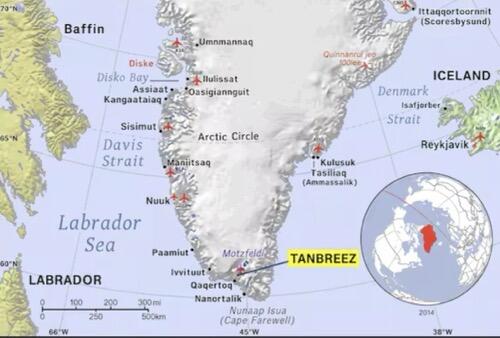
Critical Metals' Tanbreez project offers the West conflict-free (meaning ex-China) rare earth supplies. The company says heavy rare earths make up about 27% of the deposit's total rare-earth content. These materials are critical for magnets, defense systems and precision electronics. 

Based on Critical Metals' latest disclosures, Tanbreez is not yet in commercial production. The company describes it as an advanced, permitted development project that will supply rare earths "once operational."

What's notable about the Tanbreez project in southern Greenland is that it contains about 45 million metric tons of resources. 

According to Critical Metals' March 2026 slide deck, Tanbreez is targeting first ore production in late 2028 or early 2029, with concentrate exports beginning by the third quarter of 2029. That is a major problem for the West, and the market is getting ahead of itself because these critical metals were needed yesterday, as China's quasi-monopolistic position in critical metals is currently choking the West.

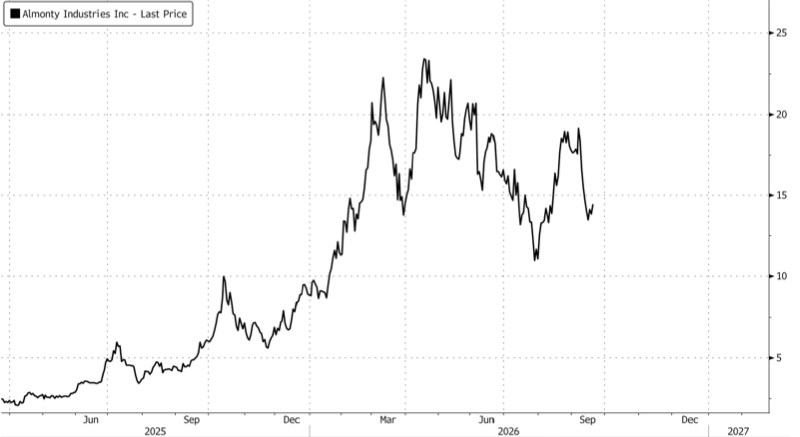
That's why we're focused on producers that can deliver today rather than junior miners, as highlighted by the Bloomberg news earlier this morning that South Korea gave Almonty Industries the green light to begin shipping tungsten ore from its Sangdong mine to overseas customers. 

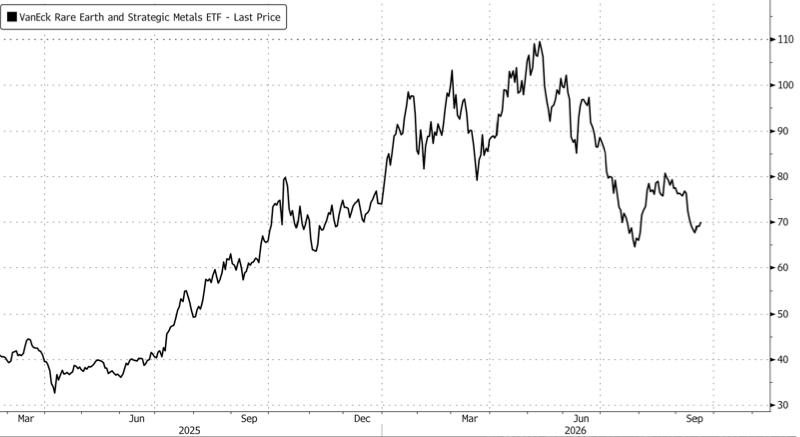
The VanEck Rare Earth and Strategic Metals ETF (REMX) is a fund that holds shares of lithium, tungsten, and other materials miners. 

Its positions include:

  • SQM: 7.89%
  • Albemarle: 7.74%
  • MP Materials: 6.22%
  • Lynas Rare Earths: 5.93%
  • Almonty Industries: 4.15%

REMX saw a massive run-up beginning in mid-2025 and peaked around June before retracing about 40%. Now the mining ETF is stabilizing with a higher low and could be due for an upside move.

With China choking off critical metal supplies to the West, the market should focus on miners that are producing today and can deliver to fill the West's supply gap. Early movers will win. 

Tyler Durden Mon, 09/21/2026 - 14:15

Wall Street Turns Its Back On Consumer Stocks As Fuel Costs Soar And Yields Surge

Wall Street Turns Its Back On Consumer Stocks As Fuel Costs Soar And Yields Surge

US gasoline prices near $4.44 a gallon at the pump, record diesel prices of $6.40 a gallon, and the Federal Reserve's interest-rate hike this week, its first since July 2023, are compounding pressure on household budgets and borrowing costs. Against that troubling backdrop, UBS warns that Wall Street is "turning more skeptical on consumer recovery."

UBS equity trader Mark Paski wrote in a note to clients on Wednesday about the gloomy environment for consumers that has placed renewed selling pressure on consumer stocks as Wall Street grows increasingly skeptical of a second-half earnings recovery, with recent management commentary pointing to persistent cost pressures and limited evidence of a meaningful rebound in demand.

"While part of the recent weakness can be attributed to higher crude prices and rates, the sharp sell-off across apparel, retail and restaurant names suggests investors are looking beyond those factors. Feedback from the conference circuit pointed to a common theme: persistent macro uncertainty, ongoing cost pressures and little evidence of a near-term demand inflection. Management teams broadly flagged pressure from inflation, transportation costs, fuel prices and cautious consumer behavior, reinforcing the view that earnings recovery may take longer than previously expected," Paski said.

He noted that consumer companies' share of S&P market capitalization has tumbled to just 13.5%, a record low, from about 31% in 1992. That decline shows the sector is becoming less relevant to investors.

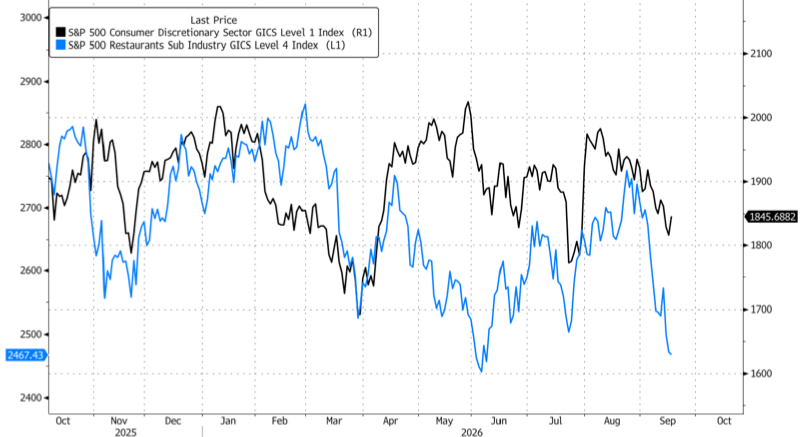
S&P restaurant stocks are weakening more sharply than the broader consumer discretionary sector, signaling this growing concern ahead of midterm elections.

The hoped-for consumer rebound in the second half is running into a familiar problem: businesses face rising costs while customers remain reluctant to spend.

Speaking at Goldman Sachs' 33rd Annual Global Retailing Conference on Tuesday morning, Dollar General CEO Todd Vasos offered a downbeat assessment of its customer base, warning that "even that middle to upper middle is acting more like a lower income shopper these days."

At the start of the week, Jefferies food analyst Scott Marks flagged new pressure on convenience store customers as gasoline and diesel prices soared in August.

Professional subscribers can read a lot more about consumer stocks here at our new Marketdesk.ai portal. 

Tyler Durden Mon, 09/21/2026 - 13:40

Powerful Explosion Rocks Aleppo Ammo Depot In Latest Mystery Blast

Powerful Explosion Rocks Aleppo Ammo Depot In Latest Mystery Blast

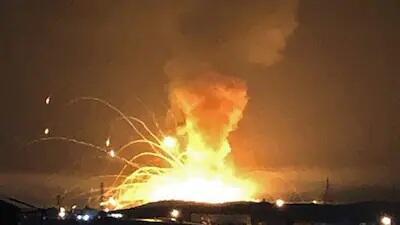
A terrifying blast erupted outside the major northern Syrian city of Aleppo overnight, which caused area residents to evacuate their homes, and with sustained explosions visible for miles around.

The explosion happened at an army base in an outlying town, injuring at least four people, after which a series of blasts persisted, which unleashed shrapnel across the area.

State media outlet SANA later cited Ministry of Emergency and Disaster Management which indicated an ammunition depot was detonated.

Amid local evacuations, emergency crews were on "high alert... due to the continued explosions" - after being initially unable to get close given persisting and follow-on explosions.

An eyewitness in Aleppo's Hamdaniyeh neighborhood told AFP of a "huge explosion" and that people in the area could see "large flames in the distance".

Typically the first fear that Syrians have is that they are once again under attack by Israeli fighter jets, given this is a scenario which has played out literally hundreds of times over the past several years of conflict. There have been no initial statements describing what caused the disaster.

But several munitions and military warehouse accidents have occurred under the new Jolani government of late.

For example, in earlier September a Ministry of Defense weapons depot ignited and 14 people were killed.

Lately the country has been suffering extreme fuel prices amid efforts to get inflation under control, and amid stagnant wages and efforts to get the post-war economy back on track. Washington's recent dropping of Assad-era sanctions have yet to bear any immediate fruit, however.

Several days of protests across various cities have persisted, after the new rulers in Damascus abruptly removed fuel subsidies for the population. 

On September 13 the government decision saw diesel prices shoot up 40% and petrol prices by 28%, after not just years but decades of government regulated price controls and subsidies. 

Is there a covert sabotage campaign afoot? The Israelis have of late occupied southern Syria, and have engaged in operations to ensure Syria has no advanced or heavy weapons or munitions...

Already the country was smashed by proxy war and sweeping US-led sanctions, not to mention a decade-long US troop occupation of Syria's oil and gas fields in the northeast, which strangled the population, as part of efforts to overthrow secular Ba'ath leader Bashar al-Assad. 

Tyler Durden Mon, 09/21/2026 - 13:20

Bessent Hails "Very Successful" China Talks As Trump-Xi Summit Puts AI, Rare Earths And Energy On The Table

Bessent Hails "Very Successful" China Talks As Trump-Xi Summit Puts AI, Rare Earths And Energy On The Table

Treasury Secretary Scott Bessent emerged from roughly eight hours of talks with Chinese Vice Premier He Lifeng in New York on Sunday calling the meeting "very successful," with Washington and Beijing agreeing to new mechanisms covering trade and artificial intelligence just days before President Donald Trump hosts Chinese leader Xi Jinping in Washington.

Chinese Vice Premier He Lifeng, also a member of the Political Bureau of the Communist Party of China Central Committee, shakes hands with U.S. Treasury Secretary Scott Bessent, Sept. 20, 2026. Bai Xueqi/ | Xinhua News Agency | Getty Images

The talks, held at JPMorgan Chase headquarters, were intended to lay the groundwork for the Trump-Xi summit later this week. Working-level discussions are continuing as the two sides try to lock down whatever can be agreed before the leaders meet.

On paper, the immediate deliverables were relatively modest. In practice, the timing is anything but.

The two sides agreed to establish a U.S.-China AI dialogue, with Washington proposing a notification mechanism for AI incidents serious enough to reach the national-security level. Bessent framed the concept as an effort to move the world's two leading AI powers from opacity toward greater transparency and establish some common understanding of threats.

As we noted Friday, artificial intelligence was already emerging as one of the summit's most consequential issues, sitting alongside trade, semiconductors, Taiwan and rare earths. The two governments also moved to operationalize the previously proposed Board of Trade. U.S. Trade Representative Jamieson Greer said negotiators are looking for baskets of "non-sensitive" goods that could potentially be treated separately from future trade restrictions. Washington is considering lower-tech Chinese consumer goods, while Beijing is looking at U.S. energy, agricultural products and potentially medical devices.

There was no announced breakthrough, however, on some of the much larger outstanding disputes, including Chinese rare-earth flows, additional purchases of U.S. agricultural goods or Boeing aircraft. Advanced AI-chip export restrictions were also not part of Sunday's AI discussion.

Perhaps more revealing was how little Beijing itself said about AI. Xinhua described the talks as "candid, in-depth and constructive" before relegating the subject to the final sentence of its brief readout: "They also held dialogues on AI-related issues."

But Xi is also heading to Washington against a considerably different geopolitical backdrop than the one surrounding Trump's May visit to Beijing.

For starters, two of China's most attractive sources of discounted crude have been sharply constrained. Venezuela had become an important supplier of cheap heavy crude to Chinese refiners, but those flows fell dramatically after Washington's intervention in the country's oil trade earlier this year. As we noted at the time, Chinese refiners initially compensated by increasing purchases of heavily discounted Iranian barrels.

Meanwhile, the renewed U.S. campaign against Iran's oil exports disrupted shipments to Asia and left tens of millions of barrels in transit or floating storage. As we reported in July, roughly 63 million barrels of Iranian crude were at one point either moving or idling aboard tankers as sanctions pressure intensified. That does not mean China is running out of oil. Beijing accumulated large inventories and can source replacement barrels elsewhere, but the combination of reduced Venezuelan flows and disrupted Iranian supply has diminished some of the cheap-energy advantage Chinese refiners previously enjoyed.

Russia can fill part of that gap, but its own energy infrastructure remains under pressure from Ukrainian long-range attacks on refineries, export terminals and storage facilities. Earlier this month, Goldman estimated that the attacks had taken roughly 300,000 barrels per day of Russian refining capacity offline during August and early September. China has also encountered setbacks around another strategic chokepoint. Panama's Supreme Court voided Hong Kong-based CK Hutchison's concessions to operate the Balboa and Cristobal ports at opposite ends of the Panama Canal. As we noted in January, the ruling stripped the legal basis from a China-linked operator at two port facilities adjoining one of the world's most important shipping routes.

Then there is Greenland. Washington announced Friday that it had reached a security agreement intended to guarantee a long-term U.S. role on the island while preventing Russia, China and other non-NATO countries from establishing military bases there. The arrangement would strengthen the U.S. position in an Arctic region that both Washington and Beijing increasingly view as strategically important. On Monday, Denmark confirmed that the Trump-Greenland deal would boost arctic security. 

The political landscape across parts of Latin America has shifted as well. Reuters described Colombia's June election of Abelardo De La Espriella as part of a broader regional movement to the right that has also included Argentina, Chile, Ecuador, Bolivia, Panama and Peru.

Brazil is now the major unresolved contest. As we noted last week, Polymarket pricing recently moved in favor of Senator Flavio Bolsonaro over President Luiz Inacio Lula da Silva. Prediction-market prices are not opinion polls, however, and Monday's BTG Pactual/Nexus survey showed Lula at 46% and Bolsonaro at 45% in a hypothetical runoff, within the survey's margin of error.

Markets, meanwhile, entered the weekend already showing signs of pressure. According to Newsquawk, the U.S. 10-year Treasury yield closed Friday 6.5bps higher at 5.004%, while the two-year rose 7.5bps to 4.745%, producing a modest bear flattening of the curve.

Yet Xi is hardly arriving in Washington without leverage of his own.

China still controls roughly 70% of global rare-earth mining and more than 85% of refining capacity, leaving Beijing with substantial influence over supply chains critical to U.S. autos, semiconductors, aerospace and defense. As we noted this weekend, disrupted Chinese yttrium shipments alone have already forced Western aerospace, energy and semiconductor companies to scramble for alternatives. Beijing also retains enormous manufacturing capacity, large accumulated energy inventories and considerable purchasing power over everything from American agricultural commodities to aircraft.

In other words, Thursday's summit is taking shape less as a grand reconciliation than an attempt by two heavily intertwined rivals to fence off portions of the relationship before the next confrontation.

Washington arrives with greater influence over Venezuelan oil flows, intensified pressure on Iran's exports, a strengthened strategic position around Greenland and reduced China-linked influence around the Panama Canal, while the political map across portions of Latin America has changed considerably.

Beijing arrives with its own formidable counters: dominant critical-mineral supply chains, a resilient manufacturing and export base, substantial energy reserves and enormous leverage as a buyer of U.S. goods. Oh, and let's not forget - open-weight AI models that have completely upended the frontier AI model. 

Tyler Durden Mon, 09/21/2026 - 12:00

Key Events This Week: Trump-Xi Meeting, Fed Speakers, PMIs And Durables

Key Events This Week: Trump-Xi Meeting, Fed Speakers, PMIs And Durables

After an extremely busy week for central bank decisions, the week ahead brings a mix of economic data, even more central bank decisions, lots of Fed speak, and geopolitical events.

The first read of the September PMIs across the major economies on Wednesday should provide the most timely update on global growth momentum, while investors will also be watching policy decisions from the Norges Bank, Riksbank and SNB on Thursday with their hike probabilities according to futures at 62%, 21% and 5% respectively, according to Deutsche Bank.

Attention will also turn to the meeting between Presidents Trump and Xi on Thursday which will likely garner a lot of headlines. We also have opening week of the UN General Assembly debate in New York.

In the US, the focus will increasingly shift towards next Friday’s payrolls report, which will be the most important data release before the October FOMC meeting. Ahead of that, markets will be very keen to hear from a heavy schedule of Fed speakers throughout the week. These comments will frame last week’s FOMC meeting, where policymakers delivered a widely expected rate increase but signalled a more hawkish policy outlook. The updated projections showed a strong majority of officials anticipating further tightening, while Chair Warsh emphasized that the Committee still sees limited evidence that policy is meaningfully restrictive.  

Fed communication begins today with Chicago Fed President Goolsbee alongside the Chicago Fed National Activity Index. Tomorrow, investors receive the Philadelphia Fed non-manufacturing survey and the Richmond Fed manufacturing index. On the policy front, Fed Vice Chairs Williams and Jefferson are due to speak. Williams is viewed as one of the four officials who are still expected to see the Fed easing by the end of next year, so any hints on that outlook will be closely scrutinized.  

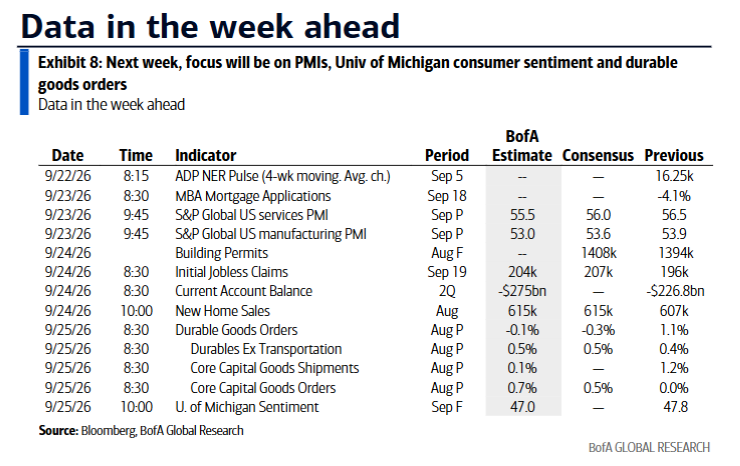
Wednesday’s main event will be the September flash PMIs. Economists expect the US manufacturing PMI to edge down to 53.6 from 53.9, while the services gauge is forecast to ease slightly to 55.9 from 56.5. Given the recent focus on AI-related investment and broader capex trends, these surveys will be watched closely for signs that business activity remains resilient. Fed Governor Barr is also due to speak. Investors will also be watching Wednesday's Treasury buyback announcement ahead of Thursday's 20-30yr operation, particularly after last month's decision to at least double the size of long-end buybacks.  

Thursday sees August new home sales and initial jobless claims. Last week continuing claims hit their lowest since January 2024. Fed speakers include Williams, Barkin, Hammack and Paulson, offering further opportunities for markets to assess where officials stand after last week’s hawkish meeting. Friday’s US durable goods report will be particularly important from a growth perspective. Our economists expect headline orders to rise by 0.6% month-on-month, with orders excluding transportation and core capital goods both expected to increase by 1.1%. The data should provide one of the clearest indications yet of whether the recent strength in business investment is being sustained. Williams and Hammack are also due to speak on Friday.  

Here is a day-by-day calendar, courtesy of DB

Day-by-day calendar of events

Monday September 21

  • Data: US August Chicago Fed national activity index, China 1-yr and 5-yr loan prime rates
  • Central banks: Fed's Goolsbee speaks, ECB’s Kazimir and Dolenc speak, BoC’s Macklem speaks

Tuesday September 22

  • Data: US September Philadelphia Fed non-manufacturing activity, Richmond Fed manufacturing index, business conditions, UK August public finances, Eurozone September consumer confidence
  • Central banks: Fed's Williams, Jefferson and Barkin speak, ECB's Nagel and Sleijpen speak
  • Auctions: US 2-yr Notes ($69bn)
  • Other: General debate of the UN’s General Assembly in New York (until September 28)

Wednesday September 23

  • Data: US, UK, Germany, France and Eurozone September PMIs
  • Central banks: Fed's Barr speaks, ECB's Vujcic, Zigman and Lane speak
  • Auctions: US 2-yr FRN (reopening, $28bn), 5-yr Notes ($70bn)
  • Other: OECD’s interim economic outlook

Thursday September 24

  • Data: US August new home sales, September Kansas City Fed manufacturing activity, Q2 current account balance, initial jobless claims, Japan September PMIs, Germany September Ifo survey, France September consumer confidence, business confidence, EU27 August new car registrations, Canada July retail sales, Australia labour force survey
  • Central banks: Central bank decisions in Norway, Sweden and Switzerland, Fed's Williams, Barkin, Hammack and Paulson speak, ECB’s economic bulletin, BoE’s Dhingra, Breeden and Lombardelli speak
  • Earnings: Costco
  • Auctions: US 7-yr Notes ($44bn)
  • Other: US President Trump and China’s President Xi meeting in the US

Friday September 25

  • Data: US August durable goods orders, September Kansas City Fed services activity, UK September GfK consumer confidence, Germany October GfK consumer confidence, Eurozone August M3
  • Central banks: Fed's Williams and Hammack speak, ECB's Vujcic speaks

Looking at just the US, The key economic data release this week is the durable goods report on Friday. There are many speaking engagements with Fed officials this week, including events with Governor Barr on Wednesday, President Paulson on Thursday, President Hammack on Thursday and Friday, and President Williams on Tuesday, Thursday, and Friday.

Monday, September 21 

  • There are no major economic data releases scheduled.
  • 06:30 AM Chicago Fed President Goolsbee (FOMC non-voter) speaks: Chicago Fed President Austan Goolsbee will speak about monetary policy at the Official Monetary and Financial Institutions Forum in London. Speech text and Q&A are expected. On August 28, Goolsbee said, “As I look at the inflation data, we were above the target, then it was going the wrong way, then we got a couple of months of more benign readings but that certainly doesn’t feel like we’re out of the woods.”

Tuesday, September 22 

  • There are no major economic data releases scheduled. 
  • 10:05 AM New York Fed President Williams speaks: New York Fed President John Williams will give keynote remarks during the New York Fed’s Treasury Market Conference. Speech text is expected. On September 2, Williams explained that “we are neither seeing second-round effects, nor unusual broadening of the effects of higher energy prices, and we are seeing well anchored inflation expectations,” though his comments came prior to September’s warmer CPI print.
  • 10:20 AM Fed Vice Chair Philip Jefferson speaks: Fed Vice Chair Philip Jefferson will speak at the New York Fed’s Treasury Market Conference on discount window modernization and Treasury market functioning. Speech text is expected.
  • 01:00 PM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will deliver a speech to the CFA Society Baltimore. Speech text and Q&A are expected.

Wednesday, September 23 

  • 09:45 AM S&P Global US manufacturing PMI, September preliminary (consensus 53.5, last 53.9); S&P Global US services PMI, September preliminary (consensus 56.0, last 56.5)
  • 10:05 AM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on housing at the Chicago Fed Community Development Summit. Speech text and Q&A are expected. On September 1, Barr said, “A series of shocks—from tariffs and then the conflict in the Middle East, as well as from the rapid AI buildout—has pushed us off course. And core non-housing services inflation remains elevated.” He also added that “with inflation above target for a protracted period, there is a risk of broader price pressures taking hold, a risk I am watching closely.”

Thursday, September 24 

  • 04:10 AM New York Fed President Williams speaks: New York Fed President John Williams will participate in a moderated discussion during the London Macro Policy Forum. Q&A is expected.
  • 08:00 AM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will participate in a fireside chat at The Economic Club of Washington D.C. Q&A is expected.
  • 08:30 AM Initial jobless claims, week ended September 19 (GS 200k, consensus 200k, last 196k): Continuing jobless claims, week ended September 12 (consensus 1,750k, last 1,730k)
  • 08:50 AM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will give opening remarks at the Inflation: Drivers and Dynamics Conference hosted by the Cleveland Fed and the European Central Bank. Speech text is expected. On September 4, Hammack stated, “Both the hard data and the anecdotes are telling me the same thing: policy is not restrictive. Inflation is too high—and the longer it stays above our objective, the harder it will be to bring it back down…Right now, what I’m hearing is that it is time to act.”
  • 10:00 AM New home sales, August (GS +0.7%, consensus +1.3%, last -10.5%)
  • 10:10 AM Philadelphia Fed President Paulson (FOMC voter) speaks: Philadelphia Fed President Anna Paulson will speak about the economic outlook at the Tenth Annual Fintech Conference hosted by the Philadelphia Fed. Speech text is expected. On August 4, Paulson explained that she sees “two plausible scenarios for how current policy is affecting inflation.” One is that “the current setting of the federal funds rate is mildly restrictive and this will bring inflation to 2 percent in an acceptable time frame” and the other is that “current policy is not restrictive enough to deliver our target rate of 2 percent inflation.”

Friday, September 25 

  • 05:15 AM New York Fed President Williams speaks: New York Fed President Williams will participate in a policy panel during the 6th Monetary Economics Conference in Oxford, UK. Q&A is expected.
  • 08:30 AM Durable goods orders, August preliminary (GS -1.0%, consensus -0.3%, last +1.1%); Durable goods orders ex-transportation, August preliminary (GS +0.6%, consensus +0.6%, last +0.4%); Core capital goods orders, August preliminary (GS +0.5%, consensus +0.7%, last flat); Core capital goods shipments, August preliminary (GS +0.3%, consensus +0.7%, last +1.2%): We estimate that durable goods orders declined 1.0% in the preliminary August report (month-over-month, seasonally adjusted) based on our tracking of commercial aircraft orders. We forecast a 0.5% increase in core capital goods orders—reflecting continued strength in the new orders components of manufacturing surveys in August—and a 0.3% increase in core capital goods shipments—reflecting the continued increase in core capital goods orders in recent months.
  • 10:00 AM University of Michigan consumer sentiment, September final (GS 47.5, consensus 47.5, last 47.8): University of Michigan 5-10-year inflation expectations, September final (GS 3.4%, last 3.4%)
  • 2:00 PM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will participate in a policy panel discussion at the Inflation: Drivers and Dynamics Conference hosted by the Cleveland Fed and the European Central Bank. Q&A is expected.

Source: DB, Goldman

Tyler Durden Mon, 09/21/2026 - 10:55

Another Tanker Struck In Strait Of Hormuz As Iran's President Heads To NY

Another Tanker Struck In Strait Of Hormuz As Iran's President Heads To NY

Just as the Iranian delegation of President Masoud Pezeshkian is set to fly to New York City for this week's UN General Assembly, where it's expected that the Iranians could be engaged in some sideline diplomacy with the White House, another tanker incident has unfolded off in the Persian Gulf area.

The UK Maritime Trade Operations (UKMTO) agency is reporting Monday that an oil tanker has been "struck by an unknown projectile" while on an inbound transit route in the Strait of Hormuz.

As a result of the attack under as yet unknown circumstances two crew members suffered "minor injuries". But the vessel is reportedly in good enough shape to continue on to its next port of call.

It may have been the result of a small drone, given what appears to only be light damage or an incident not significant enough to put the vessel out of commission. Tehran is seeking to keep its leverage and 'control' over the vital energy transit waterway.

"Vessels are advised to transit with caution and report any suspicious activity to UKMTO," the reiterated. 

But oil prices have slid to their lowest in 11 days amid optimism that Iran's Pezeshkian could hold talks with US officials, or else could engage in renewed diplomacy via mediators on the UN sidelines.

Trump in a Sunday Fox News interview actually indicated openness to a meeting with Pezeshkian, in a first of the war. Trump was asked about the high level UN meeting and surprisingly he went so far as to say he would "probably be open" to meeting with the Iranian president.

Still, this was all coupled with threats. In Trump's mind, there seem to be three options on the table, or as he put it--"to obliterate Iran, letting it rot economically or reach a deal."

Tim Waterer, chief market analyst at KCM Trade, has observed, "It seems that a degree of risk premium is being removed from oil prices on hopes that a diplomatic path to de-escalate the US-Iran war may arrive this week."

Meanwhile, a regional US commander has claimed that oil and liquefied natural gas shipments through the the Strait of Hormuz have reached their highest level in six months. This is being hailed as a sign that US naval protection and mine-clearing efforts could finally be paying off.

Iran has meanwhile over the weekend once again warned US allies in the region that they'll be considered "complicit" if the US resumes it military assault on the Islamic Republic. The Iranian military HQ stated that "any mistakes will result in painful attacks."

Tehran further indicated Sunday that it is still awaiting Trump's response to its conditions for ending the war. Mohammad Bagher Ghalibaf confirmed to AFP that Iran's demands were sent to Washington via the Qataris. The US could decide to convey its counter offer while the Pezeshkian delegation is in town.

Tyler Durden Mon, 09/21/2026 - 10:45

US Futures Rise, Near All-Time High, As Oil, Yields Drop On US-China Diplomacy Optimism

US Futures Rise, Near All-Time High, As Oil, Yields Drop On US-China Diplomacy Optimism

US futures are higher driven by Trump / Xi optimism around AI, Middle East, and trade with Middle East kinetic headlines over the weekend reflecting a pause to escalation. Sentiment was lifted by signs of progress on geopolitical issues: it’s a big week for talks, with Trump set for a summit with China’s Xi Jinping on Thursday and a possibility of talks with Iran’s president at the UN General Assembly. As of 8:00am ET, S&P futures are up 0.7%, rising to 7,770 and less than 1% from all time highs, as Nasdaq futures gain 1.1%, with tech strength on full display in APAC trade and also leading in premarket US trading with broad-based strength across Semis, Memory, and Mag7. Cyclicals ex-Energy are leading Defensives with the AI theme boosting Tech / Industrials within Cyclicals. Within Defensives, both healthcare and staples have pockets of strength as today looks like a broad-based rally in both the SPX and within Tech. WTI is below $100, dropping for a fourth day, fuel prices are lower, while bond traders reckon the Fed will succeed in its fight against inflation helping drive bond yields lower as the yield curve bull flattens, as the USD drops to session lows. This is bidding up risk assets with Equities leading. The Fed’s Goolsbee speaks 6.30am with previous speakers Fri / Sun offering a hawkish view which reiterates Warsh’s key points. According to JPM, given the macro and earnings strength, the market may be underpricing the number of hikes through YE27. There is little on today's calendar: we get the Aug Chicago Fed Nat Activity Index (est. -0.04) at 8:30am ET.

In premarket trading, Mag 7 stocks are all higher: Meta climbs about 2% after shares in the social media giant sold off on Friday. Tesla +1.5%, Alphabet +0.3%, Nvidia +0.8%, Amazon +0.7%, Microsoft +0.4%, Apple unchanged.

  • Cryptocurrency-linked stocks are rallying as Bitcoin trades above $84,000, near an eight-month high.
  • Accenture (ACN) gains 4% after Anthropic partnered with the technology consulting company to test the safety of its advanced artificial intelligence models.
  • Alkermes (ALKS) climbs 8% after announcing positive Phase 1b results for ALKS 7290 in adults With attention-deficit hyperactivity disorder.
  • Arhaus (ARHS) rises 2% after Jefferies upgraded the furniture company to buy, writing that it has “newfound optimism on the retailer’s strategy to elevate brand awareness” and improve market share.
  • Candel Therapeutics (CADL) gains 6% after BofA upgraded the biotech company to buy, citing optimism about a prostate cancer treatment.
  • Ciena (CIEN) rises 5% after Evercore ISI raised the recommendation to outperform, citing the way data centers are boosting demand for optical networking equipment.
  • Critical Metals (CRML) soars 24% after President Donald Trump said the he reached an agreement with Denmark over Greenland that would give the US “permanent control over security” of the Arctic island. In April, Critical Metals agreed to acquire European Lithium Ltd., giving it full ownership of a rare earth project in Greenland.
  • Securitize (SECZ) rises 8% after Cantor Fitzgerald initiated coverage with a recommendation of overweight as it sees the tokenization company benefiting from recent Securities and Exchange Commission guidance.
  • Warner Bros. (WBD) is up 7% and Paramount Skydance (PSKY) is up 6% as the latter is in settlement talks with California officials over its planned acquisition of the former.

In other corporate news, settlement talks between Paramount Skydance and California officials over the planned acquisition of Warner Bros. Discovery are said to include a financial penalty if the company fails to make good on a promise to distribute 30 films per year in theaters. Nscale, a developer of AI data centers that counts Nvidia and Microsoft among its partners, filed for an IPO. Novo Nordisk shares fell after the maker of Ozempic and Wegovy outlined its 2030 strategic ambitions, targeting revenue CAGR in line with industry peers. SoftBank is seeking the equivalent of more than $11 billion in what would be one of the biggest junk bond deals ever to fund OpenAI investments in OpenAI

Global markets are firmer across the board, helped by lower energy prices despite heightened geopolitical tensions over the weekend. Brent is down about 2% as diplomatic efforts to resolve the conflict are parsed, while oil and LNG flows through Hormuz hit a six-month high. The Houthis said they attacked sensitive sites in Riyadh and an Aramco facility in Yanbu over the weekend, while US President Trump reportedly said that he is thinking of "blowing up" all of Iran. One source of potential optimism is the commentary following US-China trade talks, with US Treasury Secretary Bessent describing talks as "successful" on trade and AI, while they agreed to hold another meeting on AI dialogue. For the Trump-Xi meeting - which is Xi’s first trip to the US in three years - trade, AI, critical minerals, industrial capacity, Taiwan, Ukraine and the Middle East are all on the bingo card.

The “feedback from the talks between China and the US is feeding a positive narrative as the week begins,” said Alexandre Baradez, chief market analyst at IG in Paris. “That said, for me oil prices remain the key driver.”

“The market doesn’t really need any grand bargain,” says Panmure Liberum’s Mark Taylor, who thinks signs of “amicable agreement to manage tensions” will be enough to support risk appetite. “However, if fresh tariff threats, tech restrictions or hostile commentary resurface, it could quickly revive the trade-war risk aversion,” he adds.

For today, oil is also a major risk-on driver. In a sign that US naval protection and mine-clearing efforts in the Strait of Hormuz were paying off, a regional US commander said oil and liquefied natural gas shipments through the waterway reached their highest level in six months, which almost helped push Brent below $100. Trump told Fox News he would “probably” be open to meeting his Iranian counterpart on the sidelines of the UN assembly this week.

Meanwhile, as BBG notes, the AI debate continues to rumble on, with the narrative to positive over the weekend, despite some news reports of a looming drop in memory prices. South Korea’s chip exports surged nearly 260% year-on-year in the first 20 days of September, to a record $34.1 billion. Accenture shares surged after it was chosen by Anthropic to test the safety of AI models, and SocGen said AI could help it make substantial cost savings.

But there’s still a lot of caution. Citi’s CEO said companies are racing to build up their defenses as AI models become more powerful and risk spurring cyber attacks. Today’s Big Take looks at how AI risk is making CIOs nervous. Elsewhere, opposition to data centers continues to mount: Data Center Watch said some 45 projects worth $68 billion were blocked or delayed by local pushback during the second quarter.

“AI is clearly becoming the next major area of strategic competition, but the fact that both sides are at least discussing a mechanism for dialogue is constructive,” said Mohit Mirpuri, senior partner at SGMC Capital Pte. “Markets don’t necessarily need Trump and Xi to resolve all their differences on Thursday, they mainly need reassurance that those differences remain manageable and don’t spill back into another trade or technology shock.”

And then there is inflation: price pressures continue to show up, with US retail diesel prices topping $6.50 a gallon for the first time, copper holding gains and food shock risks making headlines. Fed’s Kashkari said inflation remains too high and that pressures have broadened beyond the oil-price shock of the Iran war.

European shares gain as cooling oil and gas prices ease inflation concerns, while optimism ahead of this week’s China-US summit also lifts sentiment. The Stoxx 600 rises 0.9% with tech outperforming while healthcare falls after Novo Nordisk disappointed investors who were hoping to see more robust sales targets at the company’s capital markets day. Here are some of the biggest movers on Monday:

  • Kuehne+Nagel shares rise as much as 6% following the freight transportation firm’s collaboration with US tech behemoth Amazon, which will include providing assistance on logistics services and infrastructure for Amazon Web Services.
  • Lundbeck gains as much as 4.6% after UBS raised its recommendation to buy from neutral, saying the company is potentially on track to turn around its R&D activities, and notes several upcoming key trial readouts.
  • Lotus Bakeries gains as much as 6.2% after UBS raised its recommendation to buy from neutral, saying the company is potentially on track to turn around its R&D activities, and notes several upcoming key trial readouts
  • Huber+Suhner shares rise as much as 5.6%, recouping the losses booked on Friday after the maker of telecommunication products held its capital markets day.
  • Industrie De Nora shares rise as much as 5.9%, extending a rally after Italy agreed to cover full costs for its Gigafactory project, according to a statement.
  • Novo shares fall as much as 7.7% after the Danish firm outlined its 2030 strategic ambitions at its Capital Markets Day in London.
  • Ayvens shares drop as much as 6.2% after the fleet management company outlined its new 2029 strategic plan. Jefferies said the new targets are “more realistic than ambitious.”
  • VW shares fall as much as 2.6% after Kepler Cheuvreux downgraded the German carmaker to hold from buy citing a profit warning that offset positives from a restructuring program.
  • Craneware shares fall as much as 25% after the healthcare software company cut its revenue guidance for FY27 amid disruption caused by a cyber security incident.
  • Ipsen drops as much as 7.8% after Amneal Pharmaceuticals received FDA approval for its generic version of somatuline.

Asian stocks advanced as an extended rally in semiconductor shares and a decline in oil prices supported investor sentiment. The MSCI Asia Pacific Index rose more than 1%, heading for a fourth straight session of gains. Samsung Electronics, TSMC and MediaTek were the top contributors to the gauge’s increase. South Korea’s Kospi was the best performer in the region. Markets in Japan were shut for a holiday. “Friday’s Wall Street session has aided sentiment in the AI names early, with the US semiconductor index rising close to 3%, led by the memory names as contract prices keep rising,” said Josh Gilbert, lead APAC analyst at Etoro. “Korea and Taiwan carry the most exposure to that, which is why we’ve seen buyers return to Asia, with flows coming back into the region after a run of selling.” The MSCI Asia Pacific Index is up about 23% so far this year. However, the gauge has risen just 0.3% so far in September as the Federal Reserve’s hawkish rate hike, persistent inflation concerns, elevated bond yields and growing unease over the

In FX, the Bloomberg Dollar Spot Index is near unchanged. USD/JPY is back on a 157 handle after Friday’s reported rate check.

In rates, treasuries trade near session highs in early US session, supported by steeper gains across European bond markets as oil prices slide, leaving Brent crude on track for the longest run of declines since June. Energy prices are easing amid diplomatic efforts to end the US-Iran war and signs cargoes are still moving through the Strait of Hormuz. Treasury coupon auctions of 2-, 5- and 7-year notes commence Tuesday. US yields are 3bp to 4bp richer across the curve with front-end lagging slightly, flattening 2s10s and 2s5s spreads by ~1.5bp. 10-year is around 4.955% with bunds and gilts in the sector outperforming by 1.5bp and 3.5bp. In Europe, French bonds outperform, moving the French-German 10-year yield spread back below 100bp; 105bps spread reached Friday was the widest since 2012. IG dollar issuance slate includes a few deals already.  Dealers expect around $40 billion of new issuance this week, possibly including Sysco Corp., which is preparing a roughly $17 billion bond sale. This week’s Treasury note auctions include $69 billion 2-year Tuesday, $70 billion 5-year Wednesday and $44 billion 7-year Thursday.

are on the decline with the US 10-year borrowing cost down 4bps at 4.96% - note, cash trade was closed overnight due to the Japanese market holiday. Yields in the UK and Germany are also lower, with the pullback in energy outweighing mounting political risks for the latter. French 10-year bonds are outperforming after being trounced on Friday and the OAT-bund yield spread is back below 100 basis points.

In commodities, WTI crude futures are down almost 3%, Brent is down more than 2% as diplomatic efforts to resolve the conflict are parsed, while oil and LNG flows through Hormuz hit a six-month high. Spot gold is down 0.8%. The crypto rally is extending with Bitcoin up 4.7% and at levels not seen since January. 

US economic data slate includes August Chicago Fed national activity index at 8:30 a.m. Fed speaker slate is blank for Monday.

Market Snapshot
Top Overnight News

  • Oil prices slid to their lowest in 11 days on Monday as investors ‌hoped for diplomatic progress on the Iran war due to this week's UN meeting, and eyed a partial recovery in shipments from Saudi Arabia. Brent crude futures and US West Texas Intermediate crude touched their lowest since September 10 earlier on Monday. The Brent contract for November was at $101.75 a barrel at 0859 GMT, down $2.12, or 2%. RTRS
  • The Iran war has created a new shortage on the oil market. This time the scarce commodity isn’t just crude—it is the ships that carry it. Drone attacks that shut Saudi Arabia’s bypass pipeline earlier this month have forced more crude back through the Strait of Hormuz and onto a tanker fleet already stretched thin. WSJ
  • The US and China have agreed to set up an AI dialogue ahead of a high-stakes summit on Thursday in Washington between Donald Trump and Xi Jinping. US Treasury secretary Scott Bessent said the two sides had negotiated the creation of an AI dialogue mechanism, which was floated when Trump met Xi in Beijing in May, in talks with Chinese vice-premier He Lifeng in New York on Sunday. FT
  • China is more than halfway toward its pledge to buy 25 million tons of US soybeans this year, but a commitment to purchase at least another $17 billion of American farm products has largely stalled. BBG
  • OpenAI projects it will burn through almost $280bn by the end of 2030, highlighting its huge long-term funding needs as the AI company pushes for a valuation of more than $1.2tn in fresh investment talks. The company expects negative free cash flow of $278bn over five years from 2026 to 2030 as it invests aggressively to expand its access to computing power. FT
  • Friedrich Merz vowed to stay on as German chancellor after his CDU suffered heavy losses in state elections. The party won just 4.9% in Mecklenburg-Western Pomerania, shutting it out of a regional assembly for the first time in the country’s postwar history. BBG
  • SoftBank’s seeking the equivalent of over $11 billion for AI investments in what would be one of the biggest junk bond deals ever, people familiar said. BBG
  • Wall Street banks are expecting the US to borrow up to $1tn over the next year by selling short-term Treasury bills as part of a growing dependence on quick-maturing debt that leaves Washington vulnerable to rising interest rates. FT
  • The Fed’s Austan Goolsbee warned the central bank cannot ignore repeated and persistent supply shocks, and must respond in a way that may cause economic hardship. BBG
  • Investors are betting on a Fed win the inflation fight, turning bullish on front-end Treasuries. Two-year yields remain well above the central bank’s range, offering scope for the securities to rally if inflation eases or rate hikes are less than priced. BBG

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were ultimately mixed, but with cautious gains seen for most of the region ahead of this week's key meetings in the US, including the UN General Assembly and the Trump-Xi summit, while there are also thinned conditions with the closure of Japanese markets through to Wednesday. ASX 200 was uneventful amid mixed M&A related headlines and further RBA rate hike calls, with CBA bringing forward its rate hike call to September from November, while ANZ expects hikes in both September and November. KOSPI outperformed as tech stocks took impetus from the advances in the Nasdaq last Friday. Hang Seng and Shanghai Comp were mildly higher ahead of the Trump-Xi summit this week and after US and Chinese officials held talks in New York ahead of the leaders' meeting, with China's top trade negotiator describing the discussions as 'not bad', while state media noted the sides had frank, in-depth and constructive exchanges on important economic and trade issues of mutual concern, as well as holding dialogue on AI-related issues.

Top Asian News

  • Japan's government will work with major machinery manufacturers to collect machine-learning data for physical AI applications such as autonomous robots and assigning unique IDs to factory equipment to enable cross-vendor data aggregation, according to Nikkei.
  • Japan is poised to ease restrictions on regional bank loans for AI and energy projects, Nikkei reported.
  • China's CPC Politburo met to discuss draft documents to be submitted to the Fifth Plenary Session (26th-29th October), with Chinese President Xi presiding.

European bourses (STOXX 600 +1.0%) are firmer across the board, helped by lower energy prices despite heightened geopolitical tensions over the weekend. The Houthis said they attacked sensitive sites in Riyadh and an Aramco facility in Yanbu over the weekend, while US President Trump reportedly said that he is thinking of "blowing up" all of Iran. One source of potential optimism is the commentary following US-China trade talks, with US Treasury Secretary Bessent describing talks as "successful" on trade and AI, while they agreed to hold another meeting on AI dialogue. Sectors highlight the positive bias. Tech tops the sector pile, with Industrials and Basic Resources following closely behind. To the downside is Health Care, with Optimised Personal Care and Energy rounding out the sector laggards. Explaining the underperformance in Health Care is the downbeat reaction in Novo shares (-5%) after they announced their 2030 ambitions. The drugmaker plans to launch over 5 blockbusters by the end of 2030 and targets pipeline sales of over DKK 150bln in 2035.

Top European News

  • German Chancellor Merz vowed to stay on despite a ‘disaster’ in regional elections with partial results showing his CDU at just under the 5% threshold for parliamentary representation in Mecklenburg-Vorpommern, while the centre-left SPD is projected as 35.5% of votes and the far-right AfD is expected to get 37.0% of votes, according to exit polls. Merz's conservatives are projected at 20% of votes in the Berlin state election, while the Left Party is seen at 24.5%, SPD is seen at 12%, and AfD is seen at 16% in Berlin.
  • Scope downgraded France’s long-term ratings to 'A+' from 'AA-' and revised the outlook to stable; DBRS affirmed France at 'AA', lowered the French outlook to negative.

FX

  • Snapshot: G10s are mixed against a flat USD this morning. The Antipodeans are mildly firmer, benefiting from the risk tone, whilst the Loonie and JPY are the marginal laggards.
  • DXY currently holds within 100.20 to 100.37 range, and towards the highs made post-FOMC last week. Newsflow for the Dollar has been lacking this morning; oil prices are slipping off highs, despite ongoing supply disruptions, as attention turns to the UN General Assembly Council this week, alongside the summit between President Trump and Xi. The current mood between the two is positive; Trump recently suggested that he and Xi get on “very well”, whilst Treasury Sec Bessent suggested they had a very successful engagement with the Chinese on trade and AI.
  • JPY is a touch lower this morning, giving back some of the strength made last Friday. The Nikkei reported that the BoJ conducted a “rate check” on that Friday, which helped curtail some of JPY pressure seen following the Bank’s dovishly perceived rate decision. This makes evident that the Japanese officials remain ready and active in the market to keep USD/JPY from approaching the 160.00 mark once again. If market expectations of a Fed-BoJ divergence continue to grow, then it may prove to be difficult for Japan to significantly prevent another bout of upside in the pair. Do note that Japan is away on holiday and returns on Thursday; as such, the lower-volume environment could provide a decent opportunity for the MoF to enact some intervention.
  • EUR is essentially flat vs USD, despite political uncertainty from within the region. Firstly, two regional elections were held in Germany over the weekend; the ruling CDU party performed terribly, falling short of the 5% threshold to enter state parliament in one state. There is now mounting pressure on current Chancellor Merz to resign, though he announced that he will stay in office and “fight on”. The state election results point out the issues the German population is currently facing, but for now, it will remain a regional problem. It will likely have little impact on the federal government itself; as such, the EUR is little changed.

Fixed Income

  • USTs (+8 ticks) are stronger this morning, benefiting from 1) falling energy prices and 2) markets awaiting the US-China meeting at the White House on Thursday. On the first point, supply disruptions remain, and Trump recently said he is thinking of “blowing up” all of Iran. It seems as if markets are shifting their attention to the UNGA this week, with Trump reportedly set to meet Gulf leaders and then President Xi. There may be growing hopes that a framework agreement/deal can be ironed out; recent reports have noted that Pakistan’s Interior Minister has travelled to Iran.
  • Yields are lower across the curve, with very slight underperformance at the belly. The US 10-year (4.96%) has now slipped below the key 5.00% mark, given the aforementioned energy dynamics. A constructive UNGA mood and/or geopolitical progress could help the 10-year continue to slip to near-term lows, with 4.92% a likely area of support (low from 18 Sep).
  • Gilts (+72 ticks) outperform vs peers, and currently hold towards the upper end of an 85.28 to 85.76 range. UK-specific news flow has been focused on pre-budget speculation around housing and CGT, but with action in UK paper today ultimately driven by energy dynamics. On trade relations, UK PM Burnham is set to meet US President Trump this week. Reports suggest that the talks between the pair will focus on the Middle East, energy costs and the ongoing Russia-Ukraine conflict.
  • EGBs dominate the fixed income space this morning. Bunds after the latest state parliamentary elections, and OATs after sovereign updates and the latest fiscal disclosure. However, despite these points, EGBs are firmer with the marked energy pullback providing relief and some caveats/points to look to with reference to Bunds and OATs specifically.
  • For Germany, the Grand Coalition’s CDU had a disaster in the two elections, while their SPD partner fared somewhat better. Within Mecklenburg-Western Pomerania, the CDU are set to come in below the 5% threshold to enter state parliament, while AfD won with 38.2% but PSD a near second on 35.5%; a point that provides some relief, as there is no appetite to work with AfD, and thus SPD will likely lead a SPD-Green-Die Linke combination of some description in the region. For now, we await the final results of Mecklenburg-Western Pomerania to confirm if CDU has missed the threshold. Thereafter, we look for signs of more pressure on Chancellor Merz and whether the Grand Coalition may look for an alternative to him, a ‘Kanzlertausch’, given the September regional election outcomes and his personal low approval rating.
  • Turning to OATs, firstly digesting the trend cut to negative from stable at DBRS, due to “the risk of the government failing to address fiscal imbalances is increasing, leading to a continued rise in the government debt ratio over the medium term”. Additionally, Scope cut France to A+ (prev. AA-), primarily due to the deteriorating fiscal outlook.

Commodities

  • WTI Nov and Brent Dec futures are softer after initially advancing at the open on weekend escalation, including a Houthi attack on a Saudi Aramco facility in Yanbu and Trump reportedly saying he was considering “blowing up” Iran. Prices subsequently reversed as the immediate escalation failed to develop further and Trump also signalled openness to meeting Iran’s President. Further, there may be some hopes that the Trump-Xi meeting this week may help simmer down some geopolitical tensions in the Middle East. This morning’s picture remains mixed in terms of newsflow: the IRGC said it shot down a US MQ-1 drone over Hormuz and warned the war “is not over”, while Pakistan’s Interior Minister is heading to Tehran, with conflicting reports over whether the trip involves US-Iran mediation. WTI Nov trades close to the bottom of a USD 93.46-97.22/bbl range, while Brent Dec nearer to the lower end of a USD 96.97-100.22/bbl range. Dutch TTF is sharply softer (-3.8%) alongside the broader pullback in the energy complex within a EUR 76.85-80.55/MWh range.
  • Precious metals are softer as the Dollar remains firm in the face of lower oil prices. Spot gold trades around USD 4,350/oz within a USD 4,342-4,383/oz range, and with the 100 DMA at USD 4,319/oz today. Spot silver similarly trades flat on either side of its 100 DMA (USD 66.40/oz) in a narrow USD 65.73-67.05/oz parameter.
  • Base metals are firmer despite the cautious broader backdrop, extending some of last week’s gains. COMEX copper trades near the upper end of a USD 6.60-6.66/lb range, and 3M LME copper trades towards the top end of a USD 14,540.50-14,688.00/t parameter, with the complex supported by the generally positive tone across Chinese markets ahead of the Trump-Xi summit and after constructive US-China trade discussions in New York.
  • Kazakhstan oil shipments to Ust-Luga were recorded at 200k metric tons in August, according to Interfax.
  • French Finance Minister Lescure said France’s strategic oil stocks are full.
  • Naftogaz said ORLEN (PKN PW) will supply up to USD 500mln of petroleum products to Ukraine to stabilise the market and deliver three LNG cargoes in Q1 2027.
  • South Africa's Pretoria is reportedly looking to leverage its role as a platinum supplier to help integrate into the US and China, Semafor reported.

Trade/Tariffs

  • US Treasury Secretary Bessent said they had a very successful engagement with the Chinese on trade and AI, while they agreed to hold another meeting on AI dialogue and the US suggested a notification system between the two countries. Bessent separately commented that he is likely to meet the Chinese delegation in two months and they discussed extending the trade truce, although no pact was reached, according to FT citing an interview following Bessent's meeting with Vice Premier He Lifeng.
  • USTR Greer said they implemented a board of trade, with the US and Chinese teams to continue working on a board of trade agreement, while the board of trade from the Chinese side is likely to include consumer goods and low-tech items.
  • China's top trade negotiator Li said trade talks are ‘not bad’ and that talks will continue on Monday among the working group, while he confirmed that both sides discussed AI along with trade and investment.
  • Chinese state media noted that China and the US conducted frank, in-depth and constructive exchanges on important economic and trade issues of mutual concern, while they held dialogue on issues related to AI.
  • US and China were reported on Friday to be discussing cutting tariffs on US LNG ahead of Xi's visit, with potential USD 30bln reciprocal tariff cuts, while the visit could bring broader energy and agricultural deals.
  • China reportedly purchases more US soy cargoes ahead of the President Trump-Xi meeting.
  • Indian Trade Minister said a trade agreement with New Zealand will provide duty-free access to New Zealand for 100% of India's exports.

Central Banks

  • Fed's Kashkari (2026 voter) said inflation remains too high and that price pressures have expanded beyond the oil-price shock from the Iran war and are affecting the broader economy.

Geopolitics: Iran

  • US President Donald Trump reportedly said on Sunday that he is thinking of "blowing up" all of Iran as he left the Camp David retreat a day early to return to the White House, while Fox News reporter Yungst said Trump told him during a phone call that "very big things are going to be happening" soon. Furthermore, Trump said his options are ‘wiping out’ the regime, letting it ‘rot economically’ under naval blockade, or striking a deal, according to Fox News and The Telegraph.
  • US President Trump said on Friday that the Iran War will end soon, adding that once the war ends, US gasoline prices will revert to prior levels and could even fall further. US President Trump confirmed on Friday the US is talking to the Houthis, saying they want a deal, while adding "we'll see" on whether to annihilate Iran.
  • US CENTCOM commander Cooper said oil and LNG shipments through the Strait of Hormuz in the past two weeks reached the highest levels in six months. More US troops had reportedly died amid the Iran war than the Pentagon disclosed publicly, according to a report on Friday in the Washington Post.
  • Pakistani Interior Minister travelled to Iran today, IRNA reported. Tasnim later reported that the trip is unrelated to Iran-US matters and will focus on bilateral relations and cooperation, with the report adding that Pakistan is not carrying a message between Iran and the US.
  • Iranian officials conveyed their conditions to mediators for re-engaging in negotiations for ending the war with the US, while the conditions include ending the war on all fronts and the naval blockade, as well as unfreezing Iranian funds and they also want an end to the war between Saudi Arabia and Yemeni Houthis.
  • IRGC spokesman said all of the US' superior technologies pale in comparison to Iran's offensive and defensive capabilities, adding that Tehran are defining the new regime in the region, not America, and the war is not over and continues. The spokesman added that the IRGC has prepared itself for a long-term war and that they have new targets and weapons ready if the US launches a new attack.
  • IRGC said it shot down a US MQ-1 drone over the Strait of Hormuz.
  • UKMTO received a report of an incident involving a vessel transiting the Strait of Hormuz, reported at 07:30 UTC. A tanker conducting an inbound transit was struck by an unknown projectile.
  • Qatar's PM Al-Thani said Gulf states need to cooperate to restore regional stability and help reach a settlement between the US and Iran. It was separately reported that Qatar's Energy Minister said US Treasury Secretary Bessent is "wrong" in saying that the strategic Strait of Hormuz will be worthless in two years.

Geopolitics: Ukraine

  • Russia's Press Secretary Peskov said there have been no progress in negotiations on Ukraine yet but remains open to further talks, IFX reported.
  • UK Burnham hopes to build bridges with US President Trump at their first meeting and wants to press the case for the US to help Ukraine with air-defence systems.
  • Moscow Oil Refinery was hit during a drone attack that was part of Ukraine's largest barrage this year.

Geopolitics: Other

  • US, Denmark and Greenland reached a security agreement that expands the US’s role on the Arctic island to end the row that threatened NATO.
  • North Korea launched two missiles off its eastern coast on Sunday. It was also reported that North Korea rejected an IAEA resolution on its nuclear program and vowed to keep its status as a nuclear-armed state.
  • Japanese Defence Minister Koizumi and US Defence Secretary Hegseth agreed in a phone call to further strengthen security ties.

US Event Calendar

  • 8:30 am: Aug Chicago Fed Nat Activity Index, est. -0.04, prior -0.08

DB's Jim Reid concludes the overnight wrap

For 2026 standards, its been a relatively quiet weekend news wise but yesterday saw more, albeit expected, heavy defeats for the ruling CDU in two German state elections with a surge in support for the far right AfD in one and the far left Die Linke in the other. Chancellor Merz called the early results "a disaster" but vowed to press on with reforms. In Mecklenburg-Western Pomerania, the AfD won 38.3% of the vote, roughly double its support from the previous election in 2021 and enough to make it the largest party in the state even if a coalition to keep them out of power is likely. The shock was that the CDU didn't even make the 5% threshold to enter parliament for the first time in the country’s post-World War II history. So this will create huge amounts of political pressure on the Chancellor and raise questions about the reform agenda.  

Meanwhile, in Berlin, the Left Party (Die Linke) emerged as the biggest force with 25.3%, ahead of the CDU and Greens. The mainstream parties seem to be caught in a continued pincer movement. On the far-right the AfD continues to gain support on anti-immigration and anti-establishment themes, particularly in eastern Germany, while the Left appears to have capitalised on concerns over housing affordability, living costs and social inequality. For markets, the immediate implication is not a change in national policy, but a further weakening of Germany’s political centre and another reminder that the forces driving political polarisation across Europe remain alive and well.

Also over the weekend, President Trump announced that the US, Denmark and Greenland had reached an agreement that would allow a significant expansion of the US military presence on the island, with Trump describing the deal as giving the US “permanent control over security” in Greenland. The agreement falls well short of Trump’s earlier ambitions to acquire Greenland, while Danish and Greenlandic leaders stressed that it explicitly recognises Greenland’s right to self-determination and Danish sovereignty. Taken at face value, if this agreement holds it actually reduces event risk, as the Greenland issue could easily have come back to be a high tension hotspot in the months ahead.

Overnight in Asia, equity markets are advancing led by technology shares supported by optimism from US-China trade talks ahead of the much anticipated summit between President Trump and President Xi Jinping later this week. Across the region, the KOSPI (+1.79%) is outperforming with Japanese markets closed for the three-day Silver Week holiday. Elsewhere, the Hang Seng (+0.57%), the Shanghai Composite (+0.55%) and the CSI 300 (+0.42%) are all trading moderately higher. S&P 500 (+0.41%), NASDAQ 100 (+0.54%) and Stoxx (+0.55%) futures are all higher. Brent is -2.21% lower at $101.65/bbl which is helping. It's been above $100/bbl again since September 9th, and although US cash Treasury trading hasn't commenced due to the Japanese holiday, US and European bond futures are all notably higher this morning.  

Moving on, the week ahead brings a mix of economic data, central bank decisions, lots of Fed speak, and geopolitical events. The first read of the September PMIs across the major economies on Wednesday should provide the most timely update on global growth momentum, while investors will also be watching policy decisions from the Norges Bank, Riksbank and SNB on Thursday with their hike probabilities according to futures at 62%, 21% and 5% respectively. Elsewhere, attention will turn to the meeting between Presidents Trump and Xi on Thursday which will likely garner a lot of headlines. Indeed they already have overnight as discussed above. See our Geopolitics team's preview of the summit here. We also have opening week of the UN General Assembly debate in New York.  
In the US, the focus will increasingly shift towards next Friday’s payrolls report, which will be the most important data release before the

October FOMC meeting. Ahead of that, markets will be very keen to hear from a heavy schedule of Fed speakers throughout the week. These comments will frame last week’s FOMC meeting, where policymakers delivered a widely expected rate increase but signalled a more hawkish policy outlook. The updated projections showed a strong majority of officials anticipating further tightening, while Chair Warsh emphasised that the Committee still sees limited evidence that policy is meaningfully restrictive.  

Fed communication begins today with Chicago Fed President Goolsbee alongside the Chicago Fed National Activity Index. Tomorrow, investors receive the Philadelphia Fed non-manufacturing survey and the Richmond Fed manufacturing index. On the policy front, Fed Vice Chairs Williams and Jefferson are due to speak. Our economists view Williams as one of the four officials who are still expected to see the Fed easing by the end of next year, so any hints on that outlook will be closely scrutinised.  

Wednesday’s main event will be the September flash PMIs. Our economists expect the US manufacturing PMI to edge up to 54.0 from 53.9, while the services gauge is forecast to ease slightly to 56.1 from 56.5. Given the recent focus on AI-related investment and broader capex trends, these surveys will be watched closely for signs that business activity remains resilient. Fed Governor Barr is also due to speak. Investors will also be watching Wednesday's Treasury buyback announcement ahead of Thursday's 20-30yr operation, particularly after last month's decision to at least double the size of long-end buybacks.  

Thursday sees August new home sales and initial jobless claims. Last week continuing claims hit their lowest since January 2024. Fed speakers include Williams, Barkin, Hammack and Paulson, offering further opportunities for markets to assess where officials stand after last week’s hawkish meeting. Friday’s US durable goods report will be particularly important from a growth perspective. Our economists expect headline orders to rise by 0.6% month-on-month, with orders excluding transportation and core capital goods both expected to increase by 1.1%. The data should provide one of the clearest indications yet of whether the recent strength in business investment is being sustained. Williams and Hammack are also due to speak on Friday.  

Recapping last week now and it was a story of two halves that left most assets little changed from where they started the week. The first half saw a fresh rise in energy prices that led to renewed fears of stagflation, and we even saw the 10yr Treasury yield close above 5% for the first time since 2007. But on Wednesday, the Fed delivered their first rate hike since 2023, which seems to help ease inflation fears with a delay but the reality was that energy price falls were the more important theme reversing the yield spikes.  

Brent crude oil prices were down -0.71% on the week (-0.91% Friday), closing at $103.87/bbl after approaching $110/bbl in the first half of the week. That marked a reversal after a +17.1% jump over the previous two weeks. While oil prices stabilised, sovereign bond yields still extended their rise overall. For instance, the 10yr Treasury yield reached an intraday peak of 5.04% last Tuesday, before ending the week at 5.00%, up +2.9bps on the week (+6.5bps Friday). Meanwhile in Germany, the 10yr bund yield also hit an intraday peak of 3.57% on the Wednesday, before ending the week -1.4bps overall at 3.52%. French bonds underperformed, with the 10yr spread over bunds closing above 100bps on Friday for the first time since 2012. In absolute terms, the 10yr French yield also hit a post-2008 high on Friday of 4.56%.  

This backdrop meant equities saw modest losses last week, with the S&P 500 down just -0.08% (+0.17% Friday). The index was boosted by some of the big tech stocks, with the Magnificent 7 up +1.05% last week, marking its 4th consecutive weekly gain. However, small cap stocks struggled by comparison, with the Russell 2000 down -1.50% last week. After the AI doomerism of the previous weekend, the Philly Semiconductor index (SOX) closed up +0.73% after being down nearly -6% on Monday. Meanwhile in Europe, there were slightly larger declines, with the STOXX 600 down -0.57% (-1.11% Friday).

Elsewhere, there were some sizeable moves in FX last week, with the dollar index up +1.11% after the Fed’s hike, marking its biggest weekly gain since June. Conversely, the Japanese Yen weakened -2.08% against the US Dollar last week, which marked its biggest weekly decline since October 2025. That followed the BoJ’s 25bp rate hike, but the move was already priced in and two members voted against the hike, so markets interpreted the decision in a dovish light.

Tyler Durden Mon, 09/21/2026 - 08:36

Pages